


European households are wrestling with higher fuel and heating costs as the EU’s energy bill climbs, and that pressure keeps investors hunting for ways to put spare cash to work more efficiently. Financially solid UK penny stocks, often overlooked because of their low share prices, can offer targeted exposure without venturing into the riskiest corners of the market. This article highlights three candidates from this financially focused penny stock pool.
The three stocks highlighted here offer a compelling starting point if you want exposure to lower risk early-stage businesses with a focus on financial resilience. However, if you want the standouts, these 14 elite penny stocks are the most outstanding.
Ashmore Group (LSE:ASHM)
Overview: Ashmore Group is a London based asset manager running emerging market equity and bond funds, including smaller, lower priced issuers.
Operations: Ashmore generates £139.3 million from investment management services, with £88.4 million from the UK and Ireland and the rest across the Americas, Asia and the Middle East.
Market Cap: £1.4 billion
Ashmore Group gives this Financially Fit Penny Stocks theme a more indirect route into earlier stage and lower priced emerging market securities, since you access those through its funds rather than buying each issuer directly.
"Client activity levels at Ashmore Group are now reflected in rising subscriptions of about $12.5b for FY 2026 and the lowest redemptions in over 10 years. Any further improvement in net flows could add to management fee revenue, while a reversal would quickly pressure fee income and keep the stock grounded."
What really matters now is how one pressure on future fee margins plays out against that improving interest in Ashmore Group products.
How that tug of war plays out is exactly what sits at the heart of the full narrative for Ashmore Group, including how fee pressure and flows could eventually decouple.

W.A.G payment solutions (LSE:EWG)
Overview: W.A.G payment solutions, also known as Eurowag, runs an integrated payments and mobility platform that helps European truck fleets handle fuel, tolls and related financial transactions through fintech services like eWallets, cards and FX, alongside supporting road and fleet services.
Operations: W.A.G payment solutions generates about €2.4b from Payment Solutions and €134 million from Mobility Solutions, with revenue spread across Central and Eastern European markets including Poland, the Czech Republic, Romania and neighboring clusters.
Market Cap: £742 million
For the Financially Fit Penny Stocks theme, W.A.G payment solutions matters because its core payments engine is built around keeping fleet cash flow and working capital tighter, not looser. This focus aligns with what many smaller operators are trying to achieve.
"Rollout of Eurowag Office as a unified, cloud based platform across fuel, toll, fleet management and financial services is designed to pull multiple revenue streams into a single ecosystem, which can support higher revenue per truck and more efficient EBITDA generation over time."
What really moves the story from here is how one unresolved funding and debt pressure shapes the profitability path investors are counting on.
That funding overhang is exactly what the full narrative for W.A.G payment solutions unpacks, showing how Eurowag’s platform ambitions could accelerate or stall as the balance sheet evolves.

Currys (LSE:CURY)
Overview: Currys is an omnichannel retailer selling new, refurbished and budget consumer electronics and tech services across Currys and Elkjøp stores and online.
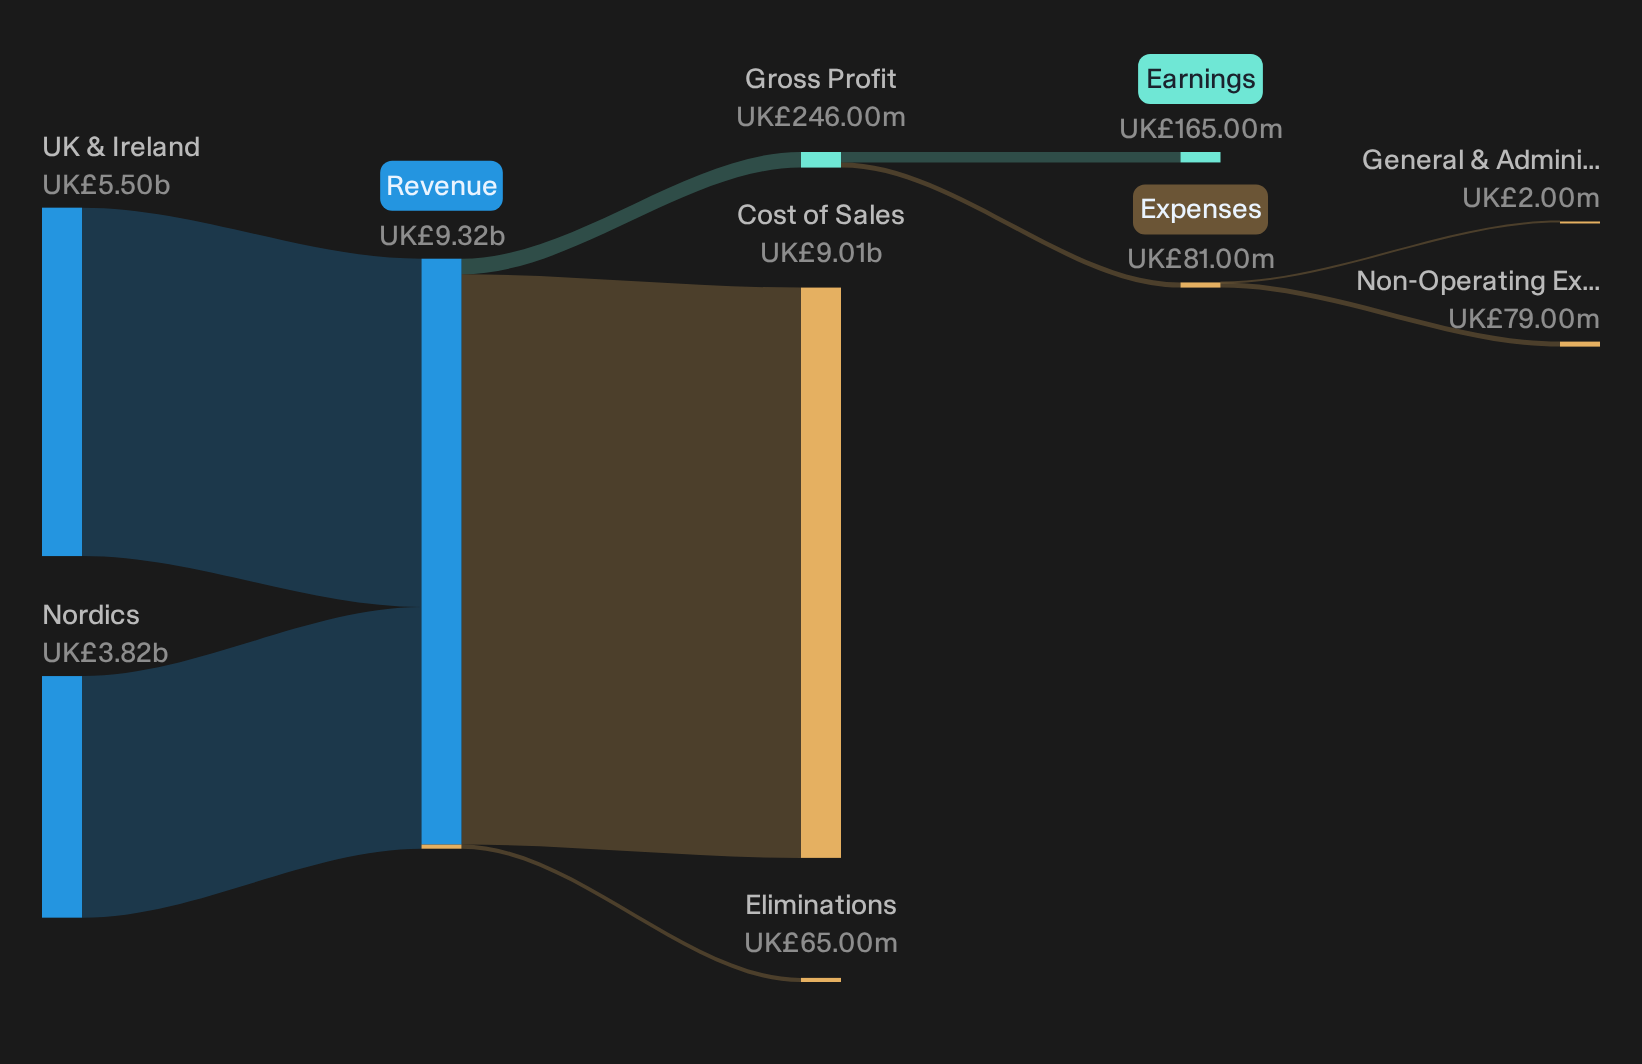
Operations: Currys generates about £5.5b from UK & Ireland and £3.8b from the Nordics, with modest eliminations between these segments.
Market Cap: £1.5b
Currys brings a different flavour to this Financially Fit Penny Stocks group, since you are getting a mature retailer that mixes low ticket refurbished electronics with recurring tech services rather than a tiny early-stage pure play.
"Expansion of higher margin recurring services such as credit, installations, connectivity and repair, which now account for over 30% of UK revenue and have been growing faster than product sales, can keep lifting Currys group revenue quality and EBIT margins as more customers shift into these offers."
What happens if one pressure on those higher margin lines quietly alters the balance between solid financial footing and future profit ambition?
If that pressure point matters to your thesis, read the full narrative for Currys to see whether Currys earnings mix is quietly compounding or at risk of stalling.
Seeking Alternatives Before Momentum Flies
Fresh opportunities rarely stay quiet for long. Once momentum builds, prices can move quickly and ideal entry points can get caught in the rush. Consider these ideas while it matters and before conditions change.
- Identify resilient operators with robust finances before they attract broader attention by running the list of solid balance sheet and fundamentals (10 results).
- Follow evolving themes in artificial intelligence and review companies already generating profits through the 38 profitable AI stocks that aren't just burning cash.
- Explore potential shifts in energy and infrastructure by using the curated 15 nuclear energy infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com