


KLA Corporation has enjoyed a powerful multiyear run in the market, and recent swings in sentiment around semiconductor equipment now put a sharper spotlight on what investors are actually paying for its earnings. After such a move, the question is whether the current share price reflects what the business is generating today rather than the stories around it.
- Over the past 5 years the stock has delivered a gain of 323.4%, which makes the current valuation hinge heavily on how durable those earnings are perceived to be.
- Recent results linked to demand from AI related chip production and high performance computing can shape expectations for future profitability and the stability of KLA's earnings base.
- Your read on KLA is one view; the desks covering it have another. See what analysts think KLA's shares could be worth.
The issue now is whether the price investors see on the screen is justified by KLA's earnings when set against the Fair Ratio benchmark.
If you are weighing KLA against other ways to play semiconductor and AI infrastructure demand, it can help to see how it compares with 54 AI infrastructure stocks.
Is KLA Fairly Priced on Earnings?
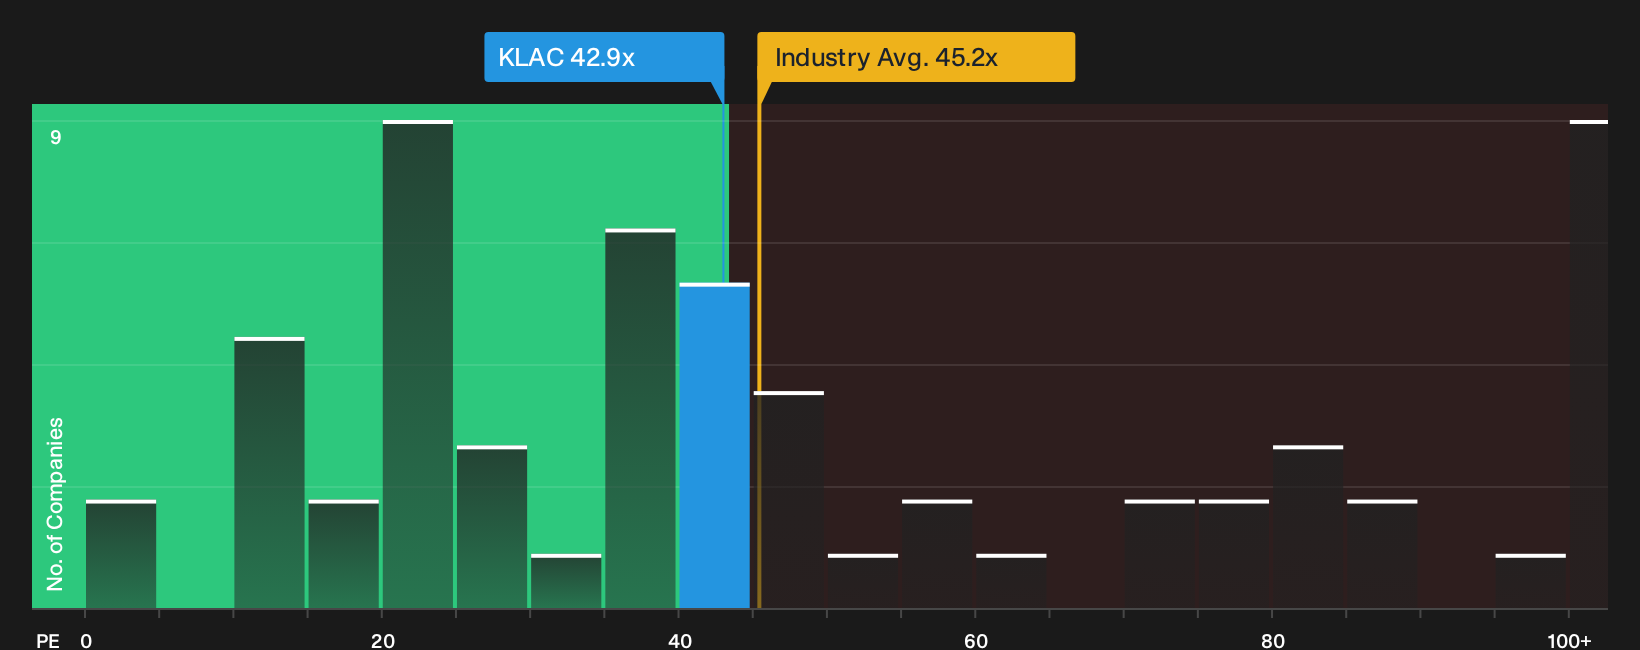
The P/E ratio is a useful lens for KLA because earnings remain a central driver of how investors frame semiconductor equipment valuations. KLA trades on a P/E of 42.9x, which is a little below the wider semiconductor sector on 45.2x but slightly above the peer group around 39.9x, so the stock is not priced at an obvious bargain or at a clear outlier premium on this metric alone.
The Fair Ratio, which reflects what investors might expect to pay given KLA's margins, growth profile, size and risk, points to the current P/E sitting very close to that tailored benchmark. Because recent results and upbeat guidance have pushed AI related expectations back into focus, this near match suggests the market is already baking those stronger earnings into the share price rather than applying a large extra uplift or steep discount. To see how much headroom that leaves relative to the Fair Ratio and peers, you can compare the full set of multiples and underlying assumptions side by side. Explore the numbers behind KLA's P/E valuation.
The KLA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where KLA's valuation puzzle leaves off. They explain which expectations for KLA's future margins, growth and earnings would need to occur for the stock to be worth meaningfully more or materially less than it is today. Rather than relying on a single multiple or model output, each narrative sets out the assumptions behind its view of fair value so you can compare those inputs with actual results as they are reported.
One of the top community narratives on KLA: 32% undervalued
"The main thing that has to go right is that KLA continues to convert its large, long dated backlog and process control share gains…"
Discover why this Narrative puts KLA at 32% undervalued.
The KLA valuation still sidesteps one crucial angle
Everything so far has focused on what KLA looks like today, yet professional coverage also sketches where this business might be a few years from now. This gives you one more lens to compare with the current pricing. Explore where analysts expect KLA to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com