


Vulcan Materials (VMC) heads into Thursday’s earnings update with two focal points for investors. The upcoming results sit alongside news that senior executive David P. Clement plans to retire in early 2027.
Vulcan Materials has seen momentum pick up into the earnings date, with a 30 day share price return of 7.66%. This comes even as the year to date share price return is down 9.45%, while the 3 year total shareholder return of 32.96% points to a stronger longer term picture.
See how Vulcan Materials compares with other construction-linked stocks that are demonstrating resilient earnings momentum and solid balance sheets using our hand picked list of solid balance sheet and fundamentals (24 results)
Bulls see recent earnings beats and long term shareholder returns backing Vulcan Materials at US$265. Bears point to the share price pullback and an expected revenue dip. Which side does the valuation support next?
Most Popular Narrative: 15% Undervalued
Vulcan Materials is trading at $265, just under the most widely followed fair value narrative of about $311 per share. This frames the current debate around cost pressure, pricing power, and infrastructure demand.
Accelerating infrastructure spending driven by the ongoing rollout of IIJA funding, major state initiatives in core Southern and Sunbelt markets, and increasing local spending is still expanding Vulcan Materials' exposure to highway and public works projects, with highway awards in its markets up 12% and public infrastructure awards up 20%, which supports future aggregates volumes and revenue.
See why 14 investors see Vulcan Materials as 15% undervalued.
Result: Fair Value of $311 (UNDERVALUED)
Still, higher diesel costs pressuring cash costs and cautious views on 2027 public spending could derail the current Vulcan Materials undervaluation story.
Find out about the key risks to this Vulcan Materials narrative.
Another View: Vulcan Materials Looks Expensive On Earnings
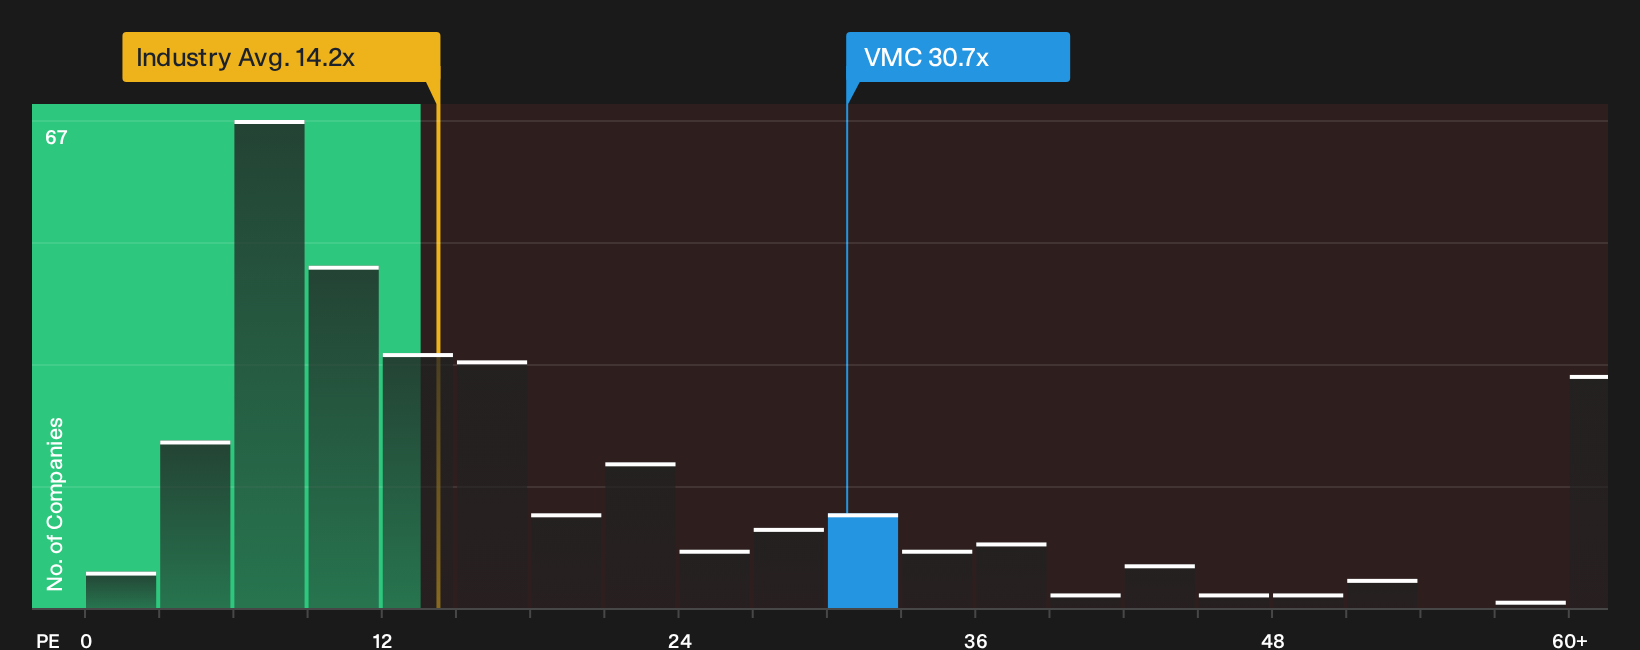
The first narrative presents Vulcan Materials as roughly 15% undervalued around $265. A different lens using the P/E ratio points the other way. VMC trades on about 30.7x earnings, while the global Basic Materials group sits near 14.2x and direct peers around 22.3x.
The fair ratio implied for Vulcan Materials is closer to 20x. That is a wide gap and it suggests investors today are paying a premium that could compress if sentiment cools or growth stays in line with current forecasts rather than surprising higher. Which story matters more for you: the almost in line DCF style fair value, or the richer earnings multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across Vulcan Materials can either look like an opportunity or a warning. Move quickly to weigh the data, stress test your thesis, and see the full picture across 3 key rewards and 2 important warning signs
Looking for more Vulcan Materials sized opportunities?
Do not stop at Vulcan Materials. Broader context from other ideas can sharpen your judgement and help you spot where risk and reward look more attractive.
- Target potential mispricings by scanning a curated 26 high quality undervalued stocks that filters for strong fundamentals and more attractive entry points.
- Lock in income focused ideas by reviewing a focused set of 6 dividend fortresses that prioritise yield alongside balance sheet strength.
- Dial back downside risk by zeroing in on a 32 resilient stocks with low risk scores that highlights resilience when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com