


United Bankshares (UBSI) drew investor attention after its third quarter update on October 22, 2026, which paired stable earnings with lower net charge offs and the completion of recent share repurchase activity.
At a share price of US$48.05, United Bankshares has pulled back slightly over the past day but still carries a 30 day share price return of 2.85% and a year to date share price gain of 25.16%. Long term investors have seen a 39.17% 1 year total shareholder return and a 90.62% total shareholder return over three years, suggesting momentum has built over time as earnings, credit costs and buybacks reshape how investors weigh the bank’s growth potential against perceived risk.
Compare United Bankshares' recent Q3 momentum with a hand picked 32 resilient stocks with low risk scores that also pairs earnings resilience with conservative balance sheets.
Bulls point to United Bankshares' solid credit metrics and share buybacks, while bears focus on flat quarterly earnings. As the recent rally cools, investors are asking which case the current valuation appears to favor.
Preferred P/E of 12.6x: Is it justified for United Bankshares?
United Bankshares is being valued at a P/E of 12.6x, which sits below its own estimated fair P/E of 11.2x yet slightly above the wider US Banks average of 11.5x, so the current $48.05 share price reflects a mixed message from different valuation lenses.
The P/E ratio compares what investors pay for each dollar of earnings. For a lender like United Bankshares, this metric often reflects how the market weighs earnings resilience, credit quality and growth potential in a single number rather than just near term profit prints.
Here, the stock looks expensive relative to the SWS fair ratio work, which points to an 11.2x level the valuation could gravitate toward over time, while still coming in cheaper than the peer group average of 13.7x where similar banks trade. That tension suggests investors are paying a modest premium against the fair ratio for United Bankshares but not a premium against comparable US banks.
Explore the SWS fair ratio for United Bankshares.
Result: Price-to-earnings of 12.6x (ABOUT RIGHT)
Still, flat quarterly earnings and a P/E above United Bankshares' own fair ratio estimate could leave the stock exposed if credit costs or loan demand weaken.
Find out about the key risks to this United Bankshares narrative.
Another View on United Bankshares: Cash Flows Paint a Different Picture
The P/E work presents United Bankshares as slightly expensive versus its own fair ratio, yet our DCF model points the other way. At $48.05, UBSI is trading about 31.6% below an estimated future cash flow value of $70.26. This frames the recent rally as potentially conservative rather than stretched. Which lens do you trust more when earnings are steady but not fast growing?
Look into how the SWS DCF model arrives at its fair value.
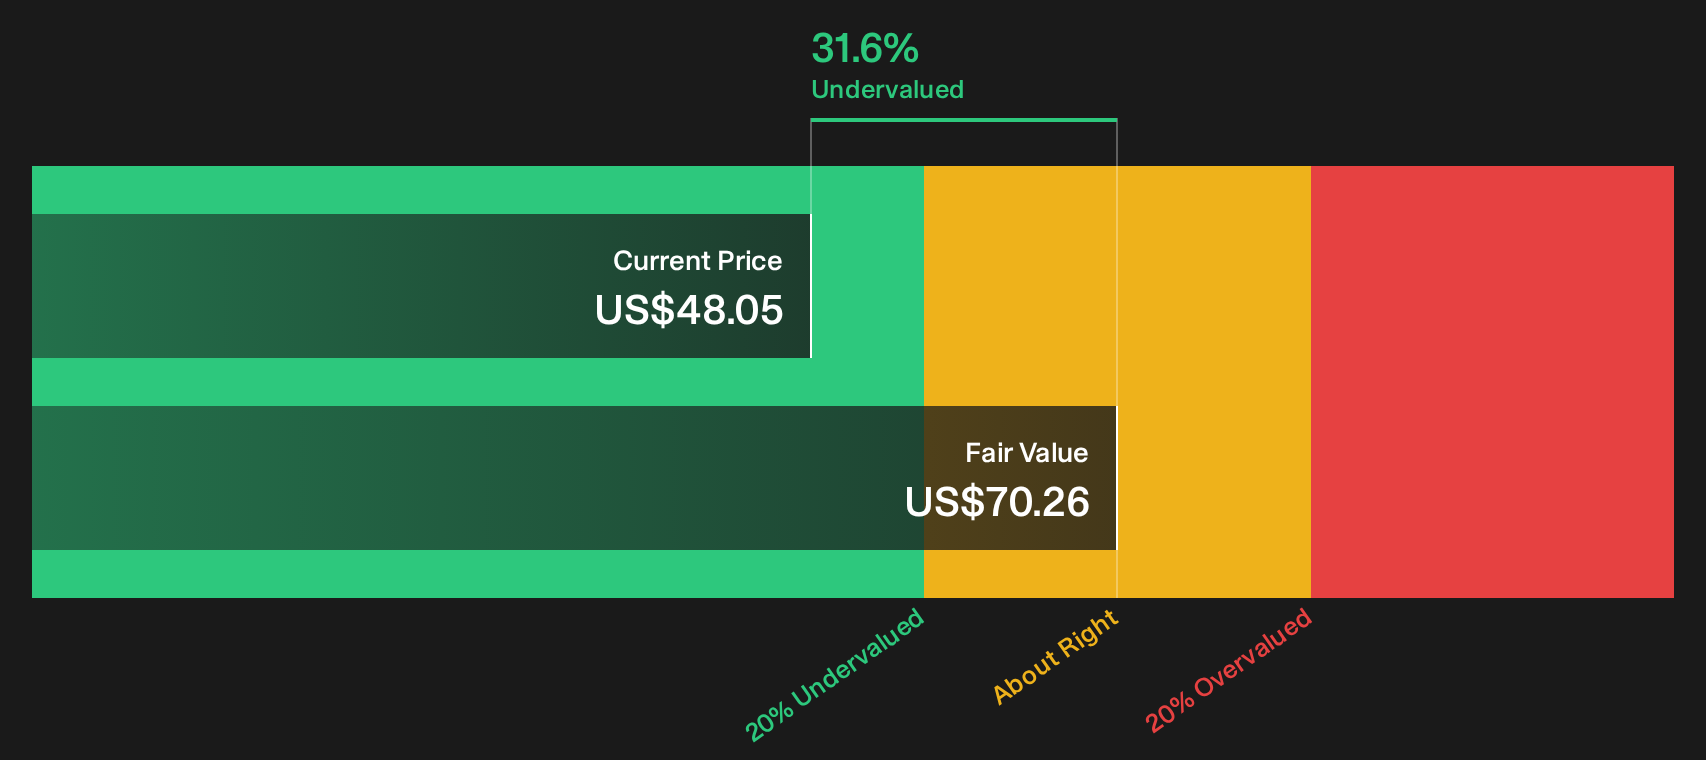
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United Bankshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 26 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
See the mixed signals on United Bankshares as a prompt rather than a verdict, and review the numbers yourself while sentiment is still settling. To evaluate the potential drivers that current shareholders are watching closely, take a closer look at the 3 key rewards
Looking for more investment ideas beyond United Bankshares?
If United Bankshares has sharpened your focus on valuation and risk, now is the moment to broaden your watchlist before the next wave of opportunities moves without you.
- Target resilience first by scanning a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses with balance sheets designed to handle tougher conditions.
- Hunt for mispriced potential through a 19 high quality undiscovered gems that highlights quality companies the wider market may not be watching closely yet.
- Prioritise downside protection with a 32 resilient stocks with low risk scores aimed at stocks that pair measured volatility with more robust fundamental profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com