


Pfizer has quietly put together a solid rebound, with the share price back near the high twenties, and investors are asking whether that move lines up with what the business is currently earning. After a period defined by product news in oncology and vaccines, the real question is how much of that story is already embedded in the valuation.
- The stock has delivered a 29.7% return over the past year, which puts more focus on whether the recent gains rest on a sustainable earnings base.
- Fresh clinical and regulatory milestones in cancer and vaccines, including new data on ELREXFIO and expanded use of Talzenna plus Xtandi, can influence how the market views future profit potential and the timing of cash flows.
- Your read on Pfizer is one view; the desks covering it have another. See what analysts think Pfizer's shares could be worth.
The issue now is whether Pfizer's current share price is justified by the earnings power that investors can reasonably tie to the business today.
If you are weighing Pfizer against other health-focused ideas, a targeted screen of 36 healthcare AI stocks may be helpful.
Is Pfizer Getting Expensive on Earnings?
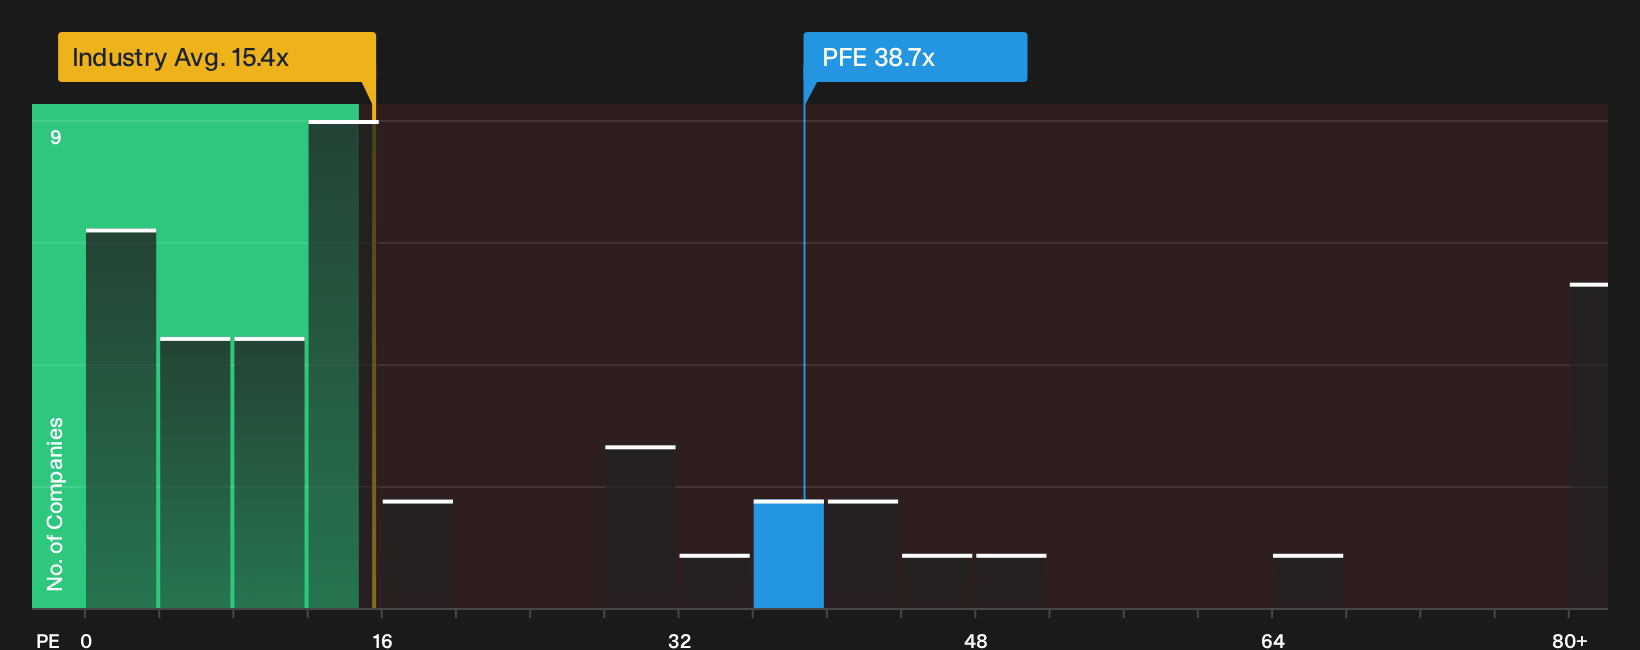
The P/E ratio fits Pfizer because investors often focus on how much they are paying for each dollar of current earnings in large, established drug companies. On this lens, Pfizer trades on a P/E of 38.7x, which is above the pharmaceuticals industry average of 15.4x and also above the peer group on roughly 57.4x, pointing to a market view that is already assigning a rich price tag relative to typical sector earnings levels.
The tailored fair value framework, which estimates the P/E you might expect after accounting for Pfizer's business profile, points to a lower figure than where the shares trade today, so the stock screens overvalued on this measure. Because recent cancer and vaccine trial news has been positive, including the strong Phase 3 data for ELREXFIO, that premium multiple appears tied to expectations that the pipeline will justify paying up for every dollar of profit. Explore the numbers behind Pfizer's P/E valuation.
The Pfizer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate on Pfizer leaves off by spelling out the kind of growth, margin profile and earnings path that would need to hold for the current share price to look meaningfully high or low relative to today. Rather than relying on a single multiple or model output, each one lays out the assumptions that sit behind its view of fair value so you can compare those inputs with Pfizer's actual results as they come through.
Community views on Pfizer are now split between investors who see more upside in the story and others who think expectations are already baked in.
Bull case: 18% undervalued
"Management’s stated intent to preserve the dividend even under stretched scenarios and to resume dividend growth after the 2028 loss of exclusivity period…"
Discover why this Narrative puts Pfizer at 18% undervalued.
Bear case: roughly fairly valued
"Pfizer continues to rely on a shrinking COVID portfolio alongside a heavier investment load in obesity and oncology…"
Explore why this Narrative puts Pfizer at roughly fairly valued.
The Pfizer story is not complete without a closer look at its risk checks
Price and earnings only tell part of what you need to know about Pfizer, since our research has also highlighted specific risk checks that could change how you view the whole picture. Take a closer look at 4 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com