


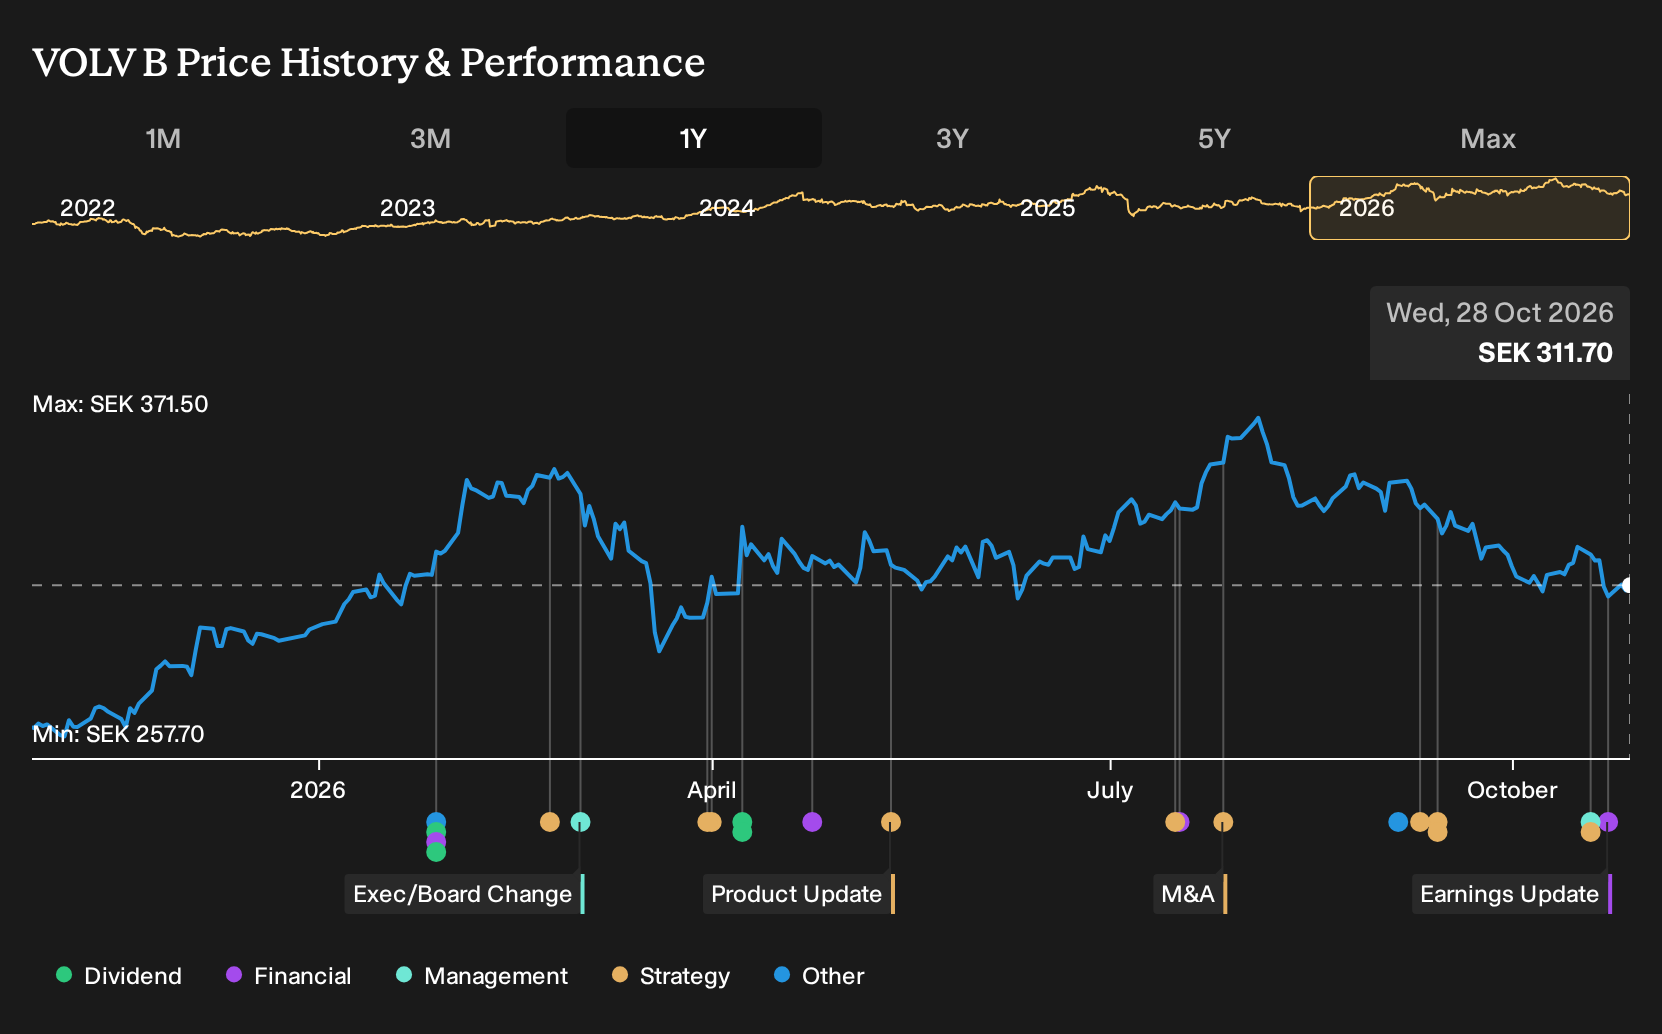
If you had put money into AB Volvo a year ago and simply left it alone, the result would look very different today. Investors who held AB Volvo over the past year are up 23.7%, including dividends. That outcome now sits against a backdrop of fresh headlines on autonomous freight routes in Texas, new electric truck platforms, job cuts, and regulatory pressure. If you were deciding on 28 October 2025, which factor would matter more: the promise of electrification or the execution risks?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made AB Volvo harder to judge, start where the gap is still open and scan 189 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On AB Volvo
The shares cost SEK261 at the start of the period. Anyone looking at AB Volvo then had to choose between two very different but reasonable stories about where the business might be heading.
On the optimistic side, the bull Narrative put Fair Value at SEK300, or 15% above the start price. That view leaned on faster electrification and digitalization, plus the idea that services and aftermarket activity could support higher margins and steadier earnings.
The cautious case set Fair Value at SEK240, or 8% below the start price. This bearish Narrative focused on rising regulation and tariffs, slower progress in zero emission fleets, and the risk that cost inflation and underused electric assets would squeeze profitability.
What The Evidence Did To The AB Volvo Argument
AB Volvo pushed ahead with autonomous freight routes in Texas and unveiled new electric and low carbon powertrains, which backed the optimistic story about electrification, digital services, and higher quality revenue. At the same time, Volvo announced 2,500 job cuts tied to a sales slump and pulled guidance, which echoed the cautious case on regulation, weaker demand, and margin pressure. Overall, the new information cut both ways.
The lesson is simple. When a thesis hangs on cleaner technology and better profitability, it can help to track reported net margin alongside product news. Evidence such as Q3 2026 net margin at 9.0% versus 6.8% a year earlier is the type of hard number that can either support or undercut any story you hear at another industrial group.
What AB Volvo's Price Already Assumes
AB Volvo now trades at SEK312, with this cautious Narrative placing its Fair Value below that level. The gap reflects concern that progress in electrification and automation may not fully offset pressure from regulation, cost inflation, and slower truck and construction cycles.
The question is what must keep going right for SEK312 to hold. A buyer at this price has to judge whether Volvo can fund and scale cleaner technology while legacy engine assets, tariffs, and supply chains still strain margins.
"Structural cost inflation in batteries, raw materials, and labor remains a persistent threat as Volvo is forced to concurrently maintain costly legacy operations and invest in capital-intensive electrification and automation initiatives, placing ongoing pressure on cost structure and net margin expansion over the coming decade."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 32% below our estimate - targets data centre build outs needing dense GPU racks and compatible software.
- Company 2 - 23% below our estimate - ties AI workloads to entrenched cloud, productivity and developer tooling subscriptions.
- Company 3 - 41% below our estimate - shifts from underwear toward higher margin sports apparel for health oriented athletes.
Those are three of them. See all 204 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com