


Taiwan Semiconductor Manufacturing (NYSE:TSM) is back in focus after management used its Q3 2026 earnings call to highlight sustained AI chip demand and an accelerated plan for global capacity expansion.
Against this AI backdrop, Taiwan Semiconductor Manufacturing’s recent moves on pricing and capacity come after a strong run in the market, with the share price at US$439.51 and a year to date share price return of 37.51% paired with a very large 3 year total shareholder return. That momentum has not been one way, however, since the 30 day share price return is down 2.95% even as the 90 day share price return is 8.98%. This suggests traders are weighing shorter term cost pressures against the longer term AI driven capacity story.
Scan beyond Taiwan Semiconductor Manufacturing and compare its AI-driven capacity story with a curated set of 54 AI infrastructure stocks powering the same build out in chips and data centers.
Taiwan Semiconductor Manufacturing looks like a powerhouse in AI hardware, yet a powerful story is not the same as a well priced stock. So what are investors actually paying for that AI capacity today?
Most Popular Narrative: 16% Overvalued
Taiwan Semiconductor Manufacturing closed at $439.51, while the most followed narrative pegs fair value at $378.29. This implies the market is placing a premium on the AI capacity story compared with that valuation anchor.
TSMC is the rarest of things: a monopoly whose dominance is rooted not in regulatory capture or historical accident, but in genuine technological supremacy. The company has spent decades perfecting the art of manipulating matter at atomic scales, and the cumulative knowledge embedded in its fabrication processes is essentially irreproducible.
See why 133 investors see Taiwan Semiconductor Manufacturing as 16% overvalued.
According to tripledub, that premium price comes with clear conditions. The narrative sets a fair value at $378.29 per ADR with a required 25% discount to that figure before calling the margin of safety acceptable for Taiwan Semiconductor Manufacturing.
The same narrative points to three clear break points that would undermine that valuation, including a severe disruption to Taiwan based fabrication, loss of apex clients to rival foundries, or a new computing paradigm that makes leading edge silicon uneconomic. Each of those hinges on structural rather than quarter to quarter issues, which is why the analysis leans heavily on long term cash generation and geopolitical concentration instead of near term growth rates.
For readers, the key takeaway is simple. At the current $439.51 share price the most popular narrative on Simply Wall St views Taiwan Semiconductor Manufacturing as trading above its $378.29 appraisal, so any thesis built on that framework assumes limited valuation cushion and elevated sensitivity to adverse scenarios.
Result: Fair Value of $378.29 (OVERVALUED)
Still, the Taiwan Semiconductor Manufacturing story hinges on fragile points, including any severe disruption to Taiwan based fabs or a decisive shift of flagship customers to rival foundries.
Find out about the key risks to this Taiwan Semiconductor Manufacturing narrative.
Another View: Taiwan Semiconductor Manufacturing Through The Market’s Lens
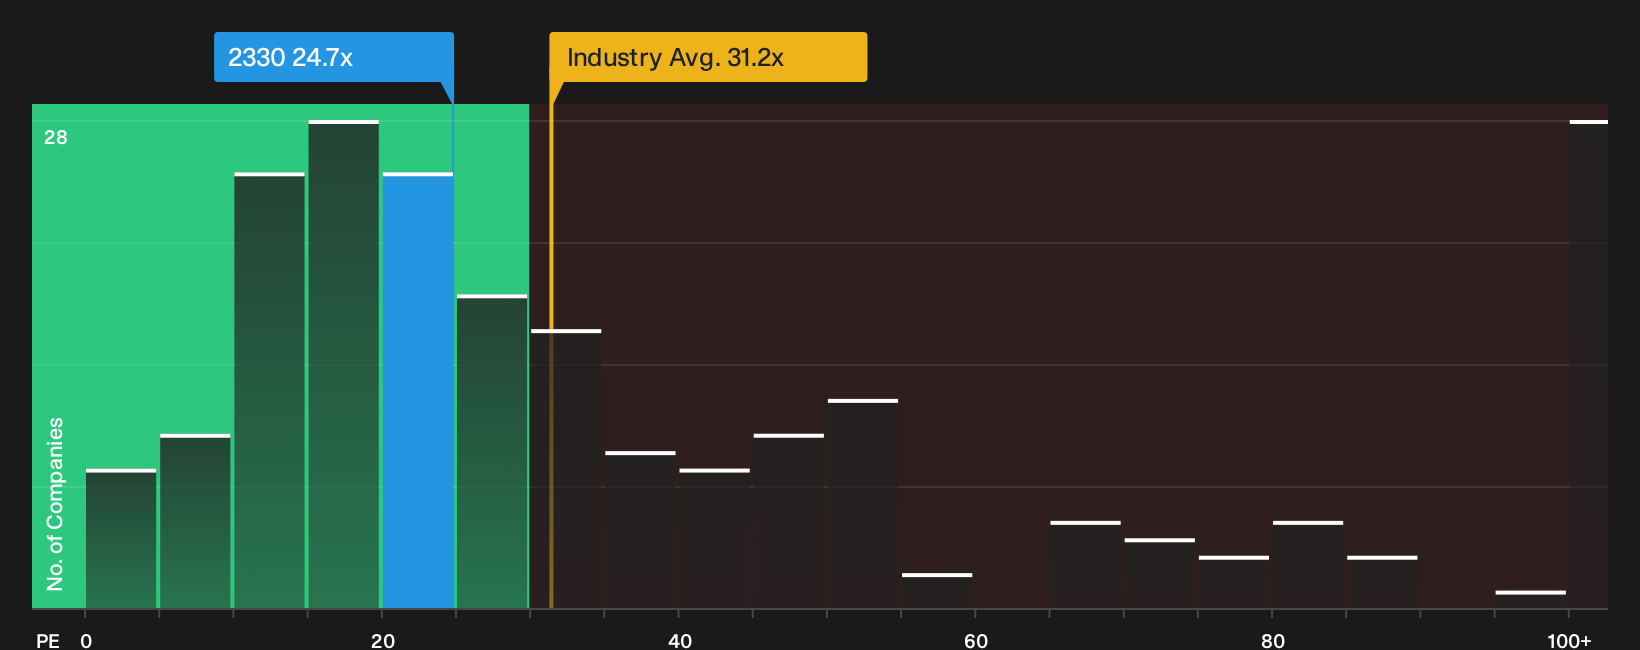
The first narrative calls Taiwan Semiconductor Manufacturing about 16% overvalued at $439.51 versus a $378.29 fair value. Yet on simple P/E math, the picture looks very different. TSM trades at 24.9x earnings against a US Semiconductor industry on 45.2x and peers near 57.5x, while its fair ratio sits at 42.6x. That gap implies investors are paying a lower earnings multiple for a business the regression work suggests the market could move toward over time. Is that a valuation cushion, or just the price of concentrated geopolitical risk?
For readers who want to see how those earnings multiples stack up in detail and how pricing pressure or multiple expansion would flow through the numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split view on Taiwan Semiconductor Manufacturing leaves you undecided, pull up the key numbers now and pressure test both the upside and the downside in your own model. To help frame that judgment, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Taiwan Semiconductor Manufacturing?
If the Taiwan Semiconductor Manufacturing story feels finely balanced, it may be worth widening your field of vision now so you are not relying on a single AI heavyweight.
Use the Simply Wall St Screener to search for ideas that match your risk appetite, income needs, and preference for strong balance sheets.
- Target potential mispriced opportunities by focusing on a 26 high quality undervalued stocks that combines solid fundamentals with compelling P/E and cash flow profiles.
- Build a steadier income stream by scanning for a 6 dividend fortresses that aims to pair higher yields with resilient cash generation.
- Dial back portfolio risk by concentrating on a 32 resilient stocks with low risk scores that scores well on financial strength and volatility metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com