


Southeast Asia is quietly becoming one of the busiest workshop floors in the global chip supply chain, as exporters, policymakers and multinationals pull more semiconductor work into Malaysia, Singapore, Vietnam, Thailand and the Philippines. For investors, that shift could mean fresh opportunities in companies exposed to AI-driven chip demand, new packaging capacity and “China plus one” investment. This article examines three stocks from our regional semiconductor screener that are closely linked to this trend.
The three stocks that follow are just a sample from this theme. The full screen surfaced 14 more Southeast Asia semiconductor manufacturing and packaging companies with equally compelling narratives that are not covered here. To go deeper into the opportunity set, identify your own filters, and analyze potential high-conviction ideas directly, head into the Southeast Asia Semiconductor Manufacturing & Packaging screener.
Unisem (M) Berhad (KLSE:UNISEM)
Unisem (M) Berhad is a Malaysia based pure-play chip assembly and test specialist, closely linked to Southeast Asia’s push into back-end packaging. It generates about MYR2.0b from semiconductor devices and related services and carries a market value of roughly MYR7.2b.
Unisem (M) Berhad provides direct exposure to the region’s efforts to move up the chip value chain, with assembly, advanced packaging and testing all under one roof for customers across Asia, Europe and the US. Expansion of its Gopeng plant for AI related wafer bumping, together with the funding and execution choices around that build, will be important for potential returns on this theme.
Those capital and execution choices could be pivotal, so review the 3 key rewards and 1 important warning sign to see what might accelerate Unisem (M) Berhad or limit its potential upside.

AEM Holdings (SGX:AWX)
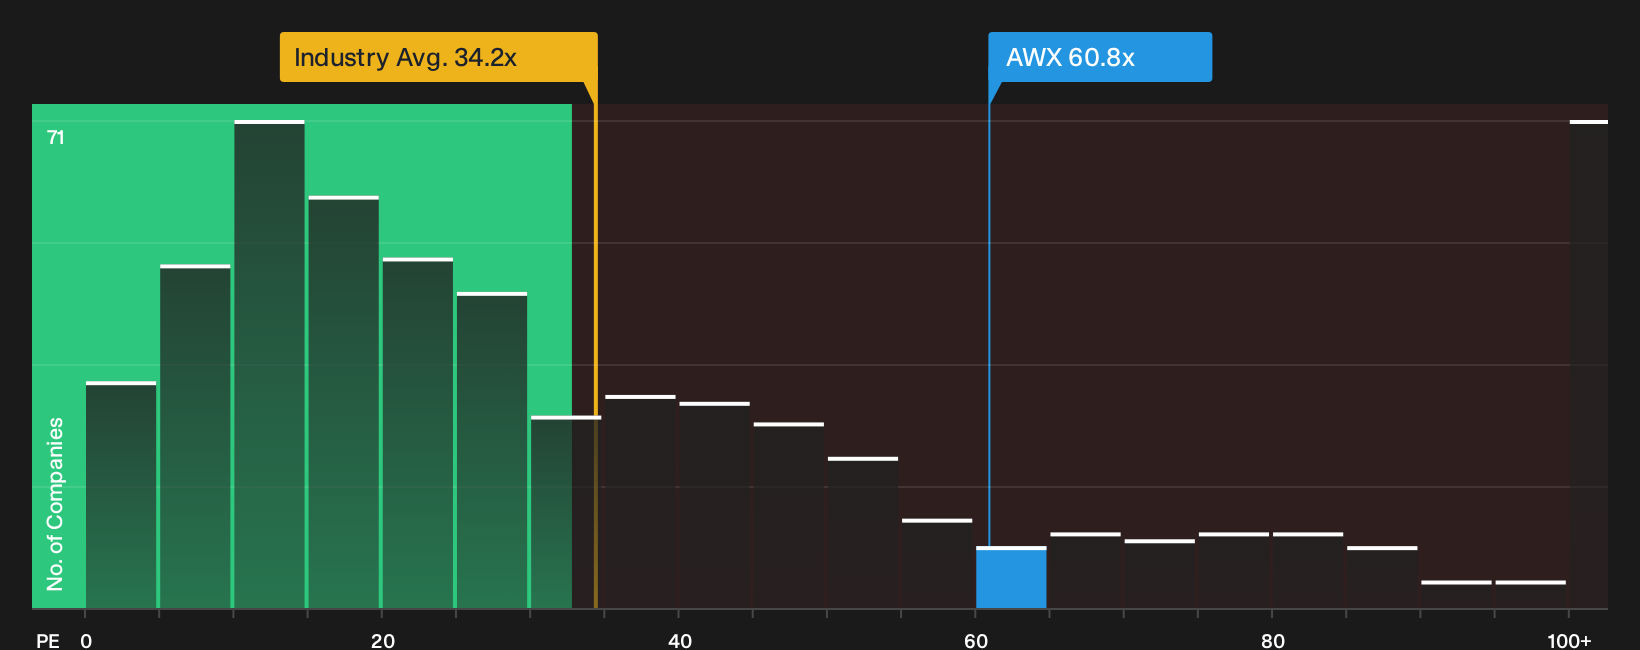
AEM Holdings plugs directly into the Southeast Asia Semiconductor Manufacturing & Packaging theme through its semiconductor testing platforms, from burn in and system tests to handler hardware and thermal control kits. Most revenue comes from Test Cell Solutions at about $313 million and Contract Manufacturing at roughly $158 million, with a market value near $2.7b.
AEM Holdings sits in the testing lane of the Southeast Asia chip supply chain, serving advanced processors that need more complex inspection as AI workloads spread. Recent profitability in this cycle backed by higher earnings points to leverage to regional capacity build outs, depending on how one unseen pressure shapes future pricing power and customer orders.
That invisible pressure point matters for AEM Holdings, so check the 3 key rewards and 2 important warning signs to see whether pricing power is quietly building or at risk of stalling.
Mi Technovation Berhad (KLSE:MI)
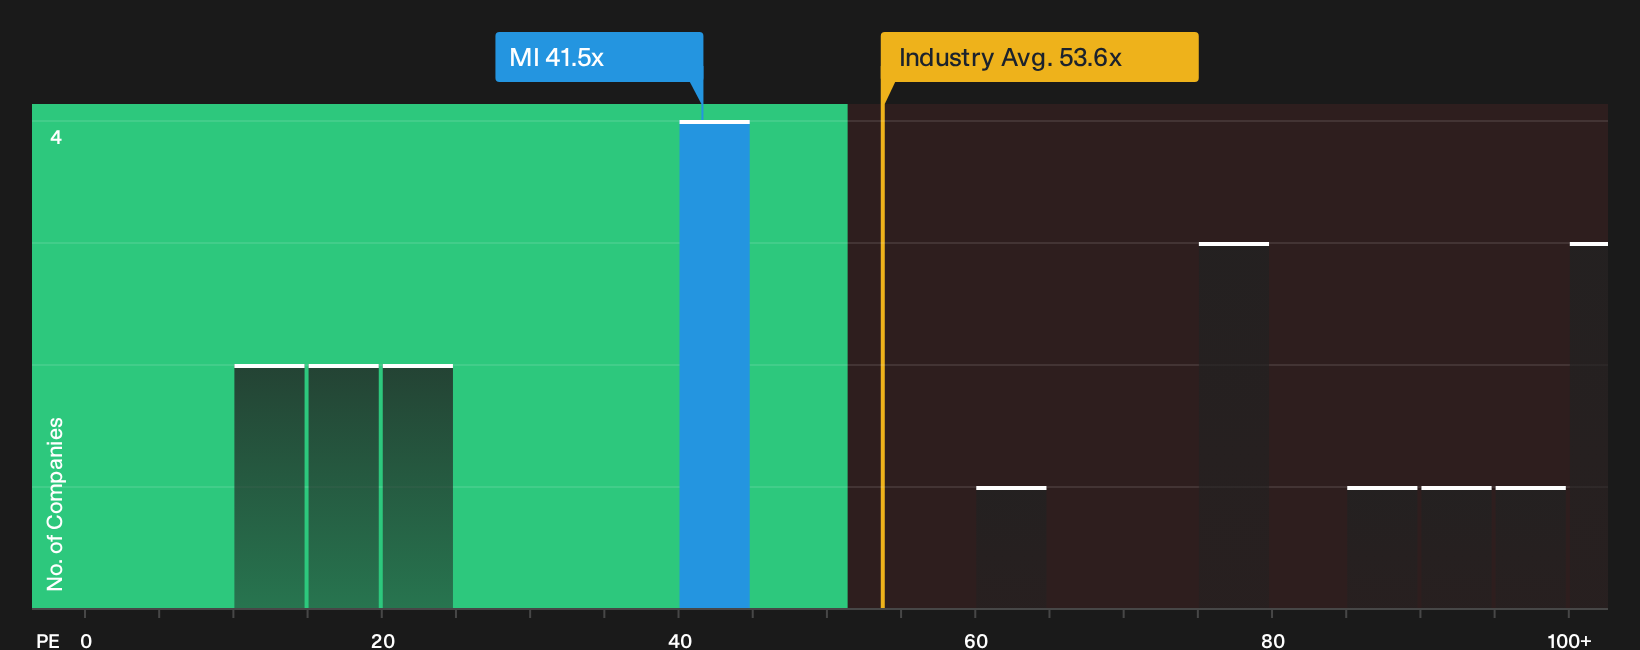
Mi Technovation Berhad designs and sells semiconductor manufacturing tools that support front end processing and advanced packaging in the Southeast Asia supply chain, earning about MYR380.7 million from materials and MYR362.9 million from equipment, and carries a market value near MYR6.1b.
Mi Technovation Berhad provides exposure to the toolmakers that keep Southeast Asia’s chip fabs and advanced packaging lines running, with meaningful earnings momentum and a P/E below regional semiconductor peers. The appeal of that set up ultimately depends on how one crucial cost of capital trade off shapes future returns.
That trade off is exactly what the 4 key rewards and 1 important warning sign unpacks so you can see where Mi Technovation Berhad’s upside and pressure points might really be hiding.
Seeking Fresh Alternatives Beyond Semiconductors?
Markets move fast. The most interesting ideas often break out quietly, build momentum and are flying under the radar for now. Do your homework while it matters and get in early.
- Spot early turnarounds and smaller companies with room to move by scanning a curated group of 132 elite penny stocks with strong financials before everyone else starts talking about them.
- Ride structural tailwinds in automation and factory upgrades by combing through a focused basket of 93 robotics and automation stocks while the best setups are still being overlooked.
- Position ahead of infrastructure upgrades and potential capacity squeezes by reviewing a filtered universe of 43 power grid technology and infrastructure stocks before pricing fully reflects the opportunity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com