


Bylaw overhaul and dividend reaffirmation set the stage
Southern (SO) has just overhauled its corporate bylaws and reaffirmed a regular dividend, giving investors fresh information on governance rules and cash returns as the next earnings date approaches.
Southern’s share price has climbed 11.14% over the past 30 days to US$91.52, even though it slipped 1.22% in the latest session, while the 1 year total shareholder return of 1.10% contrasts with a much stronger 48.31% three year total shareholder return. This suggests that long term momentum has cooled even as nearer term interest picks up around the bylaw changes, dividend reaffirmation and the upcoming November earnings release.
Scan how Southern compares with other regulated utilities by reviewing a curated set of 32 resilient stocks with low risk scores built around balance sheet resilience and steadier return profiles.
After an 11% climb to US$91.52 and a modest discount to the average analyst target, the bigger gap now sits between Southern’s trading price and longer run fair value estimates. How wide is it really?
Most Popular Narrative: 6% Undervalued
On Simply Wall St's most followed narrative, Southern’s estimated fair value of $97.08 sits above the latest close at $91.52. This puts the recent price strength into a different light for anyone weighing upside against execution risk.
Ongoing execution of a multiyear build program, including 10 GW of approved company owned generation plus multiple large battery and gas projects in Georgia and about US$700 million of gas uprates at Southern Power targeting 400 MW of additional capacity, provides a defined capital expenditure pipeline that can expand earnings and the regulated asset base over time.
See why 68 investors see Southern as 6% undervalued.
Result: Fair Value of $97.08 (UNDERVALUED)
Still, the narrative around Southern can break if large generation and storage projects stumble, or if ongoing equity issuance leaves earnings per share lagging headline growth.
Find out about the key risks to this Southern narrative.
Another View: Southern’s Price Tag Looks Full
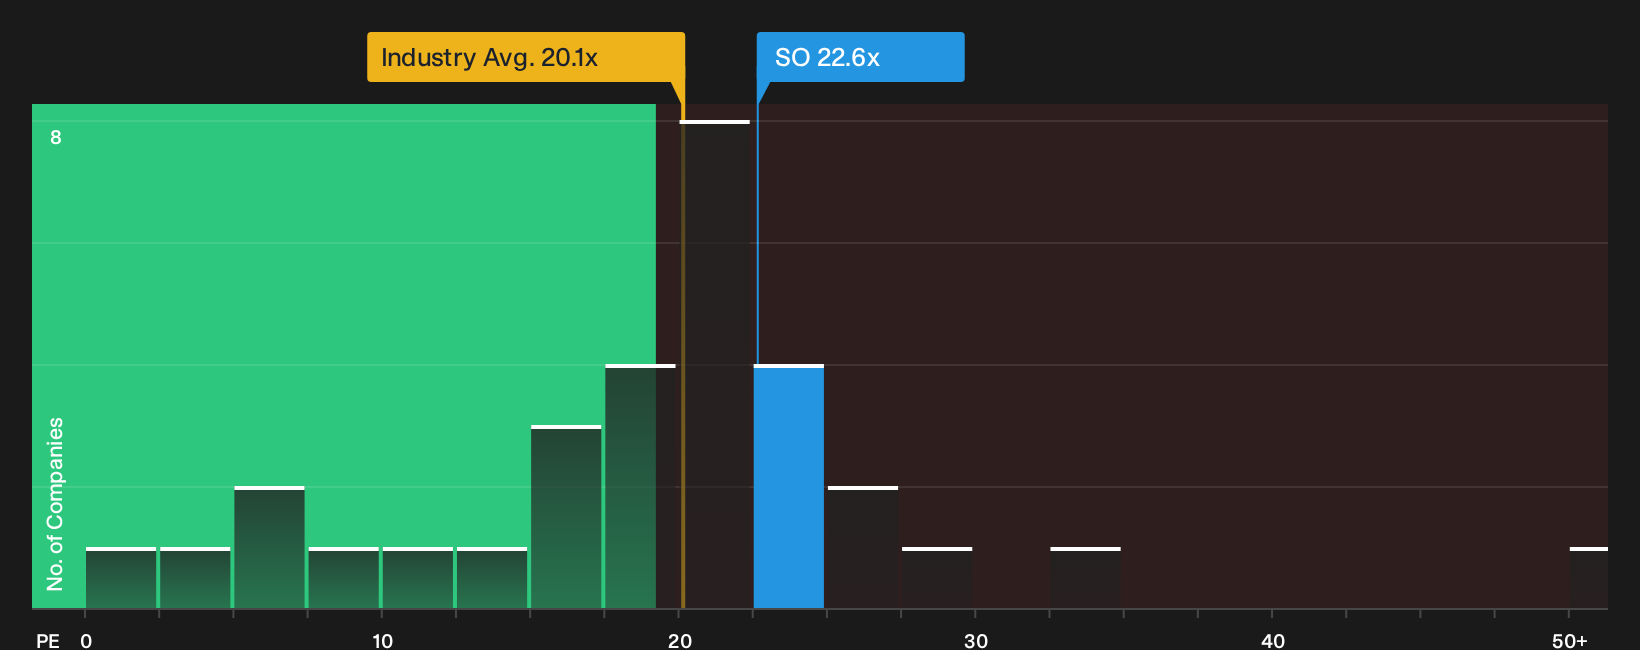
The story changes when you switch from fair value estimates to simple earnings multiples. Southern trades on a P/E of 22.6x, slightly above its own fair ratio of 22.3x and ahead of the US Electric Utilities average of 20.1x. That premium suggests more valuation risk than clear upside, so what justifies paying extra?
See what the numbers say about this price in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Southern so far. If you want to move from headlines to your own judgment, consider both the potential risks and rewards and review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Southern?
If Southern is already on your radar, give yourself an edge by lining up a few alternative options that match your risk tolerance and income goals.
- Boost your watchlist quality by scanning a list of solid balance sheet and fundamentals (24 results) that spotlights companies with sturdier finances and room to handle shocks.
- Hunt for potential value opportunities by reviewing a 26 high quality undervalued stocks focused on stronger fundamentals that the market may be pricing cautiously.
- Build a steadier income stream by checking a 6 dividend fortresses that highlights higher yielding payers with more robust cash support for distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com