


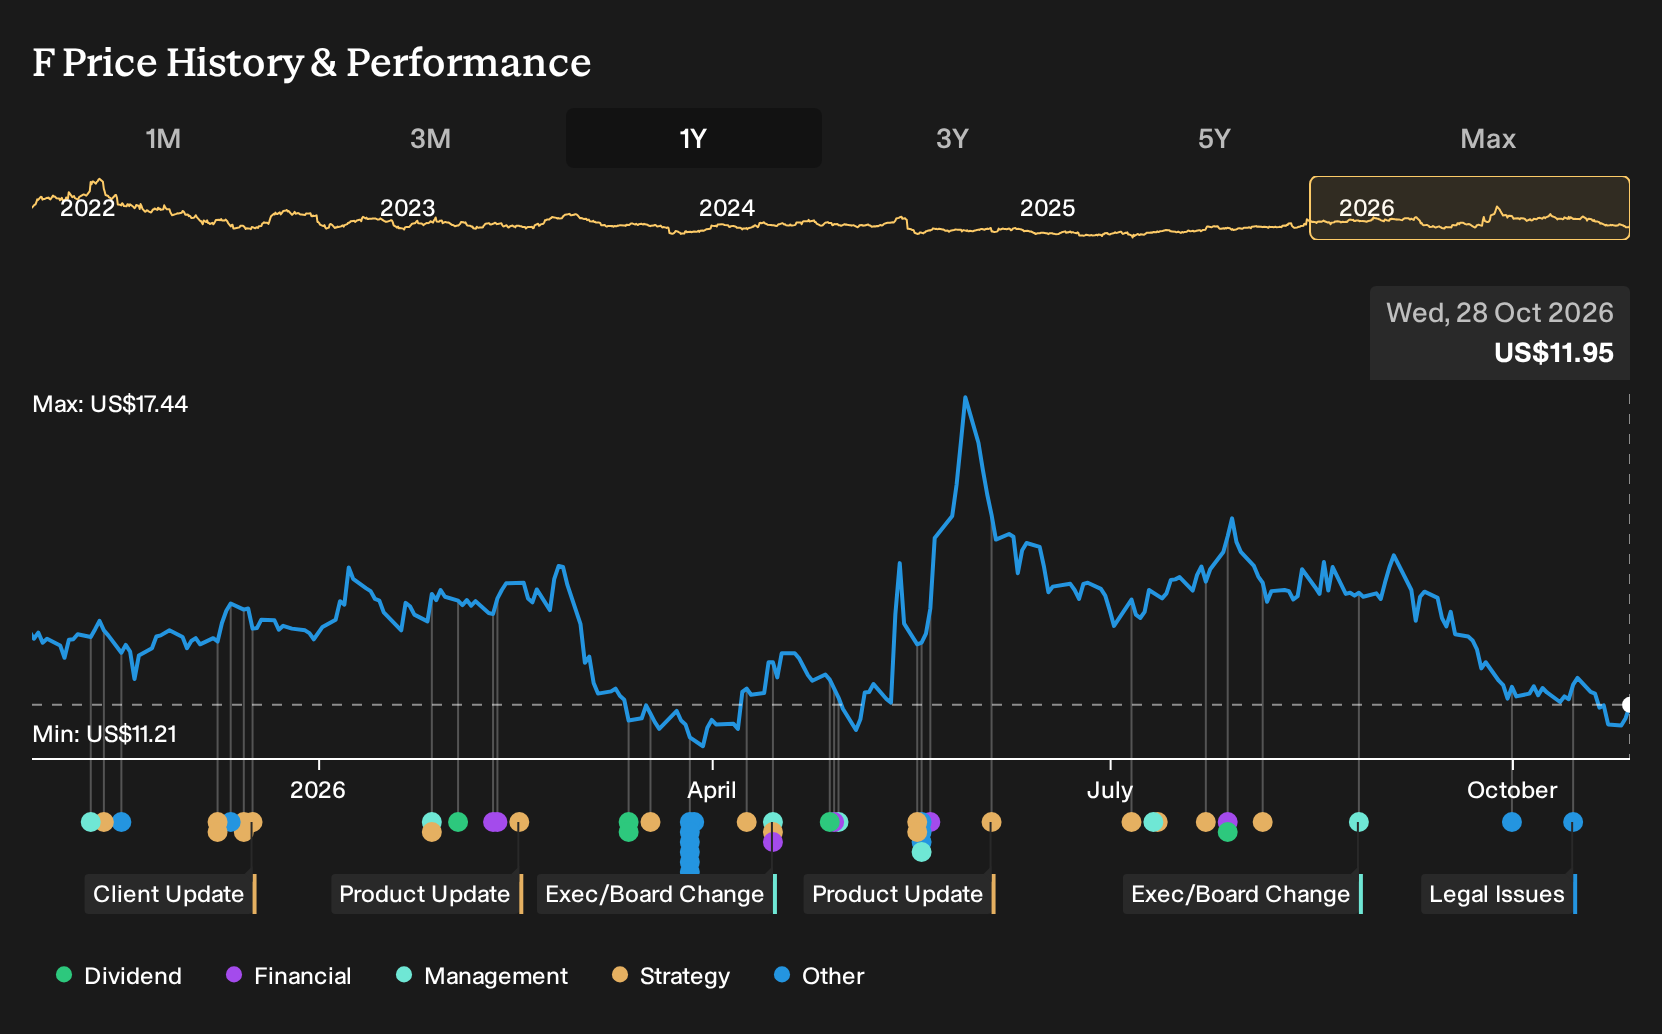
- Ford Motor reported third quarter 2026 revenue of US$49,526 million and net income of US$2,049 million, with nine month net income of US$3,270 million and a fourth quarter dividend of US$0.15 per share declared.
- Better than expected third quarter profitability, including segment strength in Ford Credit and Ford Blue along with a higher full year earnings outlook, highlights how cost control and higher margin services are influencing Ford Motor's results.
- The focus now shifts to how Ford Motor's improved earnings guidance and profitability mix could reshape its longer term investment narrative.
Ford Motor Investment Narrative Recap
To own Ford Motor today, you need to believe the business can turn stable but flat revenue into healthier profit through tighter costs, better product mix and higher margin services. The third quarter shows that story in motion. Revenue for the period and nine months was broadly similar to last year, yet net income for the nine months improved.
The key short term catalyst is whether Ford Motor can keep lifting earnings with that mix, even while traditional vehicle sales stay under pressure and Model e remains loss making. The biggest live risk sits around warranty and legal exposure plus trade and tariff noise, which the recent results do not remove but also do not materially worsen.
Among the recent items, the renewed quarterly dividend at US$0.15 a share is most relevant right now. It indicates that Ford Motor is still willing to return cash even while investing heavily in EV platforms, plant upgrades and software. For income focused holders, the question is how comfortably that payout sits against earnings and free cash flow.
There is another angle for anyone watching catalysts. A regular dividend helps anchor expectations around balance sheet discipline at a time when debt is not fully covered by operating cash flow and warranty or recall costs remain a swing factor. If operational execution on cost cuts and service revenue stalls, that distribution could come under more scrutiny.
Ford Motor's narrative projects US$193.8b revenue and US$15.0b earnings by 2029. That outcome assumes 1.0% yearly revenue growth and an earnings swing of roughly US$22.4b from the current loss of US$7.4b to the 2029 consensus figure.
Uncover why Ford Motor's fair value indicates a 31% potential upside to its current price and why that gap could close quickly.
Exploring Other Perspectives
Some of the lowest Ford Motor forecasts hinge on the risk that recent legal and warranty issues snowball. Before these results, the most bearish analysts were assuming revenue would trend toward about US$170.4b and earnings of roughly US$13.4b by 2029, which is far more cautious than the consensus path. You can treat this quarter’s mix of better profitability and fresh CP4 fuel pump class action progress as a live test of those harsher assumptions, and then decide which camp you lean toward after reviewing several viewpoints.
Explore 6 other Ford Motor fair value estimates, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ford Motor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ford Motor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ford Motor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ford Motor?
If this quarter has sharpened your view on Ford Motor but you want a broader watchlist, the Simply Wall St Screener can help you filter the wider market into a focused set of candidates that match your risk, income and quality preferences.
- For investors hunting resilient balance sheets and solid fundamentals, start with a curated list of solid balance sheet and fundamentals (24 results) that can help you narrow in on financially robust businesses.
- If your priority is steadier income, use the hand picked 6 dividend fortresses to spot companies where higher yields are paired with underlying business strength.
- For those who want to keep risk in check without giving up on opportunity, filter the market using a focused 32 resilient stocks with low risk scores that highlights stocks with lower risk scores and more resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com