


Realty Income has offered investors a mixed ride, with modest moves over the past year but a much stronger showing when you zoom out over several years. That uneven share price path raises a clear question for you as a holder or prospective buyer: Is the current price tag properly anchored in the real estate trust's earnings power?
- Over the past 3 years, Realty Income has delivered a total return of 37.6%, which puts real money behind the question of how firmly its earnings support the move.
- The trust's model of collecting rent from a diversified property portfolio can give investors relatively visible earnings, which may support a valuation that leans heavily on recurring income rather than one-off gains.
- Your read on Realty Income is one view; the desks covering it have another. See what analysts think Realty Income's shares could be worth.
The issue now is whether the earnings Realty Income generates today are enough to justify the share price you see on screen.
If you are comparing Realty Income with other income-focused opportunities, it can be useful to evaluate it alongside 6 dividend fortresses.
Is Realty Income Getting Expensive on Earnings?
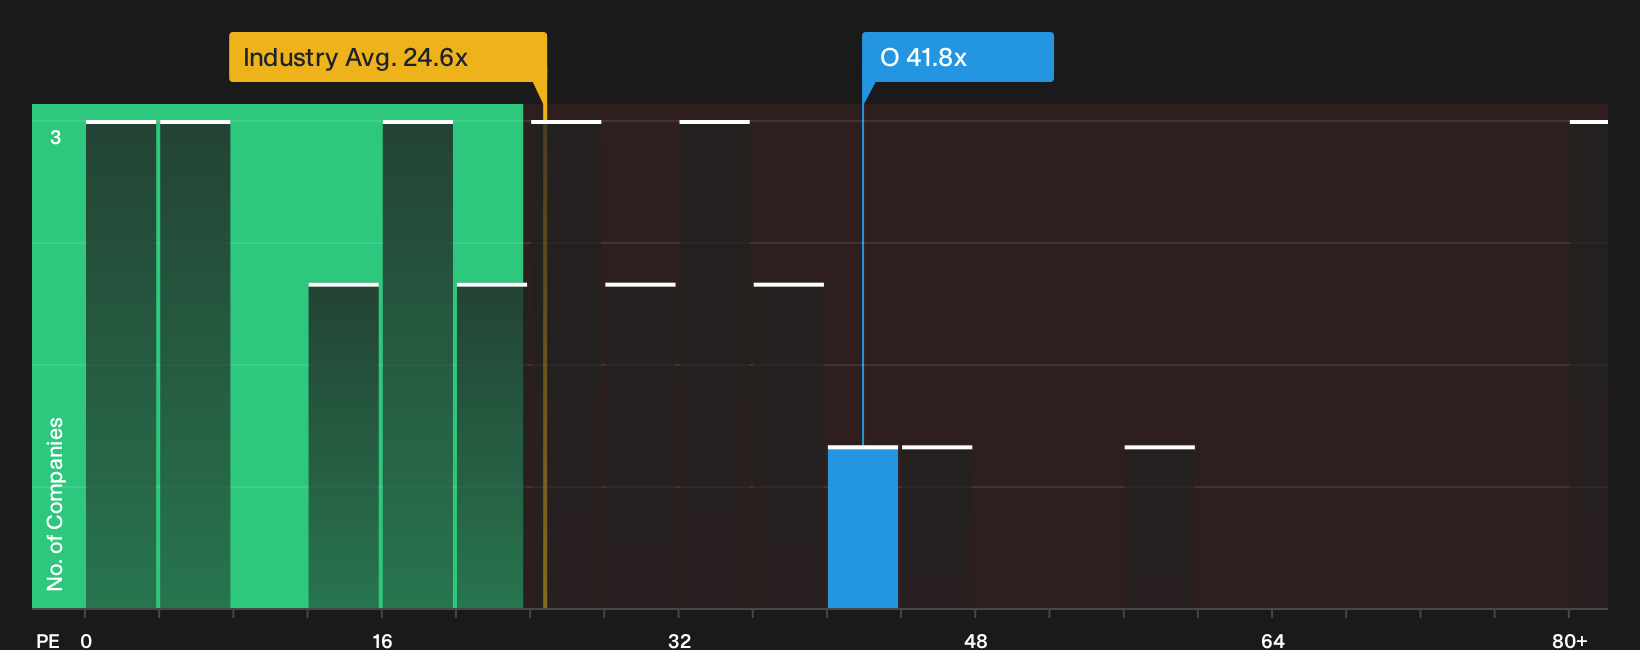
The P/E ratio suits Realty Income because many investors focus on the predictability of its rent driven earnings. On this measure, the stock changes hands at about 41.8x earnings, compared with roughly 24.6x for the wider Retail REITs sector and about 25.9x across peers. That is a sizeable premium to what investors are currently paying for similar property trusts.
The fair multiple implied by the valuation model, which blends the company’s growth profile, profitability, size and risk into a tailored benchmark, sits below the current 41.8x P/E. That gap points to Realty Income looking overvalued on this earnings yardstick, so investors would need strong conviction in the durability and quality of its future cash flows to justify paying this kind of price. Explore the numbers behind Realty Income's P/E valuation.
The Realty Income Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Realty Income leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to trade meaningfully higher or lower than it does today. Each narrative links its number to a concrete view on how Realty Income's expansion, profitability and risk profile might evolve, giving you something specific to revisit as fresh information comes through.
One of the top community narratives on Realty Income: 9% undervalued
"Given the fact that Realty Income is a dividend focused company, I will value it using only valuation methods related with dividends…"
Discover why this Narrative puts Realty Income at 9% undervalued.
One more factor to weigh before acting on Realty Income's valuation
Numbers only tell part of the story, because the people steering Realty Income and how they are rewarded can strongly influence future decisions and risk taking. See who runs Realty Income and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com