


- Alvotech reported that the FDA has approved a new Process 2.0 manufacturing method for SIMLANDI, its Humira biosimilar, which more than doubles drug substance output per batch in the DSM2 suite in Reykjavik while keeping product quality, safety and efficacy consistent with the prior process.
- The approval effectively raises SIMLANDI production capacity without expanding upstream scale. This development could reshape Alvotech’s cost structure and its ability to serve payers seeking reliable biosimilar supply.
- We will now examine how Alvotech's upgraded SIMLANDI manufacturing efficiency could influence the broader investment narrative for the business.
Alvotech Investment Narrative Recap
To own Alvotech, an investor needs to believe the company can turn its biosimilar pipeline and existing portfolio into durable cash generation despite current losses and negative equity. The recent SIMLANDI Process 2.0 approval sits squarely in that story, since manufacturing efficiency is central to competing in high price pressure markets like adalimumab.
In the near term, a key swing factor is whether commercial rollouts and milestone driven revenue can keep pace with the firm’s rising fixed costs and debt burden of about US$1.1b. The upgraded output for SIMLANDI could support volume availability, but it does not remove risks around pricing pressure, regulatory timing or partner execution.
The SIMLANDI process news aligns closely with the broader theme of Alvotech investing in its manufacturing footprint and vertical integration. Earlier moves such as the Xbrane R&D and Ivers Lee acquisitions increased the fixed cost base, yet were aimed at tighter control over production and development for a growing biosimilar lineup.
As that spending flows through, investors are watching whether operational efficiencies arrive fast enough to support a potential shift from losses of US$179.6m. Higher throughput on a major product like SIMLANDI can support that goal if pricing holds and commercialization partners convert capacity into consistent shipment volumes.
Alvotech's current narrative anchors on analysts projecting revenues of US$976.3 million and earnings of US$223.1 million by 2029. This reflects forecast revenue growth of 25.4% per year and an earnings swing of roughly US$402.7 million from a loss of US$179.6 million today into positive territory.
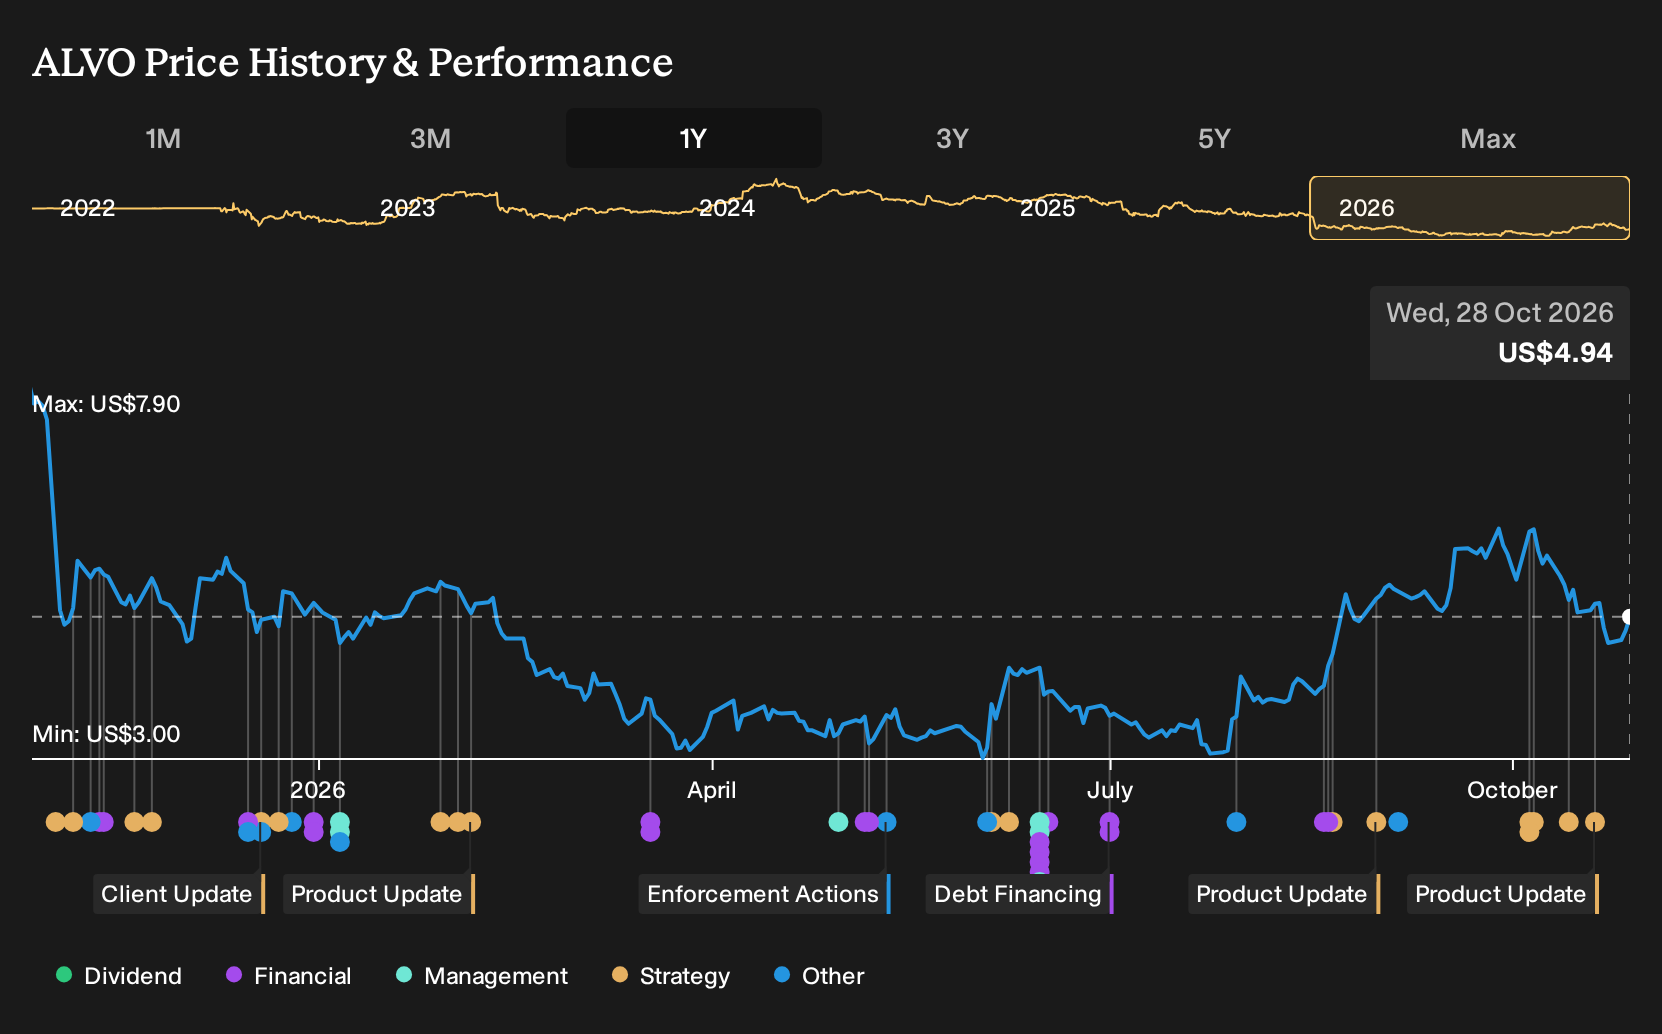
Uncover why Alvotech's fair value indicates a 38% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One alternative view focuses on Alvotech’s heavy funding needs rather than capacity gains. In that bearish script, rising interest costs and an H1 2026 net loss of about US$65.8 million make the story far more fragile, with some analysts only penciling in around US$790.5 million of 2029 revenue and US$141.1 million of earnings. Those estimates came before this SIMLANDI process approval. You may want to compare both narratives and decide which assumptions feel more realistic to you.
Explore 4 other Alvotech fair value estimates, including one that suggests as much as 19% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Alvotech research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alvotech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alvotech's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alvotech?
If the Alvotech story has you thinking about where manufacturing strength, balance sheets and future cash generation intersect, it can help to line it up against other candidates using the Simply Wall St Screener. You can filter for the traits you care about, then pressure test whether Alvotech still earns a place in your watchlist once you have a broader set of options on the table.
- For investors hunting for strong businesses that the market may be overlooking, start with a curated 19 high quality undiscovered gems that combine quality fundamentals with genuine upside potential.
- If capital preservation and steadier profiles matter more to you than rapid expansion, narrow your search to companies in the 32 resilient stocks with low risk scores that score well on resilience and financial risk metrics.
- When you want a tighter focus on balance sheet strength and underlying business quality, use the list of solid balance sheet and fundamentals (24 results) to surface companies with robust finances that can better absorb setbacks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com