


- Cigna Group (NYSE:CI) CEO Brian Evanko introduced a new enterprise vision called "Lead to One" on 26 October 2026.
- The plan centers on large scale personalization of healthcare and deeper integration across Cigna's medical, pharmacy, and behavioral offerings.
- Management highlighted an expanded focus on specialty pharmacy and integrated care solutions aimed at simplifying patient experiences and plan design.
- The "Lead to One" vision reframes how Cigna approaches personalization and integrated care, which is only part of today's story. We have also spotted 1 warning sign worth knowing about at Cigna Group.
For readers looking to explore more ideas in this corner of healthcare, the next place to go is our screener containing 19 high quality undiscovered gems.
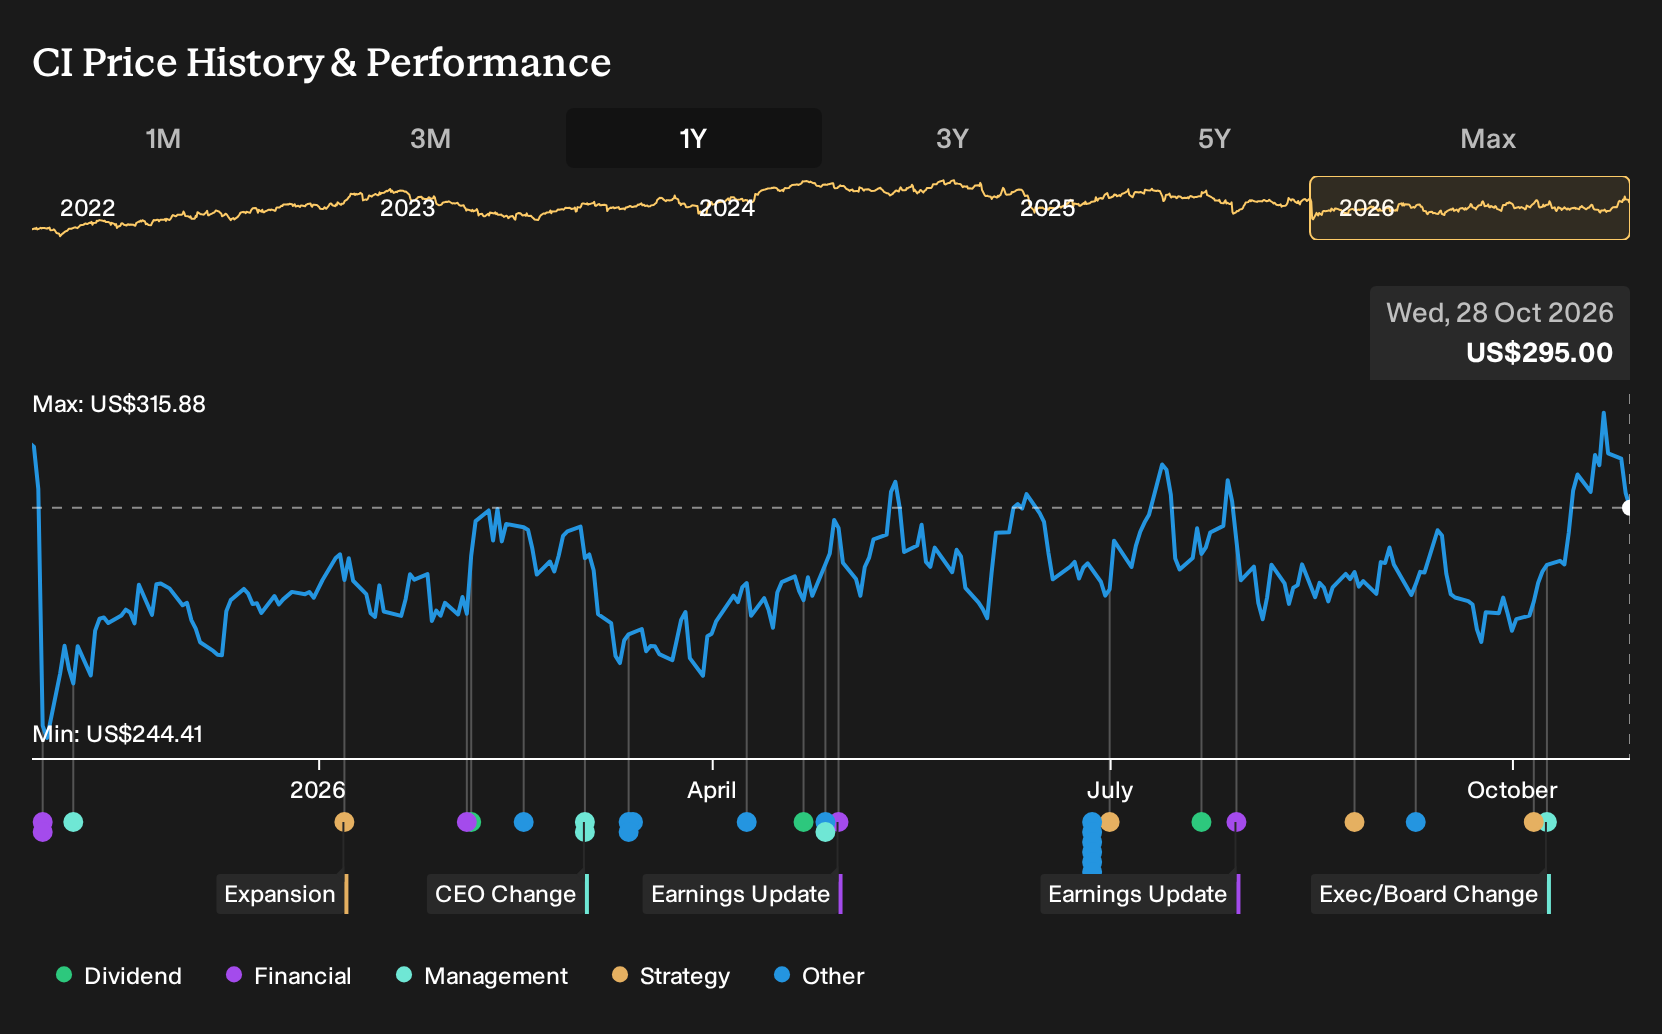
Cigna Group operates a broad US health insurance and services platform. This new vision builds on a business that already connects medical coverage with related pharmacy and benefits offerings for employers, individuals, and government-backed plans.
What does the 'Lead to One' vision actually change for Cigna Group day to day?
The new vision pushes Cigna Group to treat its medical, pharmacy, and behavioral offerings as a single connected experience rather than separate product lines. That points to more shared data, tighter care coordination, and plan designs that try to reduce friction for employers and members across Evernorth and Cigna Healthcare.
Does this shift alter the existing Cigna Group Narrative?
The Narrative already leans on Specialty and Care Services, AI tools, and the Signature rebate free PBM model to support earnings quality. Lead to One lines up with that story because it leans on data driven care programs and integrated pharmacy services. It also keeps attention on PBM margin pressure and high medical cost trends as key risks.
See how these catalysts shape Cigna Group's path to a $339 fair value.
What should investors watch next to see if 'Lead to One' is taking hold?
The clearest early markers will be 2027 Evernorth contract implementations, customer retention around the mid 90s target, and updates on Signature PBM adoption. Investors can also track how management describes medical cost trends and Specialty and Care Services earnings on upcoming quarterly calls through 2027 to see if integration is showing through in the numbers.
The Cigna Group signal hiding in plain view on your screen
There is a quiet estimate of what Cigna Group could be worth based only on the cash it produces, and it can be lined up directly against today's share price. Find out exactly what Cigna Group is worth today based on its cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com