


Traeger, Inc. (NYSE:COOK) is possibly approaching a major achievement in its business, so we would like to shine some light on the company. Traeger, Inc., together with its subsidiaries, designs, sources, sells, and supports wood pellet fueled barbecue grills and flatrock flat top grills for retailers, distributors, and direct to consumers in the United States and internationally. The US$133m market-cap company’s loss lessened since it announced a US$115m loss in the full financial year, compared to the latest trailing-twelve-month loss of US$113m, as it approaches breakeven. The most pressing concern for investors is Traeger's path to profitability – when will it breakeven? We've put together a brief outline of industry analyst expectations for the company, its year of breakeven and its implied growth rate.
Traeger is bordering on breakeven, according to the 7 American Consumer Durables analysts. They expect the company to post a final loss in 2027, before turning a profit of US$12m in 2028. So, the company is predicted to breakeven approximately 2 years from now. How fast will the company have to grow each year in order to reach the breakeven point by 2028? Working backwards from analyst estimates, it turns out that they expect the company to grow 71% year-on-year, on average, which is extremely buoyant. If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
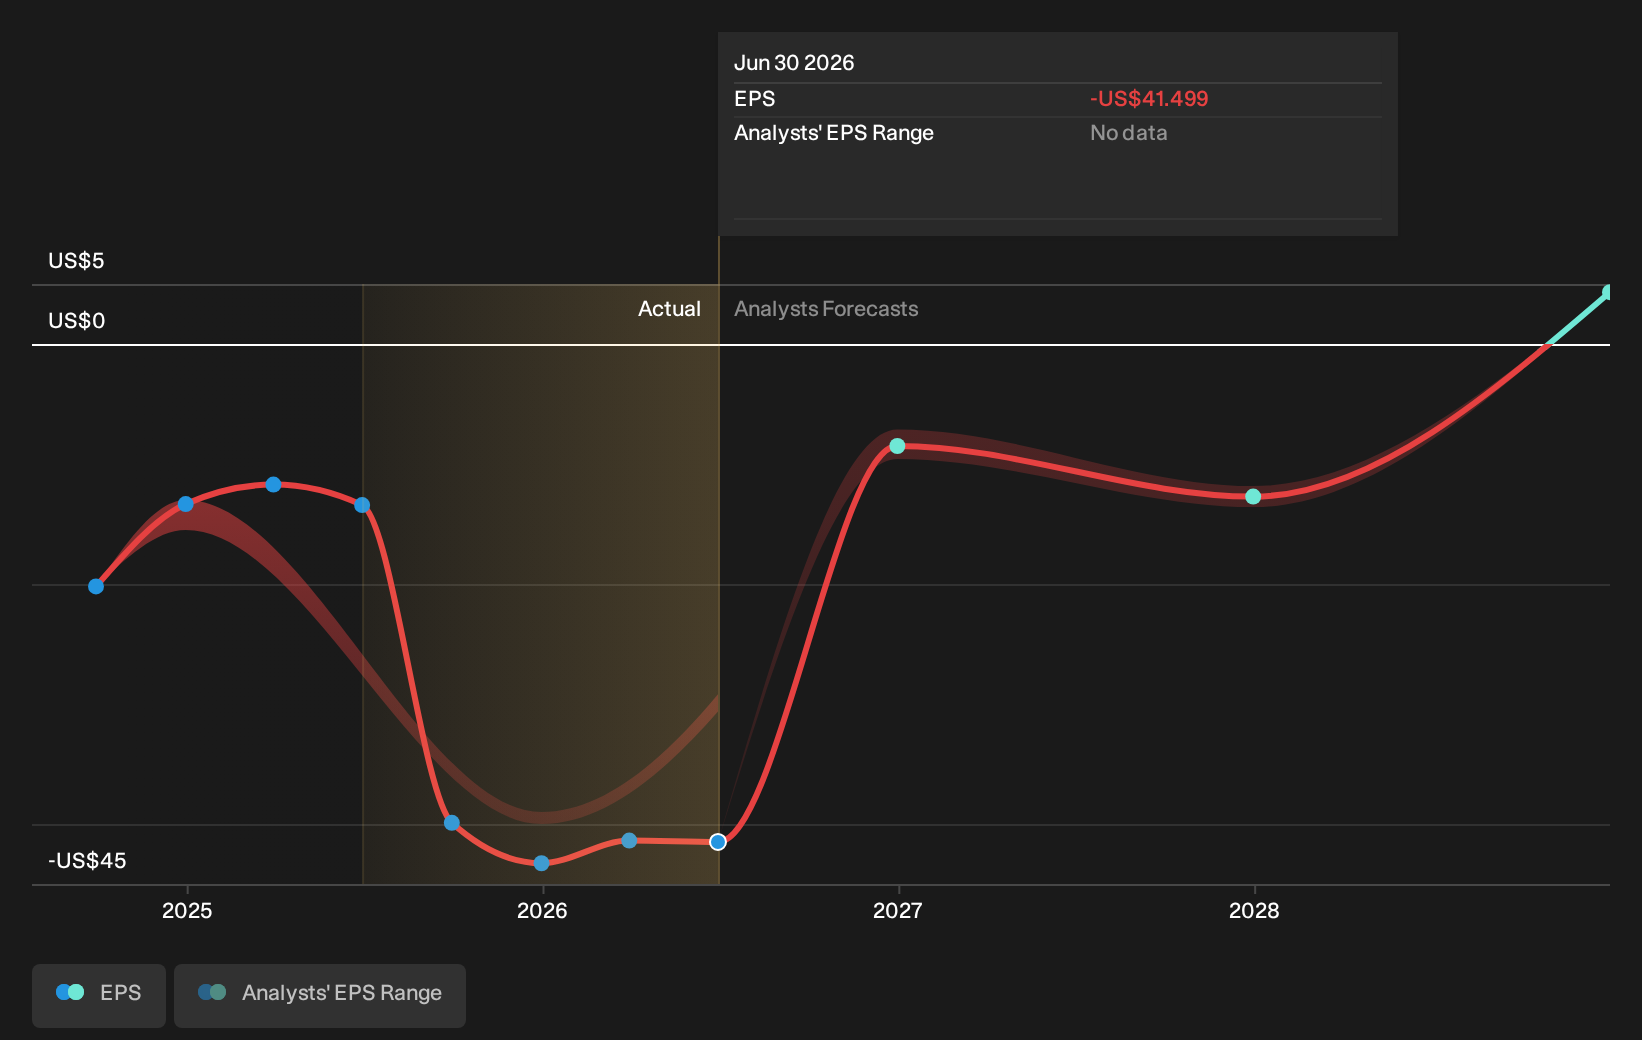
Given this is a high-level overview, we won’t go into details of Traeger's upcoming projects, however, bear in mind that generally a high forecast growth rate is not unusual for a company that is currently undergoing an investment period.
View our latest analysis for Traeger
One thing we would like to bring into light with Traeger is its debt-to-equity ratio of over 2x. Typically, debt shouldn’t exceed 40% of your equity, which in this case, the company has significantly overshot. Note that a higher debt obligation increases the risk in investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on Traeger, so if you are interested in understanding the company at a deeper level, take a look at Traeger's company page on Simply Wall St. We've also put together a list of important factors you should further research:
- Valuation: What is Traeger worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether Traeger is currently mispriced by the market.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Traeger’s board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.