


PBF Energy has delivered a very strong multi year share price run, which puts a spotlight on whether the current valuation is still grounded in what the refinery operator actually earns. With the stock now pulling back in recent weeks, the key issue is whether the recent price still lines up with the earnings power behind it.
- Over the past 5 years the share price has risen by roughly 4.8x. This puts a lot of weight on the question of how durable and repeatable PBF Energy's earnings have been.
- Recent lobbying around a potential hydrofluoric acid ban and the roughly US$350 million acquisition of hydrogen plants may reshape long term operating costs and therefore the earnings base that supports the current market value.
- Your read on PBF Energy is one view; the desks covering it have another. See what analysts think PBF Energy's shares could be worth.
The stock's next move may depend on whether PBF Energy's current price can be justified by its recent earnings when set against the Fair Ratio benchmark.
For context on how PBF Energy's earnings-based story compares with other opportunities, it can help to line it up against 26 high quality undervalued stocks.
Does PBF Energy Look Undervalued on Earnings?
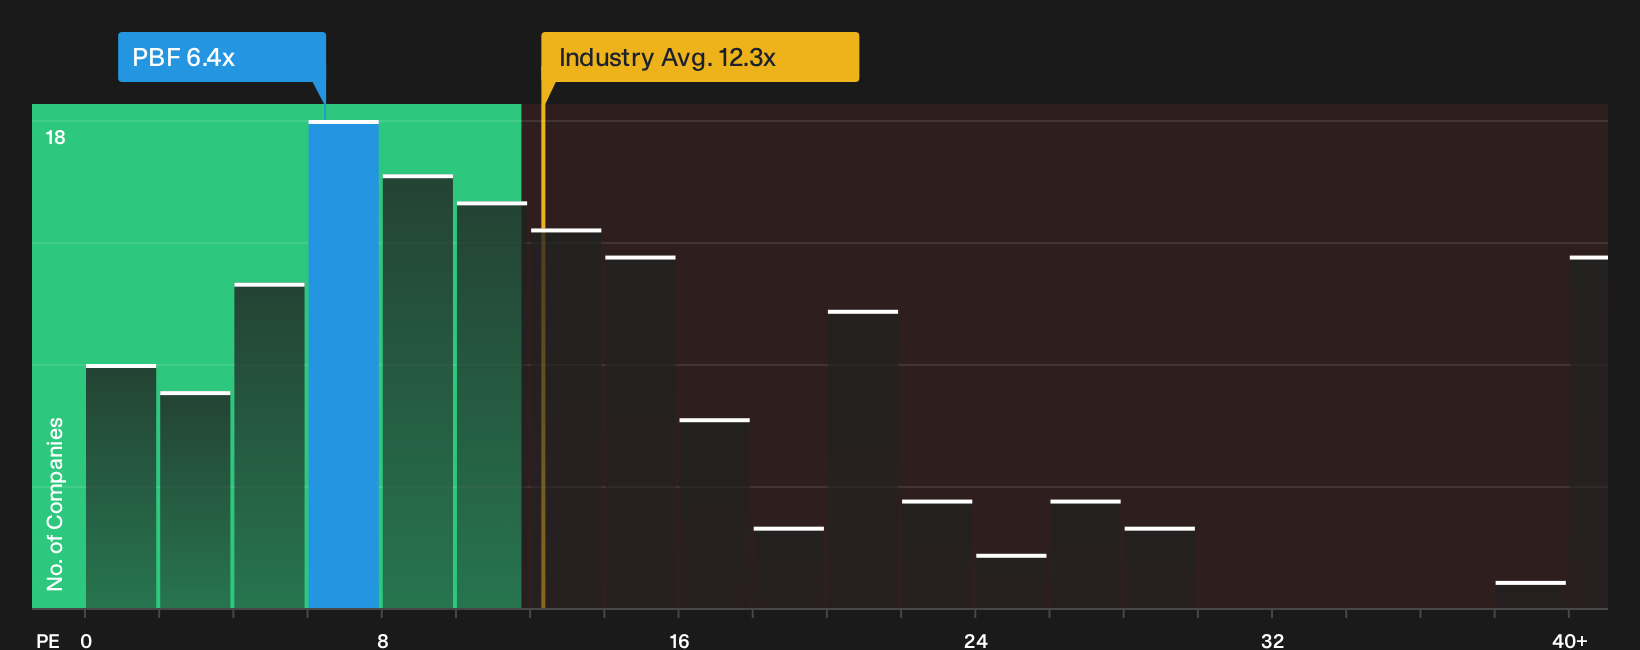
A P/E ratio suits PBF Energy because earnings are a central yardstick for a refinery operator that already generates free cash flow. On that measure, the stock trades on roughly 6.4x earnings, which is well below the Oil and Gas industry average of about 12.3x and far under the wider peer group near 30.9x. That marks a sizeable discount to where many other refinery linked businesses and broad market peers trade.
The Fair Ratio, which reflects what you might expect for PBF Energy once its margins, scale and risk profile are accounted for, sits above the current multiple, so the shares screen undervalued on this framework. Despite recent attention on hydrogen plant acquisitions and potential hydrofluoric acid regulation, the market is still pricing the company at a P/E that is low relative to both the sector and this tailored benchmark. This leaves room for investors to question whether that gap is justified by future earnings risk or has become too wide. Explore the numbers behind PBF Energy's P/E valuation.
The PBF Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for PBF Energy pick up where the P/E discussion leaves off and explain which combinations of future growth, profitability and earnings stability would need to hold for the shares to be worth materially more or materially less than the current price. Instead of a single valuation output, these scenarios describe the future that number depends on, so you can track over time whether PBF Energy's actual progress matches the assumptions.
Community views on PBF Energy are split between those who see tight fuel markets and cost cuts as support for more upside and those who focus on compliance costs and earnings volatility.
Bull case: 8% undervalued
"Company wide cost reduction under the Refining Business Improvement program has already delivered US$230 million of annualized savings and targets more than US$350 million by year end 2026…"
Discover why this Narrative puts PBF Energy at 8% undervalued.
Bear case: 32% overvalued
"Bearish analysts expect PBF Energy's core refining operations to remain exposed to higher regulatory and renewable fuel compliance costs that continue to pressure profitability…"
Explore why this Narrative puts PBF Energy at 32% overvalued.
One more piece of the PBF Energy puzzle worth checking
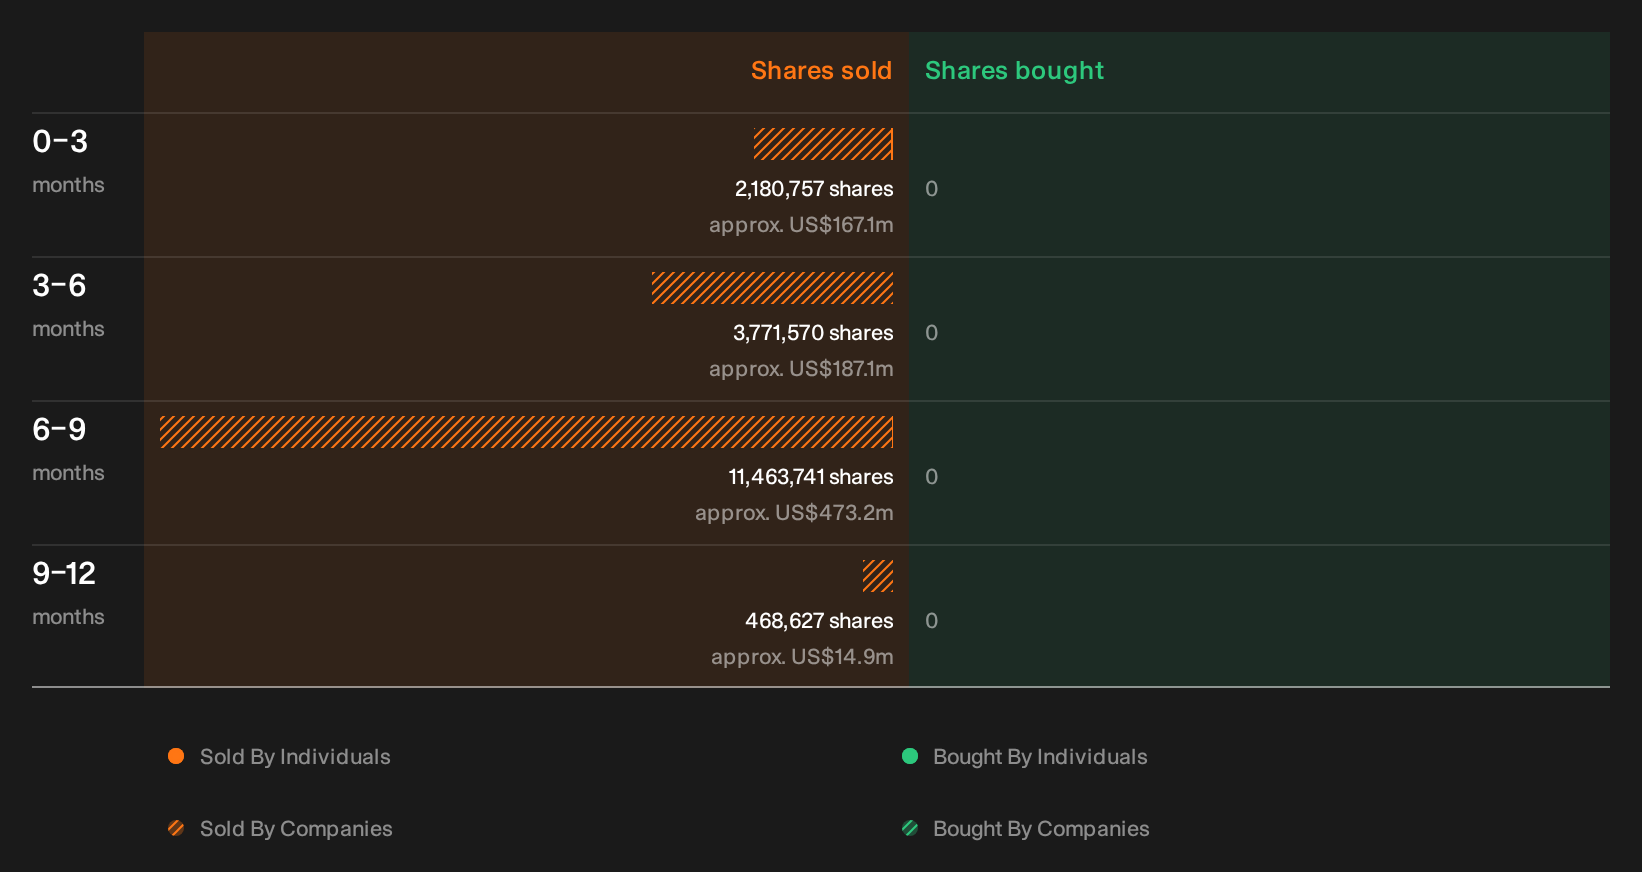
Before closing the book on PBF Energy, there is one quieter signal that deserves a closer look: the recent share dealings by those inside the business. See the recent insider selling flagged for PBF Energy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com