


Datadog (DDOG) heads into its Q3 2026 earnings release on November 4 with expectations focused on year-over-year EPS growth and fresh attention on its role in observability and AI monitoring.
The share price tells a story of strong momentum into this earnings date. Datadog’s 1-year total shareholder return of 78.47% and 3-year total shareholder return of 247.58% sit behind a year to date share price return of 108.13%. This suggests enthusiasm has been building around its observability and AI monitoring exposure, while investors watch closely for how the Upwind acquisition plan and rising AI related demand are affecting the risk and opportunity profile.
Spot opportunities riding the same AI and observability wave as Datadog by scanning our hand-picked list of 54 AI infrastructure stocks.Datadog now trades only modestly below the average analyst target and above some intrinsic value estimates. After a 108% year to date move, the question is where a reasonable fair value range actually lands.
Most Popular Narrative: 5% Undervalued
At a last close of $278.41 against a widely followed fair value marker of about $292, the Datadog story leans toward modest undervaluation while investors weigh how durable its AI observability advantage can be under a premium price tag.
Expanding AI workloads, with over 750 AI customers including all 10 of the top AI leaders and growing use cases such as GPU monitoring, Agent Observability, AI Guard and Bits AI, can support higher observability and security spend per customer and feed Datadog revenue growth over time.
See why 175 investors see Datadog as 5% undervalued.
Result: Fair Value of $292 (UNDERVALUED)
Still, concentration in very large customers and ongoing insider selling activity could pressure the Datadog story if usage or sentiment cools from this point.
Find out about the key risks to this Datadog narrative.
Another View: Datadog’s Rich Sales Multiple
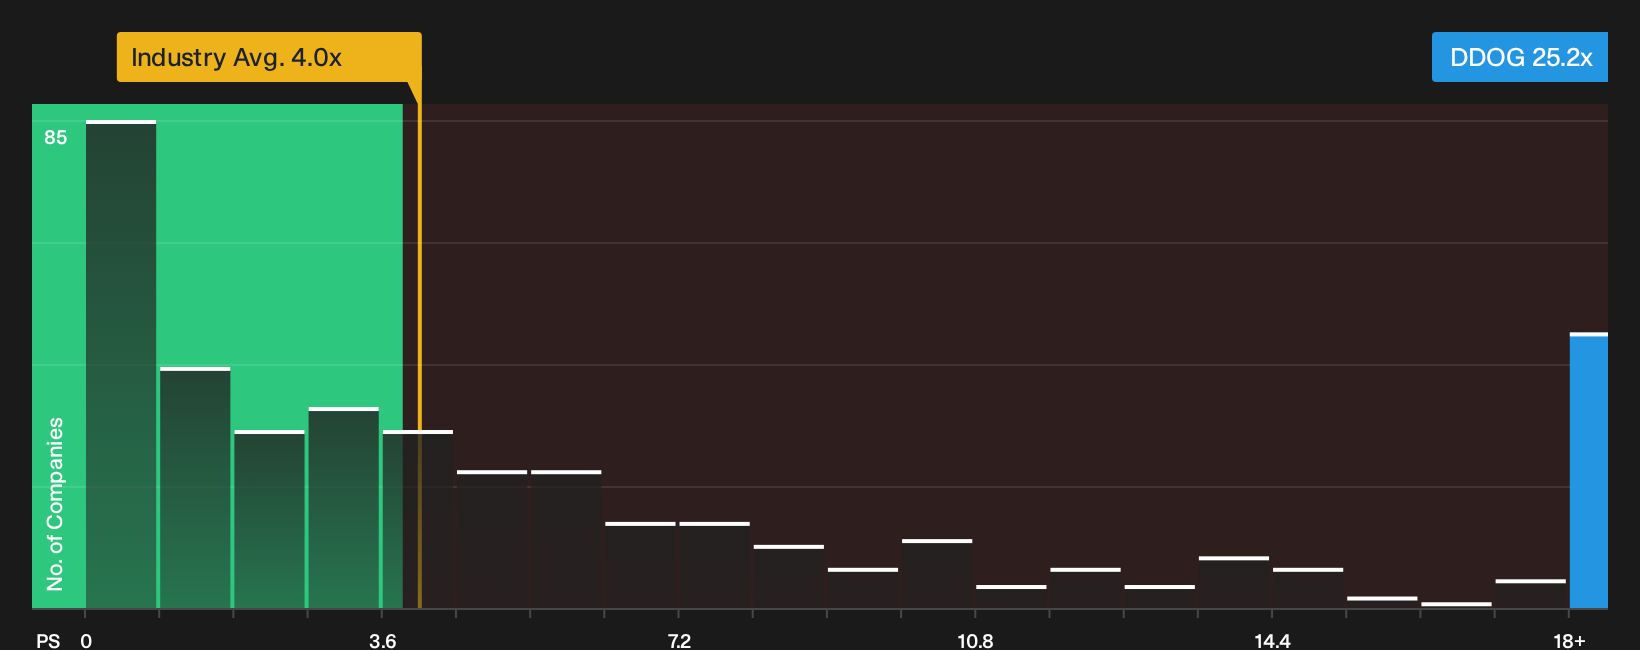
The first take leans on fair value and DCF style thinking. A different lens uses Datadog’s P/S ratio of 25.2x against the US Software industry at 4x, peers at 8.3x, and a fair ratio of 15.5x. That premium signals meaningfully higher valuation risk if sentiment cools.
To stress test that gap against the underlying numbers and see what the market could move toward over time, it helps to walk through a full valuation breakdown like See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Datadog’s valuation and sentiment can be confusing, so consider reviewing the underlying metrics yourself, then weigh the 3 key rewards and 1 important warning sign.
Ready for more Datadog-style ideas?
If you stop at Datadog, you risk missing other opportunities. Use the Simply Wall St Screener to quickly surface fresh, high conviction ideas across the market.
- Target steady compounding by scanning a curated 32 resilient stocks with low risk scores that aims to prioritize resilience when conditions get choppy.
- Hunt for potential bargains by running a focused search on a 19 high quality undiscovered gems that many investors may not be watching yet.
- Strengthen your downside protection by filtering for a list of solid balance sheet and fundamentals (24 results) so you can concentrate on businesses with healthier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com