


Laureate Education has delivered very strong multi‑year gains, and that rise puts fresh focus on whether the current share price lines up with what its earnings can reasonably support. With the stock now well above where it traded several years ago, investors are asking if the underlying profit engine justifies paying today’s multiple.
- Over the past 5 years the stock has climbed about 3.6x, which puts real pressure on the valuation case to be grounded in the business’s earnings power rather than just share price momentum.
- The group’s education services model, with its emphasis on enrollment levels and cost control, can shape how much of each revenue dollar ultimately turns into sustainable profit available to support the current market value.
- The analysts covering Laureate Education have run their own numbers. See what analysts think Laureate Education's shares could be worth.
The stock’s next move may depend on whether Laureate Education’s current earnings profile is strong enough to support the price investors are being asked to pay today.
If you want a broader earnings check alongside Laureate Education, consider using a focused stock screen of 26 high quality undervalued stocks.
Is Laureate Education a Bargain on Earnings?
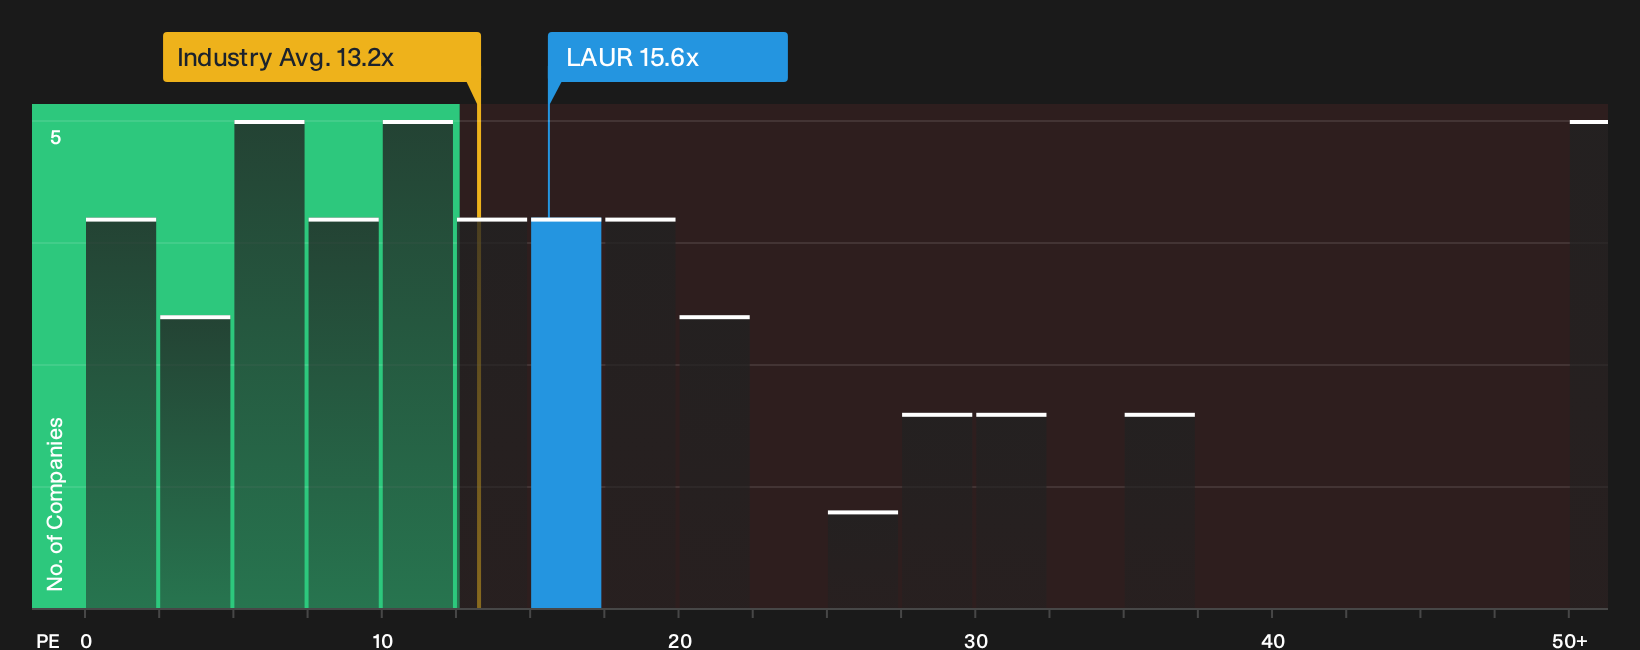
The P/E ratio is a useful fit for Laureate Education because investors often anchor education stocks to how many dollars of profit they pay for each dollar of earnings. Laureate trades on roughly 15.6x earnings, which is very close to both the Consumer Services industry average of about 13.2x and the peer group on roughly 15.6x, so the headline multiple alone does not paint it as either an outlier bargain or an obvious outlier on the expensive side.
The tailored fair P/E that blends Laureate Education’s growth profile, margins, size and risk points to a somewhat higher ratio than where the shares trade today. That leaves the current P/E sitting below what this framework would expect, which signals the stock screens as undervalued on earnings compared with that custom benchmark. Readers still need to weigh the quality and durability of those earnings, because any change in profitability would quickly alter how attractive this P/E really looks. Explore the numbers behind Laureate Education's P/E valuation.
The Laureate Education Narrative: What Would Justify Today's Price?
Narratives pick up where the Laureate Education valuation puzzle leaves off. They spell out which paths for growth, margins and earnings would need to hold for the stock to look meaningfully cheaper or richer than today’s quote. Rather than leaning on a single P/E or model output, each one lays out the assumptions behind its fair value so you can compare those expectations with the results as they are reported.
One of the top community narratives on Laureate Education: 12% undervalued
"The main thing that has to go right is that Laureate Education continues to scale high margin online offerings, execute its multiyear campus buildout, and embed AI tools across marketing and student delivery..."
Discover why this Narrative puts Laureate Education at 12% undervalued.
One more Laureate Education check that sits beyond the share price
Figures only tell part of the story for Laureate Education, because the people steering the business and the way their pay is structured can heavily shape future choices and risk, and that separate check still waits for you. See who runs Laureate Education and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com