


Brookfield has delivered a 94.5% gain over the past three years, yet the recent share price slide in 2026 puts the focus squarely on what investors are paying for its earnings today. With the latest move in distributable earnings and active share buybacks now in the mix, the question is how well the current valuation lines up with the underlying profit engine.
- Brookfield's share price has climbed 94.5% over three years, which raises the stakes on whether that run is adequately supported by the earnings the business is generating.
- A 15% rise in distributable earnings per share, helped by contributions from asset management, insurance, infrastructure, renewables and real estate, may support the case for a higher earnings base and different expectations around what the company can earn on its capital.
- The analysts covering Brookfield have run their own numbers. See what analysts think Brookfield's shares could be worth.
The issue now is whether Brookfield's current share price is justified by its earnings when set against the broader industry average.
If you are weighing Brookfield's earnings against its current share price, it can help to see how other companies trade on similar questions of value through 4 high quality undervalued stocks.
Is Brookfield Getting Expensive on Earnings?
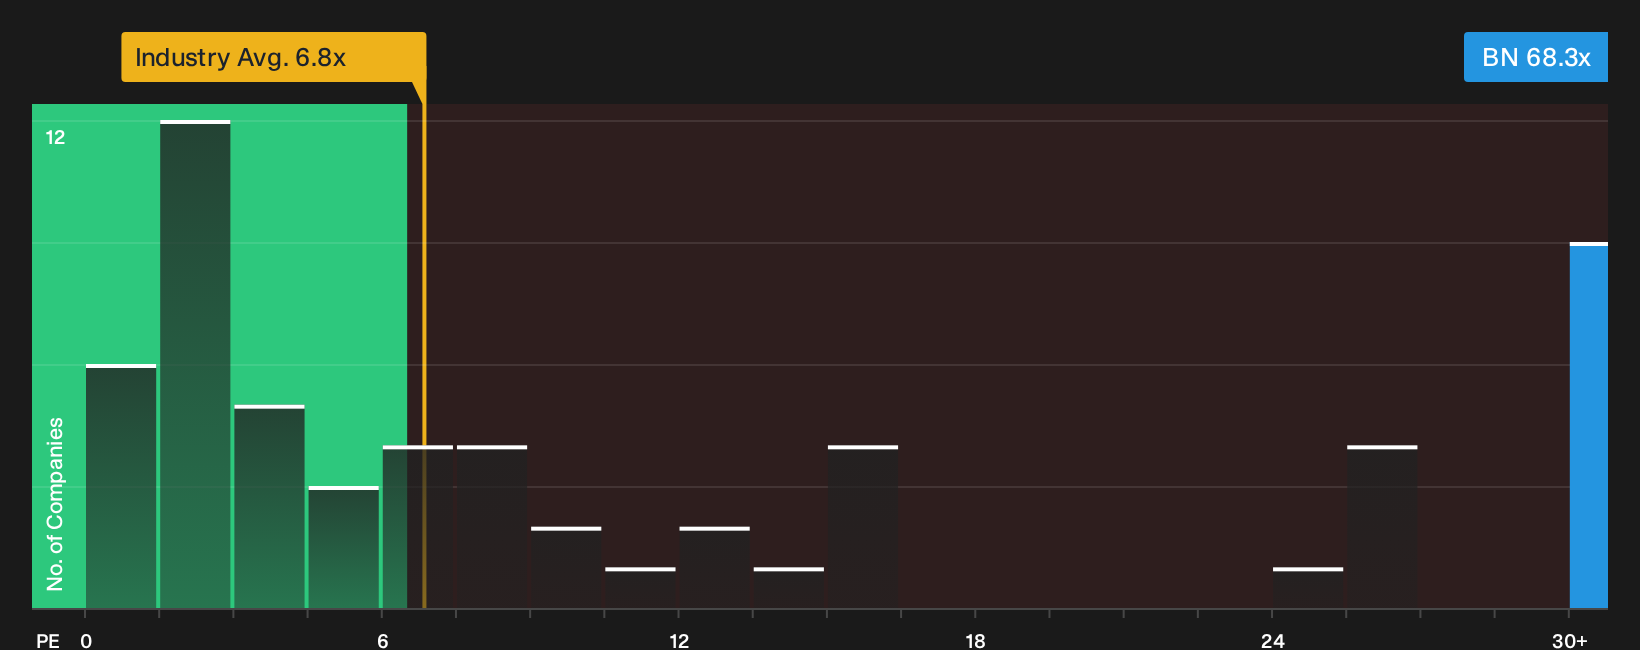
P/E suits Brookfield because earnings are the main yardstick investors watch across capital markets groups. On this measure, the stock changes hands at about 68.3x trailing earnings. That is far above the broader capital markets industry average of roughly 6.8x and also well ahead of the peer group near 16.8x, so the shares currently trade at a steep premium to both sets of comparables and screen as overvalued on this metric.
Because distributable earnings per share recently rose 15% and management has been buying back stock, some investors may feel more comfortable with a richer tag on Brookfield than on a more plain vanilla manager or broker. The model used here still treats the gap between the 68.3x P/E and the sector as extreme. This signals that the framework is heavily penalising the risk profile and earnings quality and is best read as a warning that the shares price in a lot of good news already. Explore the numbers behind Brookfield's P/E valuation.
The Brookfield Narrative: What Would Justify Today's Price?
Brookfield's valuation puzzle only really comes into focus once you spell out the stories that could sit behind its current P/E, which is what Simply Wall St Narratives aim to do on the Community page. Each scenario pins its number to a specific view on how Brookfield's growth, profitability and risk profile might evolve, giving you a concrete thesis you can test again as fresh figures and updates come through.
One of the top community narratives on Brookfield: 34% undervalued
"The return comes from compounding earnings; any narrowing of the discount is the accelerant, not the engine..."
Discover why this Narrative puts Brookfield at 34% undervalued.
One more Brookfield question before you move on
Before you lean too hard on today's P/E story for Brookfield, it can help to see where professional forecasts expect the business to be a few years from now. Explore where analysts expect Brookfield to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com