


Interest rates are frozen, but the debate inside the Fed is heating up. With the benchmark stuck at 3.75–4.0% and futures pointing to a higher chance of more tightening by year end, rate sensitive financials could see meaningful shifts in earnings power and investor attention. This piece walks through 3 US banks and brokers that appear especially exposed to this latest policy twist.
The three rate sensitive financials highlighted below are only a starting sample, since the wider screen surfaced 37 more US banks, brokerages and cash managers with equally compelling rate stories that are not covered here.
If you want to go beyond these examples, head straight into the US Rate-Sensitive Financials (Banks, Brokerages & Cash Managers) screener to identify, filter and analyze the setups that best match your own conviction.
Esquire Financial Holdings (ESQ)
Overview: Esquire Financial Holdings is a U.S. commercial bank focused on legal and small business clients, offering tailored lending, deposits, payment processing and cash management solutions that are closely tied to short term interest rate moves.
Operations: Esquire Financial Holdings generates about US$149 million in Community Banking revenue, all from customers in the United States.
Market Cap: US$1.53b
Esquire Financial Holdings sits squarely in the rate sensitive banking camp, with a niche legal finance model that can translate policy moves by the Fed directly into changes in net interest income and fee potential for specialized clients.
"The growth of contingent fee law practices and complex litigation is supporting wider use of specialized financing, which Esquire is already serving through a US$1.22b litigation loan book at about a 9% yield."
This raises a key question: what happens if a single assumption about future case volumes and client appetite for that funding line shifts at the same time as policy rates?
That pivot risk is exactly what sits at the center of the full narrative for Esquire Financial Holdings, where you see how Esquire Financial Holdings could either accelerate or stall.

Arrow Financial (AROW)
Overview: Arrow Financial is a regional U.S. bank holding company that provides commercial and consumer lending, deposits, wealth services and insurance. Earnings are sensitive to short term interest rates.
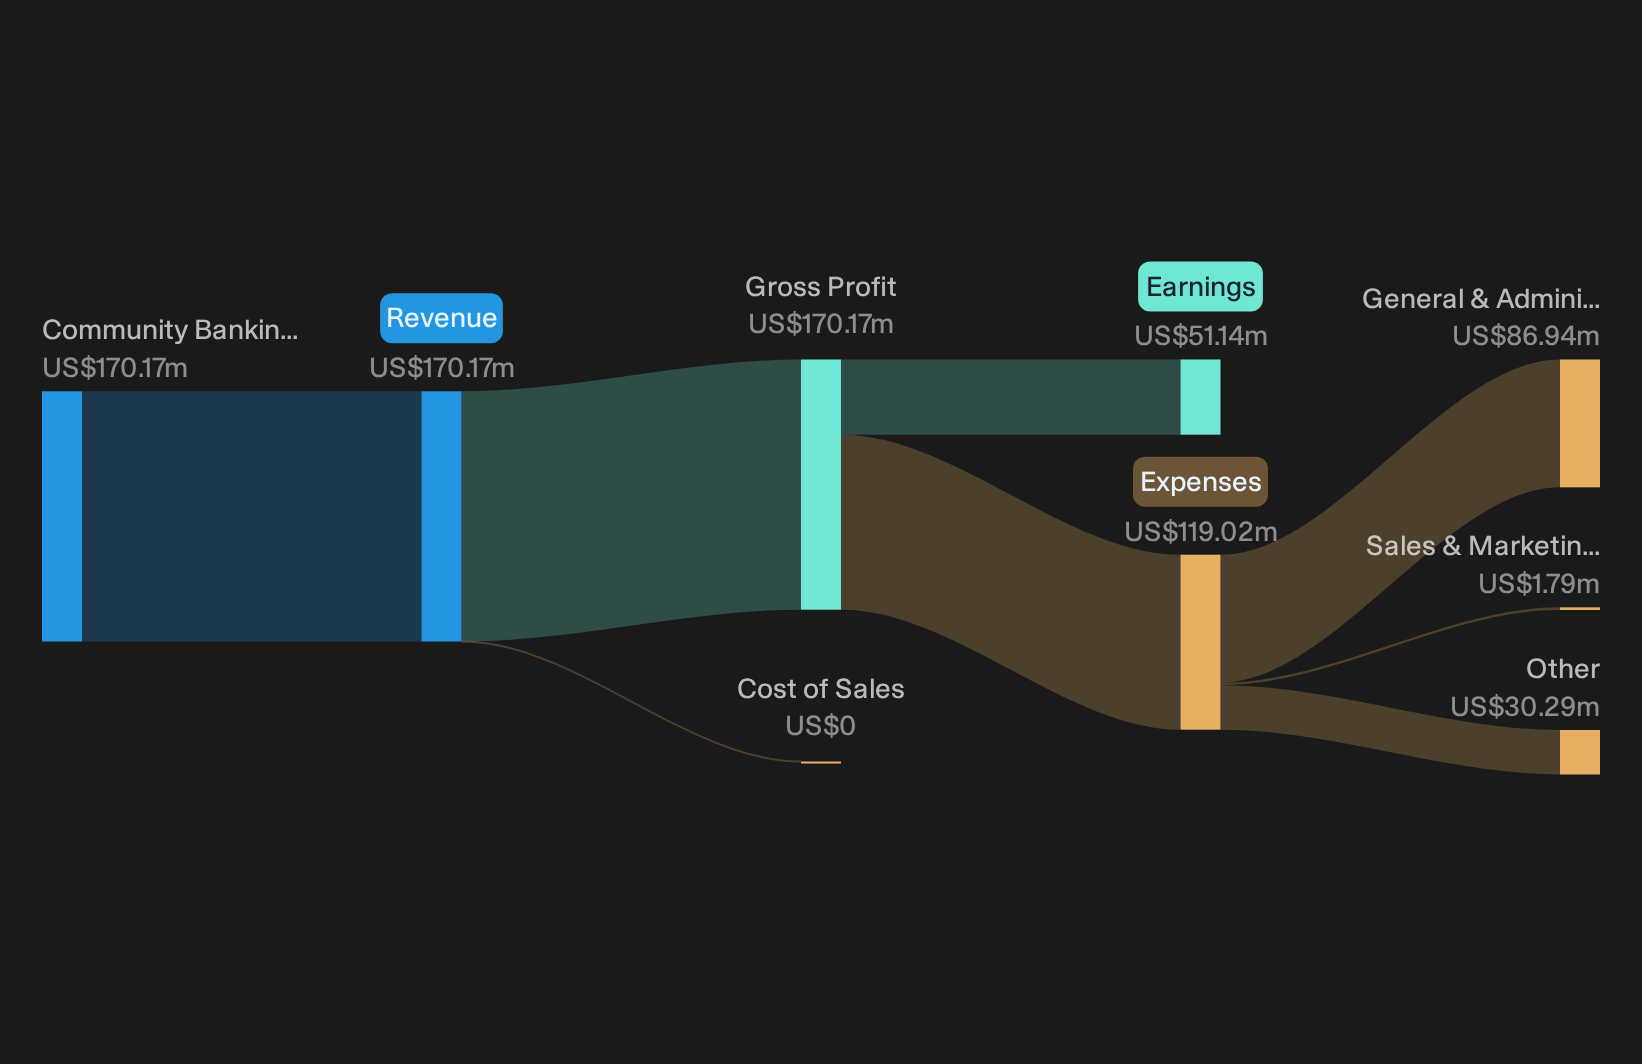
Operations: Arrow Financial generates about US$170 million in Community Banking revenue, all from customers in the United States. This ties performance closely to domestic rate policy.
Market Cap: US$712 million
Arrow Financial fits this rate-sensitive screen because virtually all of its income comes from traditional banking, where net interest margin is a key factor as the Federal Reserve considers a higher-for-longer stance. Earnings, dividend income and valuation all depend on how that spread behaves if a single unseen funding pressure shifts at the wrong moment.
That unseen pressure is exactly what the analysis report for Arrow Financial could be quantifying for Arrow Financial, before funding costs start decoupling from headline rate moves.
Northrim BanCorp (NRIM)
Overview: Northrim BanCorp is an Anchorage based commercial bank that earns money from loans, deposits and financial services tied to US interest rates.
Operations: Northrim BanCorp generates about US$145 million from Community Banking, US$43 million from Home Mortgage Lending and US$36 million from Specialty Finance, all in the United States.
Market Cap: US$534 million
Northrim BanCorp sits firmly in the rate sensitive bucket, with commercial lending, mortgages and specialty finance all relying on the gap between loan yields and what it pays on deposits. A P/E below larger US banks provides exposure to interest rate dynamics at a lower entry multiple, although a single funding pressure could still affect those spreads at an inopportune time.
Those funding pressures are exactly where the real story could start to shift for Northrim BanCorp, so pull up the 4 key rewards and 2 important warning signs and see what the market might be missing.

Seeking Alternatives Before The Crowd?
Fresh opportunities do not wait. Breakout trends build momentum, weak ideas start dropping and quiet winners stay under the radar for now. Spot the shift while it matters and act now.
- Track cash rich operators that can keep compounding through cycles by running the list of solid balance sheet and fundamentals (24 results) before those balance sheets get fully priced in.
- Identify potential momentum where income meets resilience by scanning the 6 dividend fortresses while yields and payout strength are still flying under wider attention.
- Focus on early growth stories in one place by checking the 19 high quality undiscovered gems while these businesses remain off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com