


- Aerie, the intimates and activewear brand within American Eagle Outfitters, was hit with a court ordered preliminary injunction in China that bars sales of its "Overslept" sleepwear line after a finding of trademark infringement and bad faith adoption of the mark.
- The ruling arrives ahead of the peak holiday period and highlights a real operational risk for American Eagle Outfitters, as a legal dispute in a single product line can disrupt inventory plans, channel relationships and demand forecasting for a division that is focused on growth.
- We will now look at how this Chinese injunction on Aerie sleepwear could influence American Eagle Outfitters' broader investment narrative.
Scan how traders are pricing this legal setback for American Eagle Outfitters against peers by reviewing 32 resilient stocks with low risk scores, which have steadier business and risk profiles.
American Eagle Outfitters Investment Narrative Recap
For an investor to stay with American Eagle Outfitters, the core belief is that Aerie, OFFLINE and the ongoing reset in American Eagle womens bottoms can support a healthier mix of growth and margins over time. The China injunction sits against that story as an operational headache rather than a thesis breaker, unless it broadens beyond the Overslept sleepwear line.
The near term catalyst remains execution on merchandising and markdown control as inventory at cost has been running ahead of unit growth, which can pressure cash and profits. The biggest risk is that clearance heavy behavior lingers at the American Eagle brand while Aerie expansion is temporarily disrupted in pockets like China.
The trademark injunction in China directly intersects with Aerie, which analysts previously framed as a key growth engine with trailing 12 month revenue above US$2b and comparable sales in the high teens to mid 20s. That earlier context sets up the current issue as a test of how resilient Aerie’s momentum is when a single product line faces legal constraints in an important market.
For you as a shareholder, the link to catalysts is clear. Aerie and OFFLINE are intended to carry a larger share of American Eagle Outfitters growth while the core brand works through womens bottoms and margin cleanup. Any operational friction around Aerie, even if limited to one sleepwear label, adds another execution factor to watch around inventory, marketing focus and international expansion pacing.
What The Aerie Injunction Means For American Eagle Outfitters' Forecasts
The trademark setback around Aerie sleepwear in China lands against a backdrop where analysts already have a defined path sketched out for American Eagle Outfitters. Those forecasts assume steady but not explosive progress rather than a dramatic reset in either direction. That context matters, because any disruption to Aerie, even in a single category like sleepwear, now gets judged against a relatively modest growth script rather than a blue sky scenario.
On the top line, the current consensus builds in revenue growth of 3.6% a year for the next three years. For a retailer leaning on Aerie and OFFLINE to do more of the heavy lifting, that kind of mid single digit pace implies a gradual build in demand instead of a sprint. Pressure points like a product specific injunction in China can still matter, since even small execution stumbles can make a 3.6% annual climb feel tight when merchandising resets and inventory cleanup are already in play.
Analysts expect earnings to rise from US$336.9m today to US$381.6m by 2029, which is an increase of roughly US$44.7m. That path assumes only a small move in profit margins, from 5.9% to 6.0%, so most of the earnings lift comes from that steady revenue build rather than a big margin reset. Any legal or operational friction at Aerie that slows revenue contribution or complicates markdown discipline can therefore ripple into this earnings bridge, even if the injunction is currently tied to a single sleepwear label.
Valuation expectations are anchored to that same 2029 destination. Consensus modelling points to American Eagle Outfitters generating about US$6.4b of revenue and US$381.6m of earnings in that year, with the stock trading on a P/E of 10.4x if those estimates play out. That multiple sits below the current P/E cited for the wider US specialty retail group, which suggests analysts are not baking in heroic assumptions. For investors, the practical read is that the China ruling may be more of a test of execution against already conservative numbers rather than a shock that forces a wholesale rewrite of the long term story.
American Eagle Outfitters' current analyst roadmap points to US$6.4b in revenue and US$381.6m in earnings by 2029, built on 3.6% yearly revenue growth and an earnings increase of about US$44.7m from US$336.9m today.
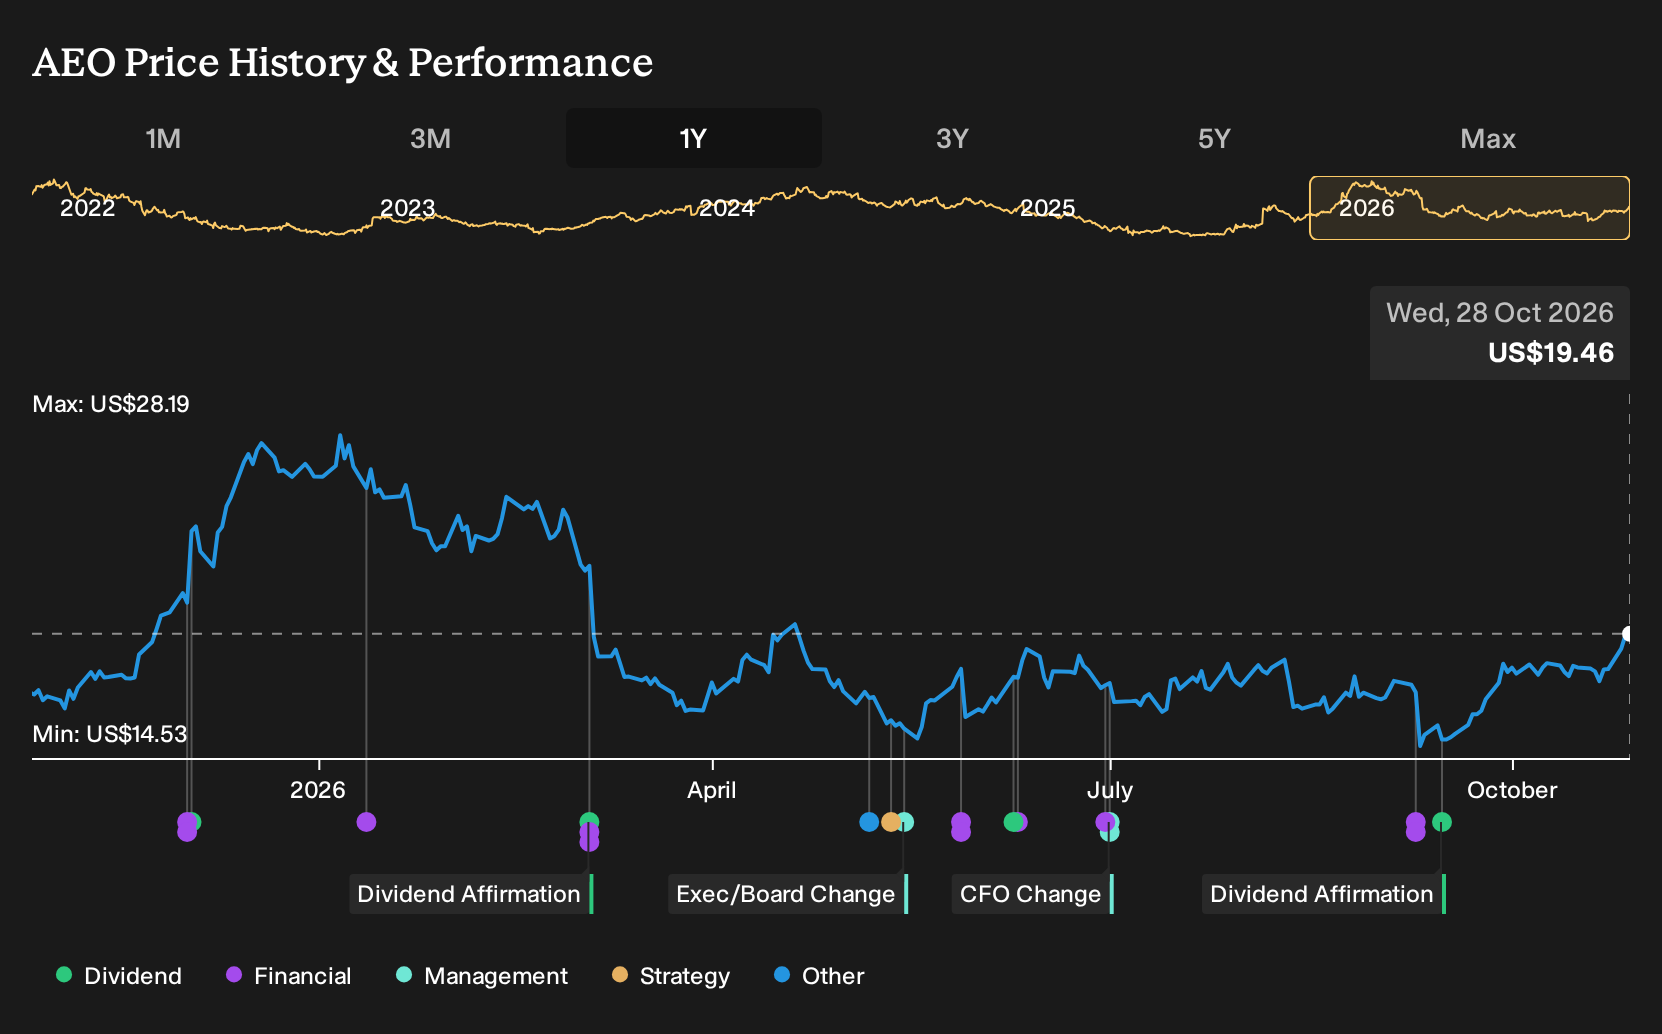
Uncover why American Eagle Outfitters' fair value indicates a 5% potential downside to its current price, suggesting a premium that may not be sustained.
Exploring Other Perspectives
Some of the most optimistic analysts treat Aerie and OFFLINE as the real story for American Eagle Outfitters, not the legal twists. Before this injunction, the bullish camp was modelling around US$6.7b of revenue and roughly US$457.6m of earnings by 2029. You should expect those more upbeat views to be revisited. This is exactly why comparing several narratives can help you decide how much this ruling matters in your own framework.
Explore 3 other American Eagle Outfitters fair value estimates, including one that suggests as much as 54% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your American Eagle Outfitters research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Eagle Outfitters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Eagle Outfitters' overall financial health at a glance.
Looking For More Investment Ideas Beyond American Eagle Outfitters?
If this Aerie injunction has you reassessing your exposure, it can help to widen the lens and scan other businesses with different risk and balance sheet profiles using the Simply Wall St Screener.
- For investors who care most about capital strength and staying power, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stretching the finances too far.
- If you are hunting for value where quality and pricing look out of sync, review a hand picked set of 26 high quality undervalued stocks that pair fundamental strength with more modest expectations baked into the share price.
- Those looking to prioritise stability and income can scan a curated pool of 6 dividend fortresses that focus on higher yields backed by business models built for regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com