


Adhesive manufacturing company Avery Dennison (NYSE:AVY) reported revenue ahead of Wall Street’s expectations in Q3 2026, as revenue rose 5.2% year on year to $2.33 billion. Its non-GAAP profit of $2.42 per share was 4.1% above analysts’ consensus estimates.
For more on Avery Dennison, read our full research report for free.
Avery Dennison (AVY) Q3 2026 highlights:
- Revenue $2.33 billion vs S&P analysts’ consensus estimates of $2.27 billion (5.2% year-on-year growth, 2.6% beat)
- Adjusted EPS $2.42 vs S&P analysts’ consensus estimates of $2.32 (4.1% beat)
- Adjusted EBITDA $367.7 million vs analysts’ consensus estimates of $358.7 million (15.8% margin, 2.5% beat)
- Adjusted EPS guidance Management slightly raised its full-year adjusted EPS guidance to $10.17 at the midpoint
- Operating margin 11.7%, in line with the same quarter last year
- Free cash flow margin 10.5%, down from 12.1% in the same quarter last year
- Organic revenue rose 3.7% year on year (beat)
- Market capitalization $13.69 billion
“We delivered another quarter of strong results, highlighted by continued improvement in our underlying organic sales and earnings growth,” said Deon Stander, Avery Dennison’s president and CEO.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Avery Dennison’s revenue grew at a sluggish 2.7% compounded annual growth rate over the last five years, falling short of our benchmarks.
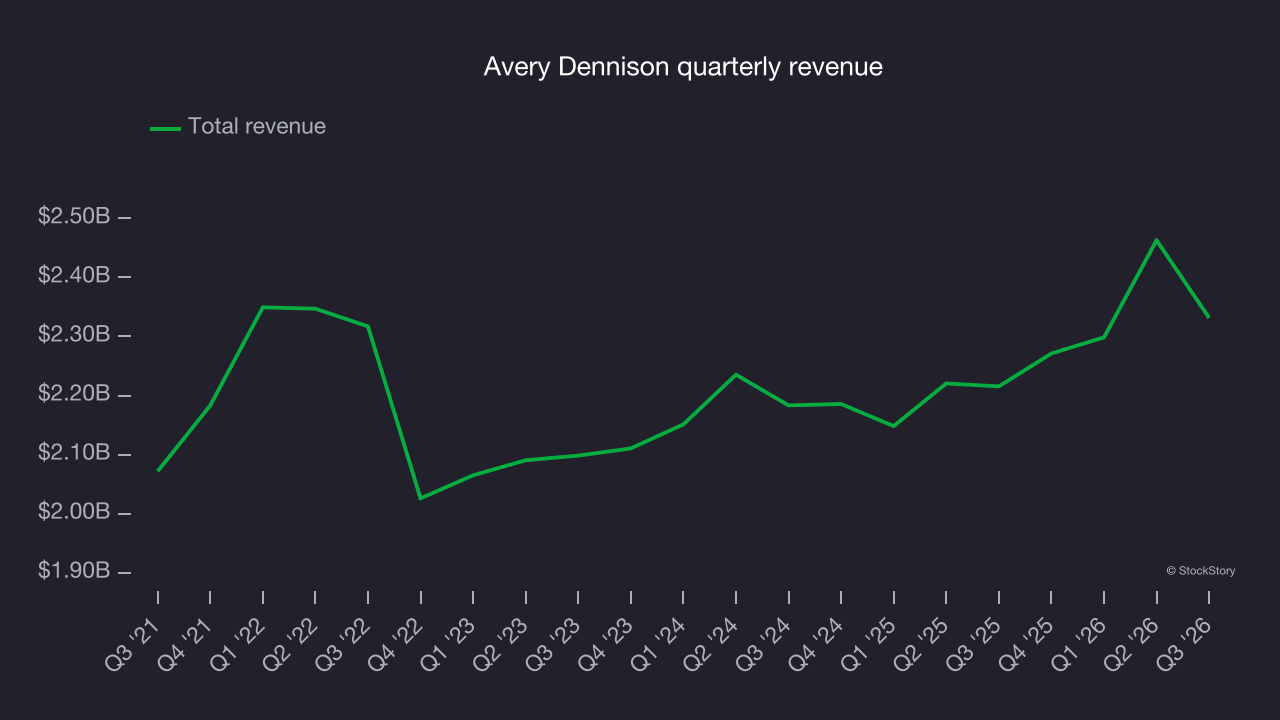
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Avery Dennison’s annualized revenue growth of 3.9% over the last two years is above its five-year trend, an encouraging improvement. 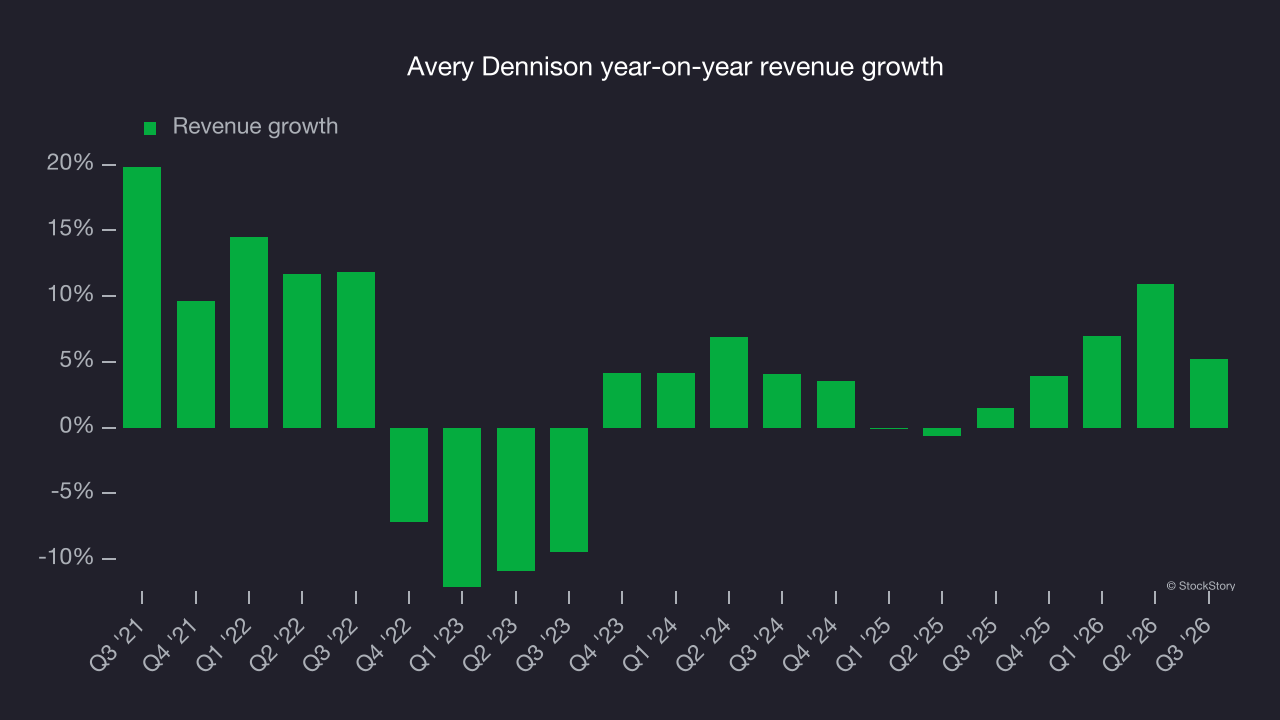
Examining organic revenue offers more detail on the company’s revenue dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Avery Dennison’s organic revenue averaged 2.1% year-on-year growth. Total revenue growth outpaced organic revenue growth over that period, indicating that a combination of acquisitions and foreign exchange rates boosted its headline results. 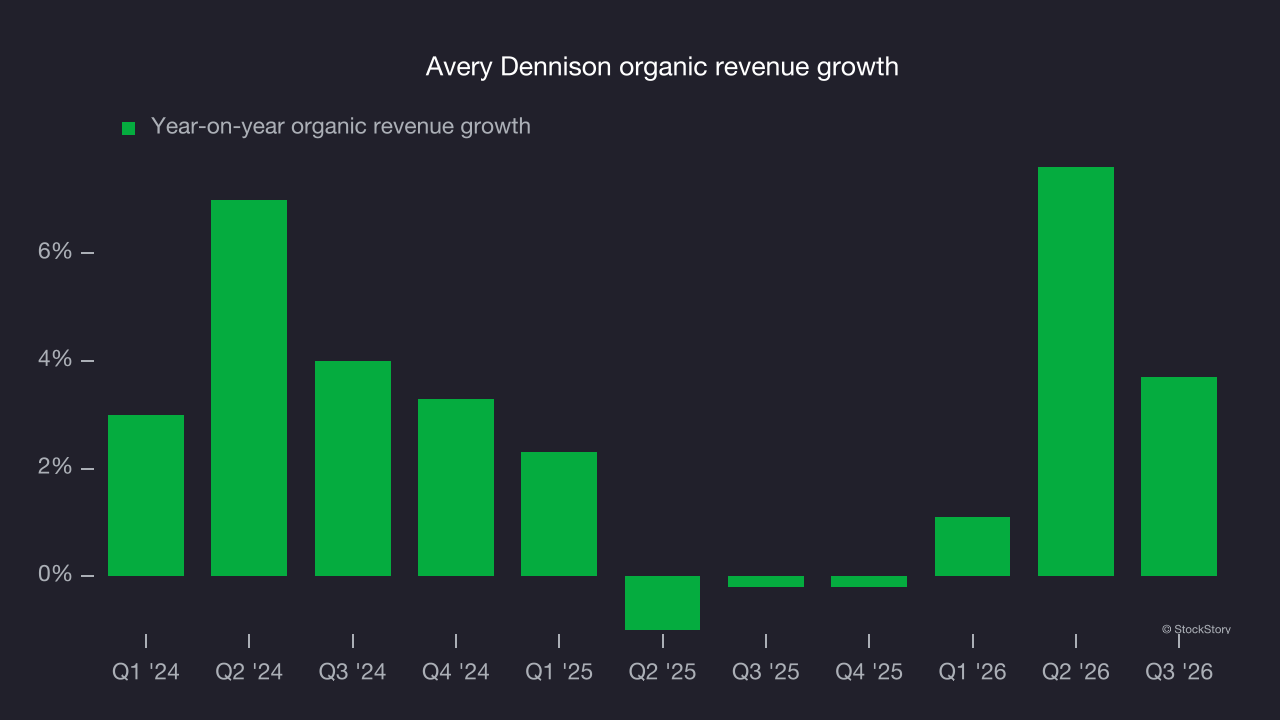
This quarter, Avery Dennison reported year-on-year revenue growth of 5.2%, and its $2.33 billion of revenue exceeded Wall Street’s consensus estimates by 2.6%.
Looking ahead, sell-side analysts expect revenue to grow 2% over the next 12 months, according to S&P, a slight deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges.
Operating margin
Avery Dennison’s operating margin has generally stayed the same over the last 12 months, averaging 11.4% over the last five years. This profitability was solid for an industrials business and shows it’s an efficient company that manages its expenses well. This result was particularly impressive given its low gross margin, which is mostly a factor of what it sells and requires major shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins indicate well-managed operations.
Analyzing the trend in its profitability, Avery Dennison’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. Margin expansion would be preferable, but Avery Dennison’s performance held up well considering most industrial packaging companies saw their margins decline.
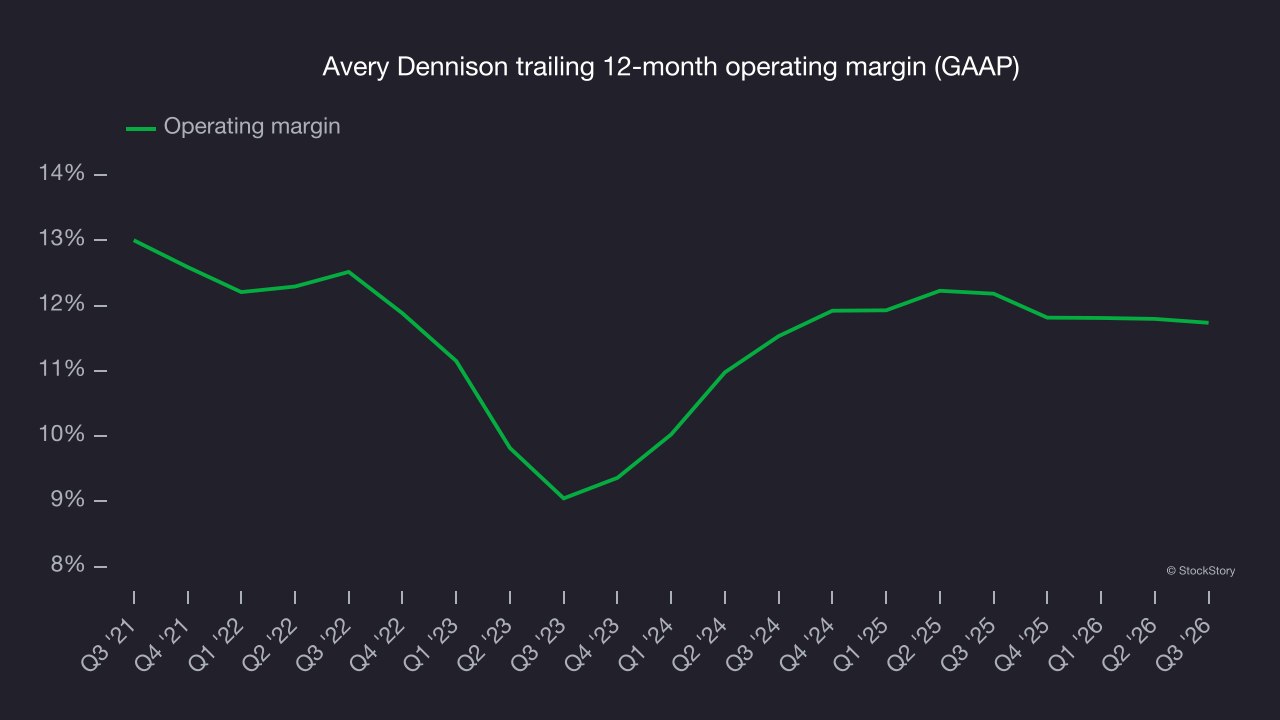
In Q3, Avery Dennison generated an operating margin of 11.7%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Avery Dennison’s weak 2.5% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
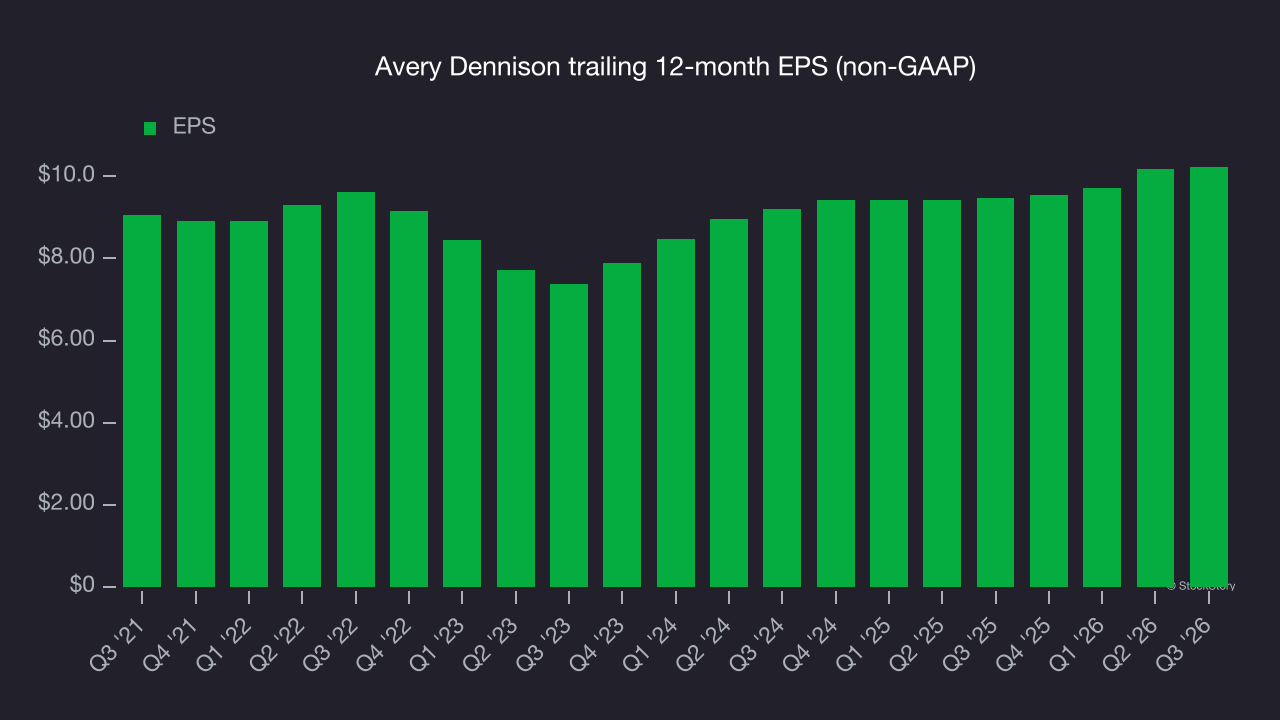
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Avery Dennison, its two-year annual EPS growth of 5.4% was higher than its five-year trend. Accelerating earnings growth is almost always an encouraging data point.
In Q3, Avery Dennison reported adjusted EPS of $2.42, up from $2.37 in the same quarter last year. This result beat analysts’ consensus estimates by 4.1%. Over the next 12 months, Wall Street expects Avery Dennison’s full-year EPS to grow 6.2% from $10.23 to $10.86, according to S&P.
Key takeaways from Avery Dennison’s Q3 results
Avery Dennison’s next-quarter EPS guidance came in well above analysts’ consensus estimates, and organic revenue also topped Wall Street’s estimates. Those were key positives in a solid quarter. Shares remained flat at $181.31 immediately after the results.
Avery Dennison may have had a good quarter, but that alone does not determine whether to invest. That decision should take into account its valuation, business quality and latest quarterly results. For more on those factors, read the full research report here (it’s free).