


Zai Lab has seen its share price move sharply over the past few years, and that swing now raises a straightforward question for investors who care about fundamentals. Is the current US$23.04 price tag adequately supported by the sales the company generates today and what those revenues may reasonably lead to over time.
- Over the past 5 years, the stock has declined 77.6%. This puts the focus squarely on whether the valuation now lines up with the business it reflects.
- Positive trial data for zocilurtatug pelitecan in extensive-stage small cell lung cancer and a recent US$250m private placement can shape future revenue expectations and the funding available to reach them, which both feed directly into how much investors are prepared to pay for each dollar of sales.
- There is a second opinion on Zai Lab worth weighing. See what analysts think Zai Lab's shares could be worth.
The issue now is whether Zai Lab's current market value is justified by its sales when judged against the Fair Ratio benchmark.
If you are considering Zai Lab at US$23.04 and want other reference points for oncology and biotech style bets, compare it with our screener containing 19 high quality undiscovered gems.
Does Zai Lab Look Pricey on Sales?
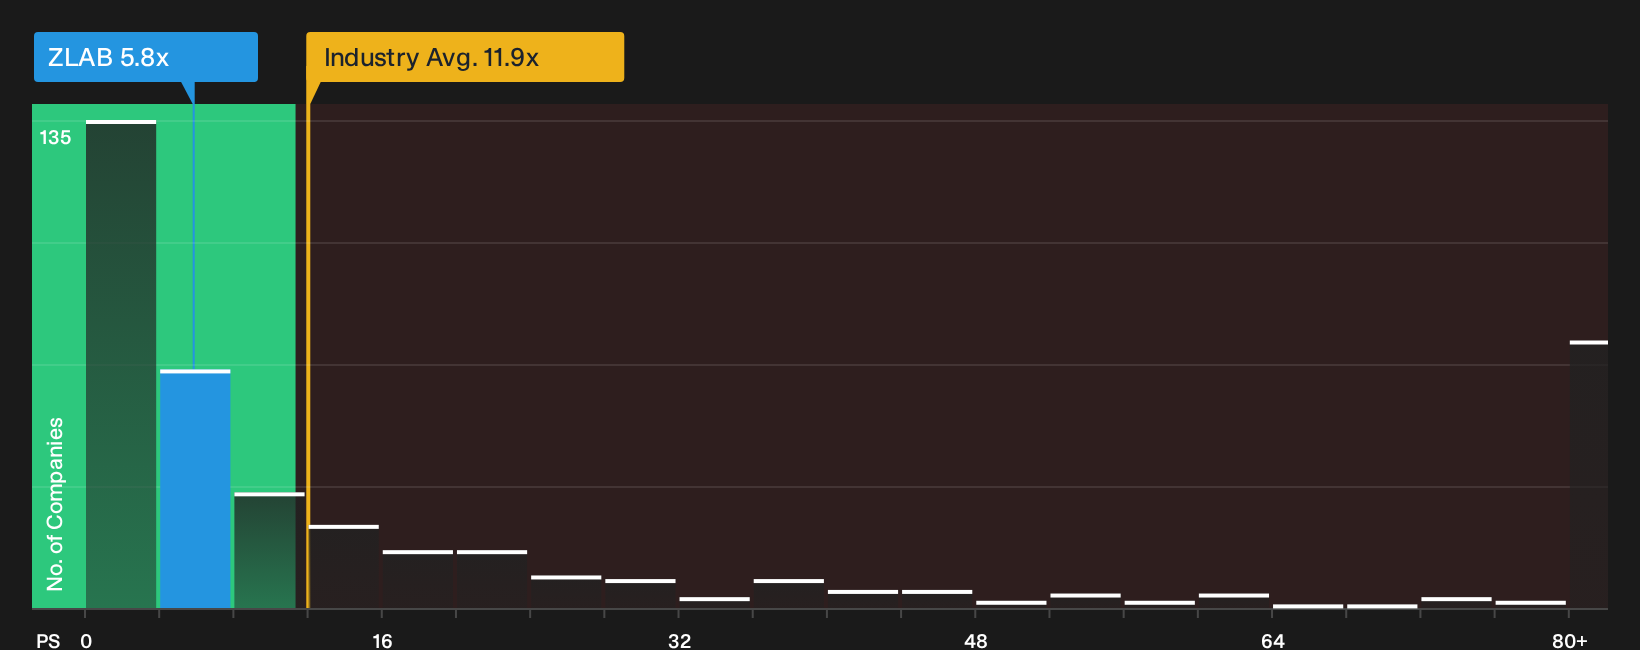
P/S fits Zai Lab better than P/E right now because the business is still loss making and investors are mainly anchoring expectations to revenue potential. At a P/S of 5.8x, the stock trades below the broader Biotechs sector on 11.9x and under the 9.5x peer average, so the market is already applying a sizeable discount to each dollar of current sales compared with similar oncology and biotech companies.
The tailored Fair Ratio benchmark, which blends factors like expected growth, profitability profile, size and risk, still sits lower than Zai Lab’s current 5.8x P/S. As a result, the shares screen overvalued on this framework despite the apparent discount to peers. Because the strong early data for zocilurtatug pelitecan has raised attention around the pipeline, the P/S gap to the Fair Ratio suggests sentiment is giving the stock more credit than this cash flow model does for now. Explore the numbers behind Zai Lab's P/S valuation.
The Zai Lab Narrative: What Would Justify Today's Price?
Narratives for Zai Lab pick up where the valuation puzzle leaves off and explain what kind of future on growth, margins and earnings would need to occur for the stock to be worth significantly more or less than today’s price on Simply Wall St's Community page. Instead of stopping at a single output from a ratio or model, they describe the business path that number implies so you can observe over time whether reality aligns with those assumptions.
One of the top community narratives on Zai Lab: roughly fairly valued
"The main factor that has to go right is that Zai Lab turns its emerging global pipeline into successful approvals while keeping operating expenses broadly stable…"
Discover why this Narrative puts Zai Lab at roughly fairly valued.
One last Zai Lab check that belongs next to the price tag
Before you file Zai Lab away as cheap, expensive, or somewhere in between, it is worth pausing on the separate set of risk indicators our research has picked up and weighing what they might mean for your thesis. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com