


As the Canadian market navigates a landscape of fluctuating indices and evolving economic conditions, investors are increasingly focused on companies that demonstrate resilience and potential for growth. In this context, high insider ownership can be a compelling indicator of confidence in a company's future prospects, making it an important consideration when evaluating growth stocks on the TSX.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 15.2% | 128.9% |
| Propel Holdings (TSX:PRL) | 25.7% | 33.7% |
| Obsidian Energy (TSX:OBE) | 11.2% | 40.3% |
| New Found Gold (TSX:NFGC) | 12.3% | 77.4% |
| LSL Pharma Group (TSXV:LSL) | 24.5% | 57.0% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32.1% |
| goeasy (TSX:GSY) | 19.5% | 123% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 131.8% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.6% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
Here we highlight a subset of our preferred stocks from the screener.
goeasy (TSX:GSY)
Simply Wall St Growth Rating: ★★★★★☆
Overview: goeasy Ltd. offers non-prime leasing and lending services through its easyhome, easyfinancial, and LendCare brands to Canadian consumers, with a market cap of CA$701.34 million.
Operations: The company's revenue is primarily generated from its Easyfinancial segment at CA$1.36 billion and its Easyhome segment at CA$145.02 million.
Insider Ownership: 19.5%
goeasy demonstrates potential as a growth company with high insider ownership, despite recent challenges. The company forecasts robust earnings and revenue growth, outpacing the Canadian market. Recent strategic moves include renewing a $910 million debt facility to align funding needs and reduce costs. However, financial strains are evident with suspended dividends and share repurchases following reduced earnings in 2025. Leadership changes aim to enhance risk management and data capabilities for sustained growth.
- Take a closer look at goeasy's potential here in our earnings growth report.
- Upon reviewing our latest valuation report, goeasy's share price might be too optimistic.
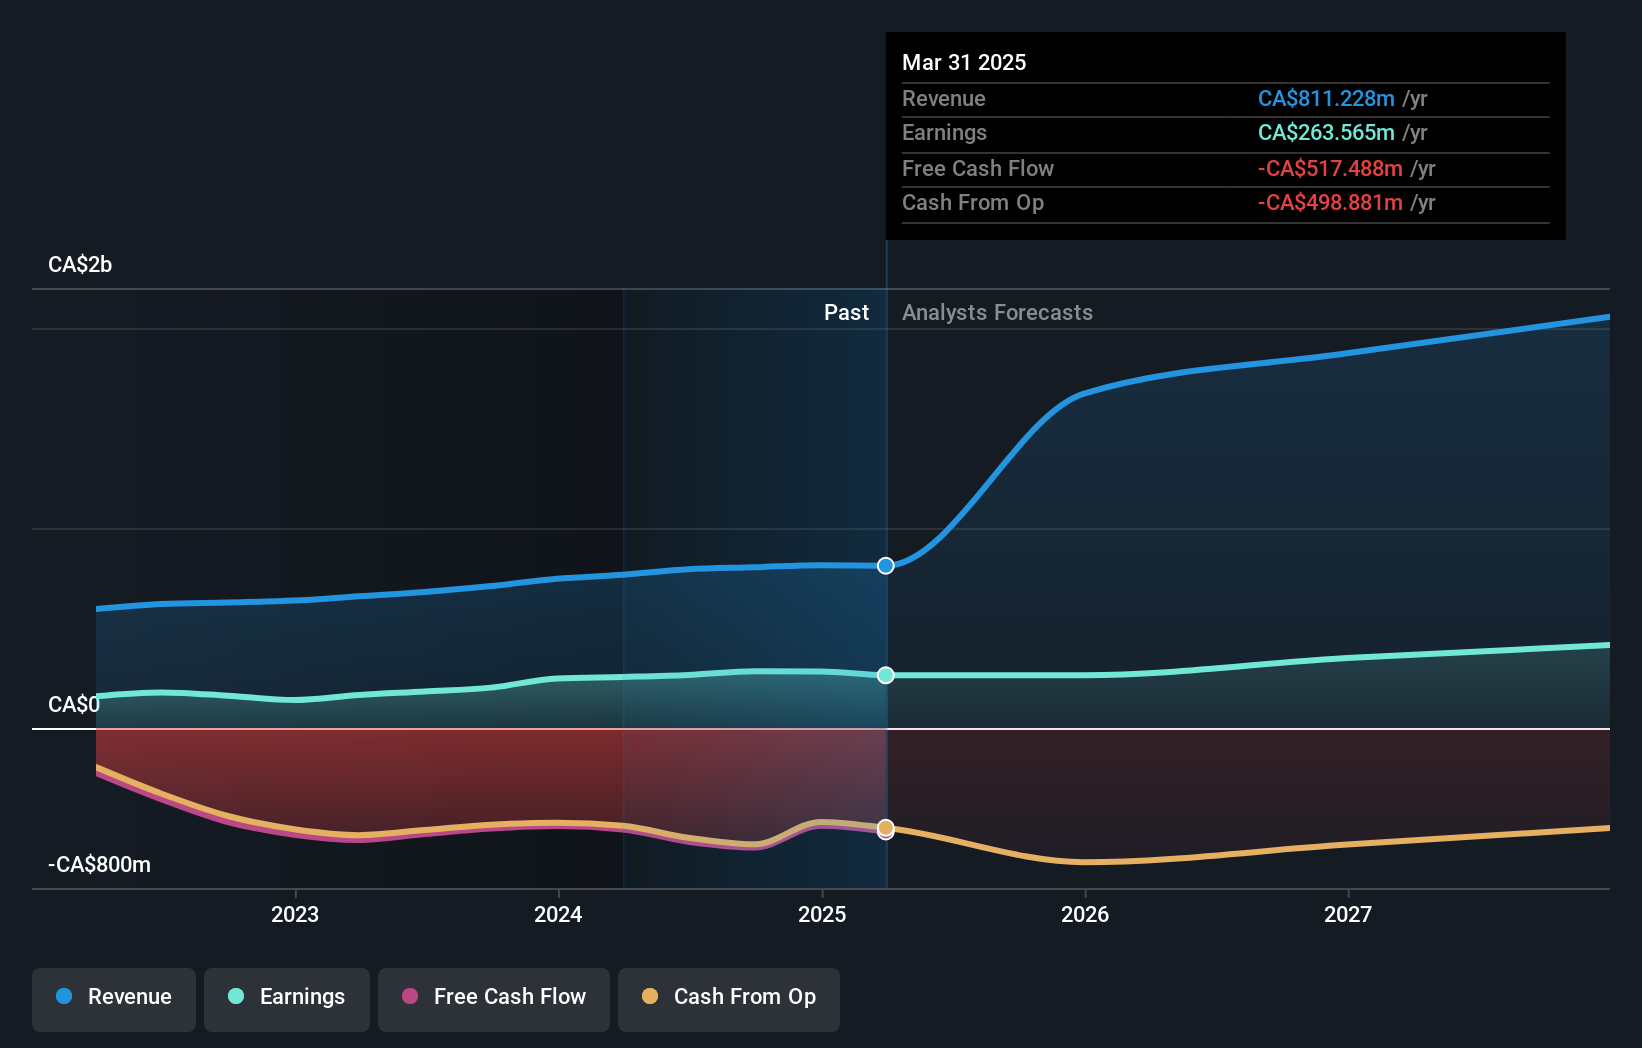
Hammond Power Solutions (TSX:HPS.A)
Simply Wall St Growth Rating: ★★★★★★
Overview: Hammond Power Solutions Inc., along with its subsidiaries, designs, manufactures, and sells various transformers across Canada, the United States, Mexico, and India; it has a market cap of CA$2.83 billion.
Operations: The company generates revenue of CA$1.06 billion from the design, manufacture, and sale of transformers across its operational regions.
Insider Ownership: 27.1%
Hammond Power Solutions shows promise with strong forecasted revenue growth of 22.1% annually, surpassing the Canadian market. Despite a decline in profit margins from 9.6% to 5.8%, earnings are expected to grow significantly at 32.1% per year. The company is expanding its manufacturing capacity with a new facility in Texas, enhancing service capabilities for U.S.-based customers, while recent board changes may influence strategic direction positively amidst insider selling activities.
- Unlock comprehensive insights into our analysis of Hammond Power Solutions stock in this growth report.
- Our comprehensive valuation report raises the possibility that Hammond Power Solutions is priced lower than what may be justified by its financials.
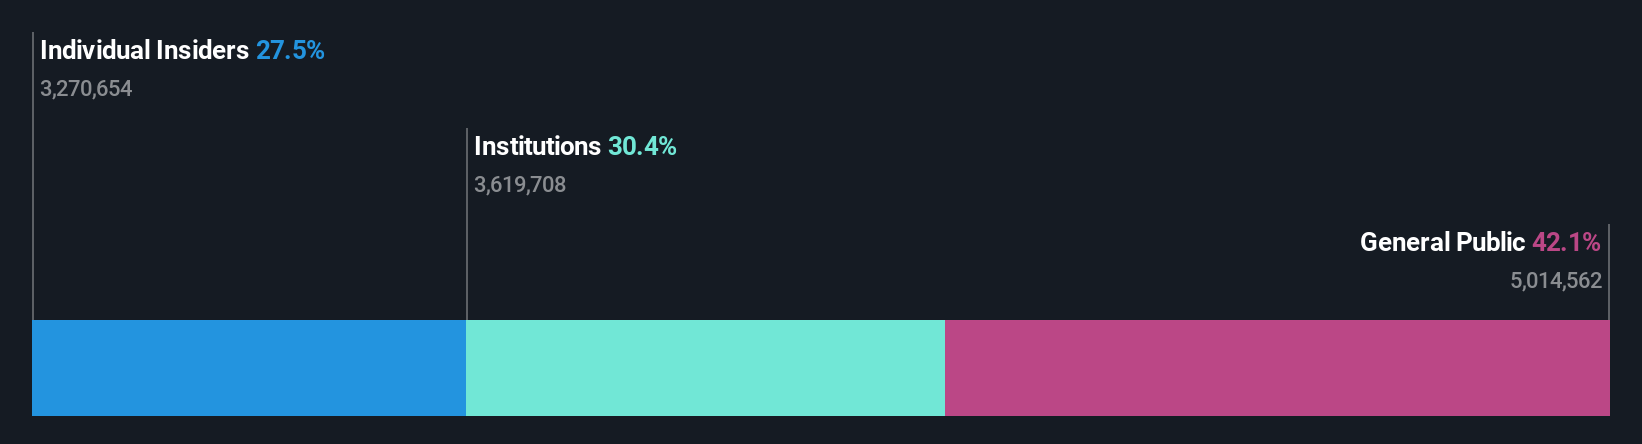
Lightspeed Commerce (TSX:LSPD)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Lightspeed Commerce Inc. provides cloud-based software subscriptions and payment solutions for retailers, restaurants, golf course operators, and other businesses with a market cap of CA$1.97 billion.
Operations: The company's revenue is primarily derived from its software and programming segment, which generated $1.24 billion.
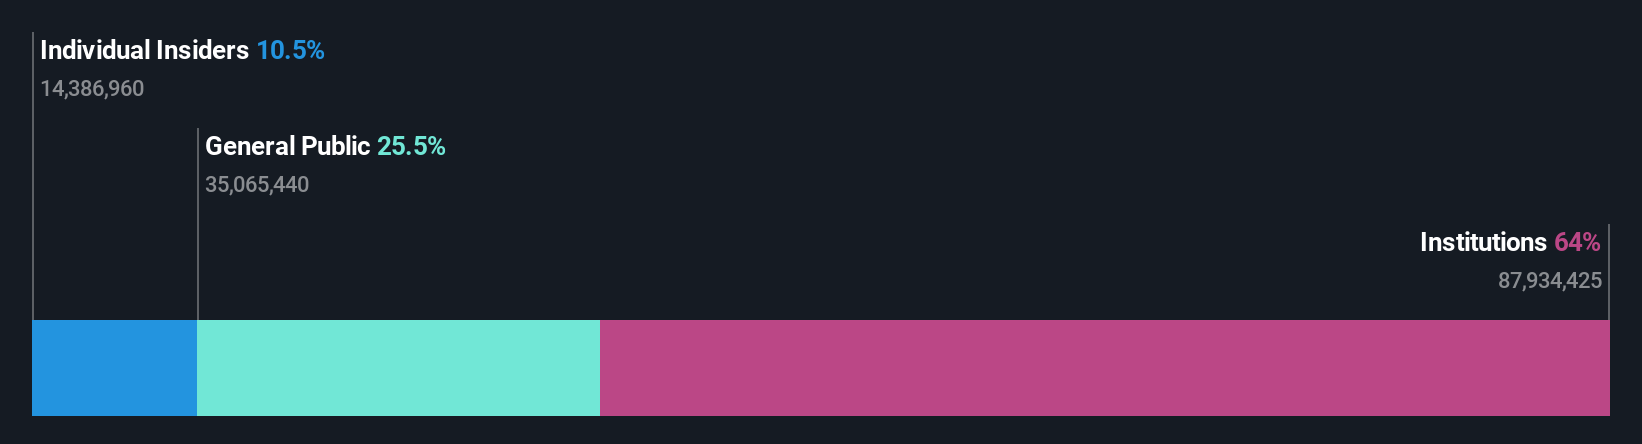
Insider Ownership: 10.9%
Lightspeed Commerce faces mixed prospects as it trades at a good value, 69.8% below its estimated fair value, yet experiences significant insider selling over the past quarter. Despite forecasted revenue growth of 8.7% per year, which outpaces the Canadian market average, profitability remains elusive with earnings projected to grow substantially by 127.75% annually over three years. Recent innovations in AI capabilities and strategic partnerships aim to enhance operational efficiency and customer engagement across retail and golf sectors.
- Dive into the specifics of Lightspeed Commerce here with our thorough growth forecast report.
- Our valuation report here indicates Lightspeed Commerce may be undervalued.
Next Steps
- Delve into our full catalog of 50 Fast Growing TSX Companies With High Insider Ownership here.
- Ready For A Different Approach? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com