


Synopsys, Inc. (SNPS), headquartered in Sunnyvale, California, is a technology company providing engineering solutions for semiconductor and system design. Its offerings include electronic design automation software, semiconductor intellectual property, and simulation and analysis tools, helping companies develop AI-powered products and accelerate innovation across industries. The company has a market capitalization of approximately $73.8 billion.
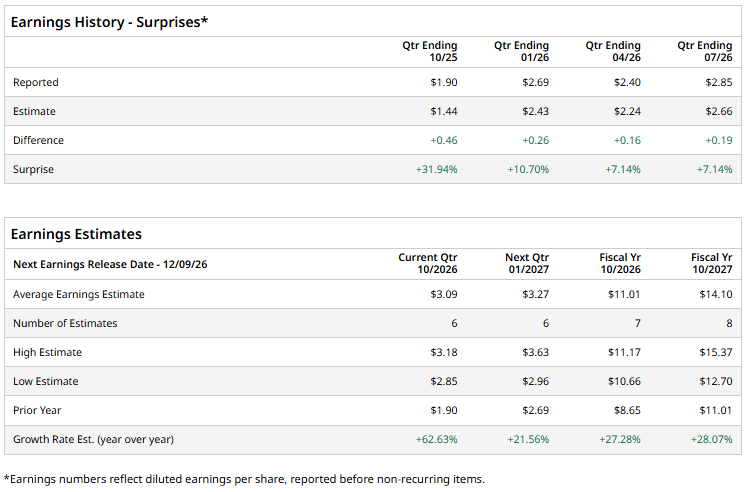
SNPS is set to report its Q4 earnings soon. Ahead of the release, analysts expect the company to report diluted EPS of $3.09, up substantially by 62.6% from $1.90 in the year-ago quarter. SNPS has surpassed Wall Street’s EPS estimates in each of the past four quarters, an impressive track record.
For fiscal 2026, analysts project EPS to climb 27.3% year over year to $11.01, compared with $8.65 in fiscal 2025. Growth is expected to accelerate further in fiscal 2027, with EPS forecast to rise another 28.1% to $14.10.
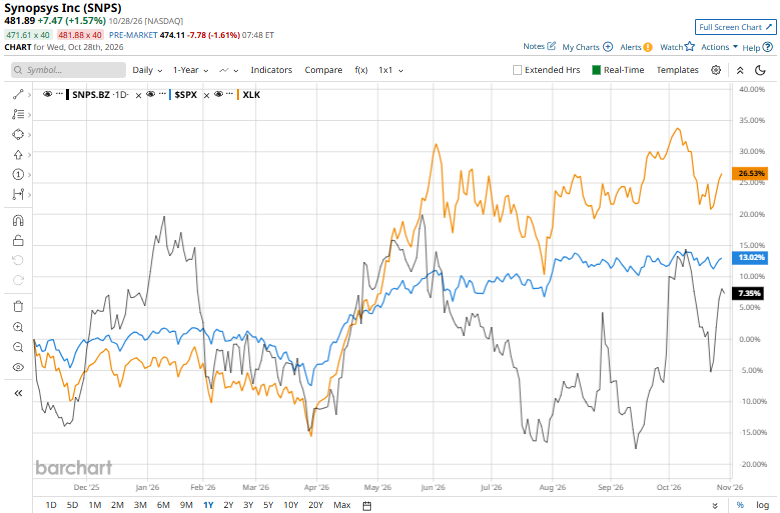
SNPS shares have risen 5.5% over the past 52 weeks, underperforming the S&P 500 Index ($SPX), which returned 12.4%, and the State Street Technology Select Sector SPDR ETF (XLK), which gained 26.5% over the same period.
Synopsys is rebounding from a difficult stretch, with shares rising more than 30% from their September lows after falling over 20% year to date through mid-September. Its recovery is supported by a more than $1 billion Amazon IP deal and an OpenAI partnership focused on AI-driven chip design, which could expand revenue opportunities and demand for its electronic design automation tools. Management has raised its fiscal 2030 targets to mid-teens revenue CAGR and a 50% adjusted operating margin, while targeting $1 billion in application-optimized IP revenue by 2030 from existing deals and commitments.
Analysts remain bullish on SNPS, with the stock carrying a consensus “Strong Buy” rating. Of the 20 analysts covering the stock, 18 recommend a “Strong Buy,” one rates it a “Moderate Buy,” and one recommends a “Hold.” The average price target of $593.10 implies 23.1% upside from the current share price.
On the date of publication, Abhishek Bhuyan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.