


PHINIA (PHIN) is back in focus after mixed quarterly results, where solid revenue and cash generation sat alongside weaker margins, reduced profitability guidance, and investor questions around the pending stoba Group acquisition.
PHINIA’s share price has slipped over the past quarter, with a 90 day share price return down 21.05% and a 30 day move down 5.04%, as investors reassess margin risk and the stoba Group deal, even though the 1 year total shareholder return is 12.84% and the 3 year total shareholder return is very large.
Compare PHINIA's recent pullback with other hand picked industrials by reviewing the 26 high quality undervalued stocks that pair resilient balance sheets with solid cash generation.
PHINIA’s pullback, mixed earnings, and looming stoba Group deal present a simple fork in the road. Do you lean into today’s reset, or wait and see what the valuation is really offering?
Most Popular Narrative: 35% Undervalued
PHINIA’s most followed narrative pegs fair value at $88.20 against a last close of $57.68, which frames today’s pullback as a sizeable discount. That view leans heavily on how the business is shifting its mix and where future earnings could come from.
PHINIA is pushing into higher margin aftermarket, service and adjacent applications like aerospace, defense and industrial, with the aim that continued scaling and a mix shift toward these areas helps offset pressure in legacy combustion programs. The current valuation suggests the market is not fully reflecting PHINIA’s cash generation, capital returns and activity in aftermarket and alternative fuel programs.
See why 9 investors see PHINIA as 35% undervalued.
Result: Fair Value of $88.20 (UNDERVALUED)
Still, PHINIA’s heavy reliance on internal combustion technologies and the lower 2026 EBITDA margin outlook mean that a faster tilt to full electrification could quickly challenge this undervalued thesis.
Find out about the key risks to this PHINIA narrative.
Another View: PHINIA On Earnings Multiples
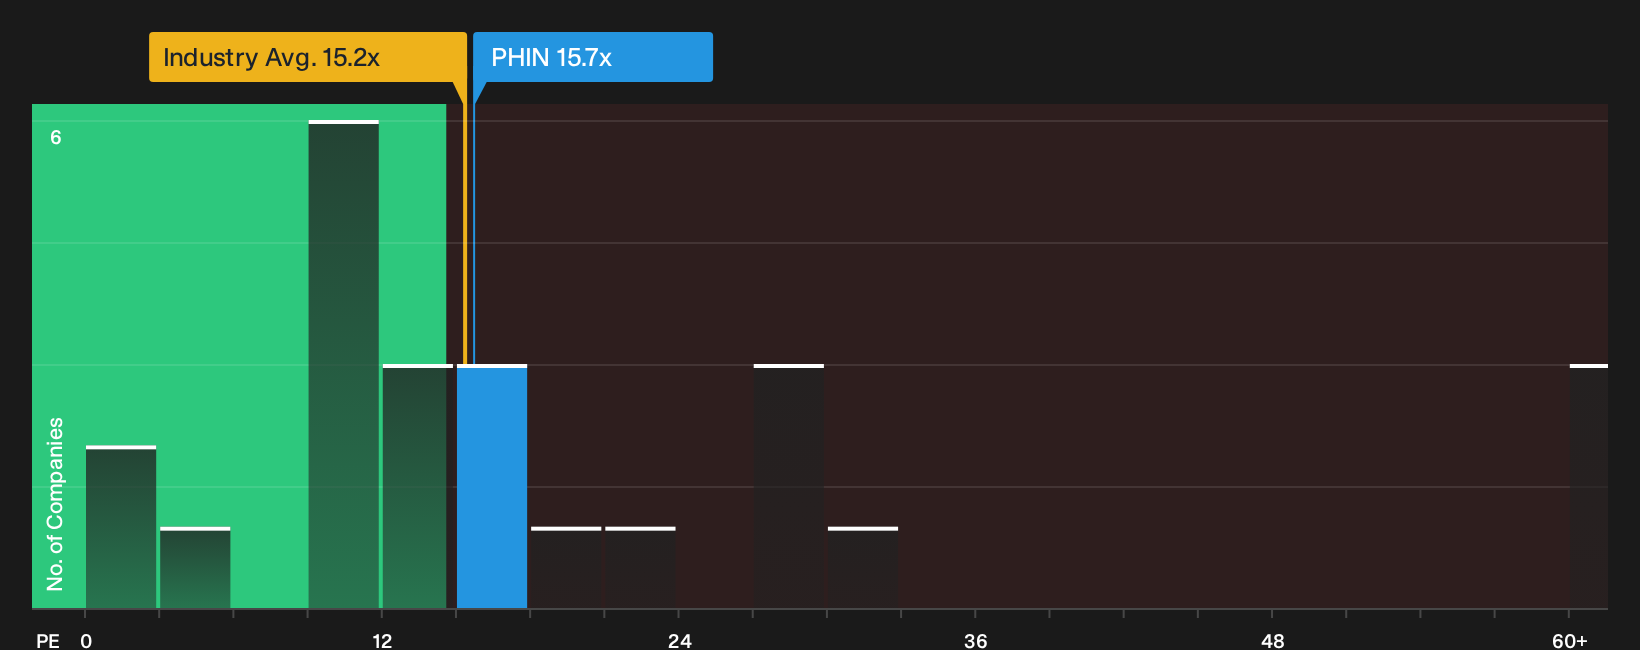
There is a catch to the PHINIA undervaluation story. On earnings, the stock trades at a P/E of 15.7x, which is above its own fair ratio of 13.9x and in line with the US Auto Components industry at 15.7x. That gap suggests some valuation risk if sentiment moves closer to the fair ratio. Is the cash flow case strong enough for you to look past that?
To test whether this price is really justified by the current fundamentals, take a closer look at how the earnings-based valuation stacks up against peers and the fair ratio in our breakdown, then decide if that premium feels comfortable for your risk tolerance. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed narratives around PHINIA only matter if you use them. Act quickly, stress test both the upside and the red flags, then weigh the 3 key rewards and 3 important warning signs
Looking for more PHINIA style investment ideas?
If you stop at PHINIA, you risk missing other stocks that could fit your plan. Put a few minutes into fresh ideas and widen your opportunity set.
- Target resilient compounding potential by reviewing a curated 26 high quality undervalued stocks that combine solid cash generation with disciplined balance sheets.
- Strengthen your income stream with a focused 6 dividend fortresses that aim to pair higher yields with durable underlying businesses.
- Ring fence your downside risk by scanning a 32 resilient stocks with low risk scores that score well on financial resilience and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com