


- Cinemark Holdings recently saw earnings estimates for the September 2026 quarter revised higher, with analysts now projecting earnings per share of US$0.94 and revenue expectations that are above the prior year period.
- The combination of stronger forecast earnings, an Earnings ESP of +5.33%, and a Zacks Rank of #1 ties the latest outlook directly to Cinemark Holdings' underlying cash generation and premium format rollout rather than just sentiment.
- We will now look at how Cinemark Holdings' investment narrative could be shaped by the recent upward revisions to near term earnings.
Scan how Cinemark Holdings’ earnings story compares with other potential rebound candidates by reviewing a curated set of 19 high quality undiscovered gems with similar cash flow support and operational momentum narratives.
Cinemark Holdings Investment Narrative Recap
To hold Cinemark Holdings, you need to believe the theatrical model can keep pulling people off the couch and into higher spend per visit, helped by premium formats and loyalty programs. The latest earnings revision story speaks directly to that. Stronger near term expectations lean on ticket and concession economics and auditorium upgrades, not just box office headlines.
The near term swing factor stays the same: execution around premium formats, Movie Club engagement and Latin America utilization. The biggest risk remains leverage on a cost base that is both fixed and pressured by energy and maintenance, especially if film slates or pricing power soften at the same time.
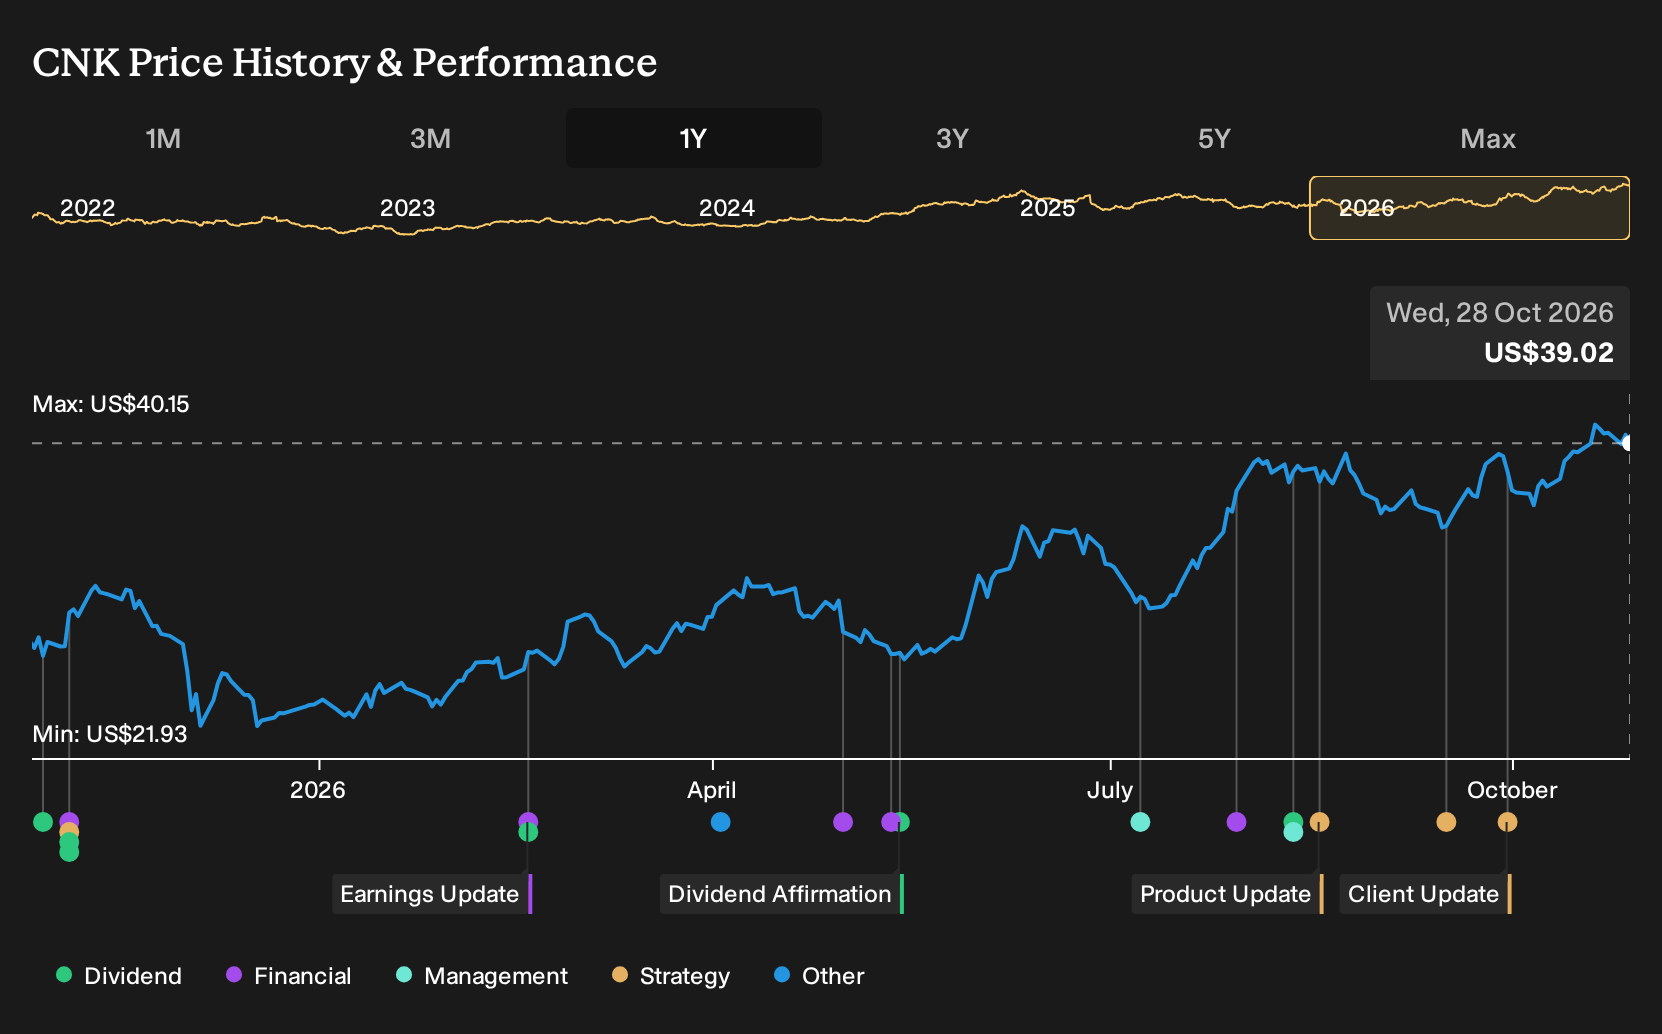
The most relevant piece of news is the fresh earnings setup for the September 2026 quarter. Analysts are looking for US$0.94 in earnings per share and revenue that is above the prior year period, with the report due on 3 November 2026. That keeps attention squarely on operating performance rather than one off factors.
If Cinemark Holdings reports numbers in line with or stronger than those expectations, it would give investors one more data point on how premium screens, fuller release schedules and loyalty driven attendance translate into cash flow. A weaker result would highlight how exposed the model is to film slate variability and cost inflation, especially given the business already carries a meaningful debt load.
Cinemark Holdings' current earnings sit at US$214.4 million, with analyst consensus pointing to earnings of US$332.2 million and revenue of US$4.0 billion by 2029. That profile assumes 5.7% yearly revenue growth and an earnings increase of about US$117.8 million from today to the 2029 forecast period.
Uncover why Cinemark Holdings' fair value indicates that Cinemark Holdings is in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts frame alternative content as the real swing factor for Cinemark Holdings rather than just the next quarter’s EPS revision. Before this news, the bullish camp was modeling about US$4.1b of revenue and US$419.6 million in earnings by 2029. Those forecasts and the fresh estimate upgrade may end up colliding, so treat this as your cue to compare several narratives and not follow just one.
Explore 2 other Cinemark Holdings fair value estimates, including one that suggests as much as 111431% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cinemark Holdings research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cinemark Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cinemark Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cinemark Holdings?
If Cinemark Holdings has sharpened your thinking about earnings power and balance sheet pressure, use that same lens to scan a wider field of opportunities with the Simply Wall St screener and build a watchlist that fits your own risk and income profile.
- For investors who want quality at a reasonable price, start with companies that screen as attractively priced on cash flows and fundamentals through a curated set of 26 high quality undervalued stocks.
- If capital preservation matters most to you, focus on businesses that pair steadier operations with stronger financial resilience by reviewing a 32 resilient stocks with low risk scores that filters for lower risk profiles.
- Income focused investors can zero in on steadier payout potential by scanning a hand picked group of 6 dividend fortresses that combine higher yields with more robust underlying accounts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com