


Carvana has rewarded long term holders with a very large share price gain over the past three years, but the stock has recently pulled back and now trades near US$59, which raises a simple question for you as an investor. Is that price still in line with what its earnings can realistically support.
- Carvana's share price has delivered a very large 3 year return, which adds importance to the question of whether the current earnings base can support that kind of move.
- Recent news has highlighted rapid revenue expansion alongside a reset of profitability expectations, which can change how much value the market assigns to each dollar of earnings.
- There is a second opinion on Carvana worth weighing. See what analysts think Carvana's shares could be worth.
The stock's next move may depend on whether Carvana's current earnings justify today's market price or point to a gap between price and profit power.
If you want to stress test this same earnings question beyond Carvana, you can run the rule over a wider field using 26 high quality undervalued stocks.
Is Carvana Fairly Priced on Earnings?
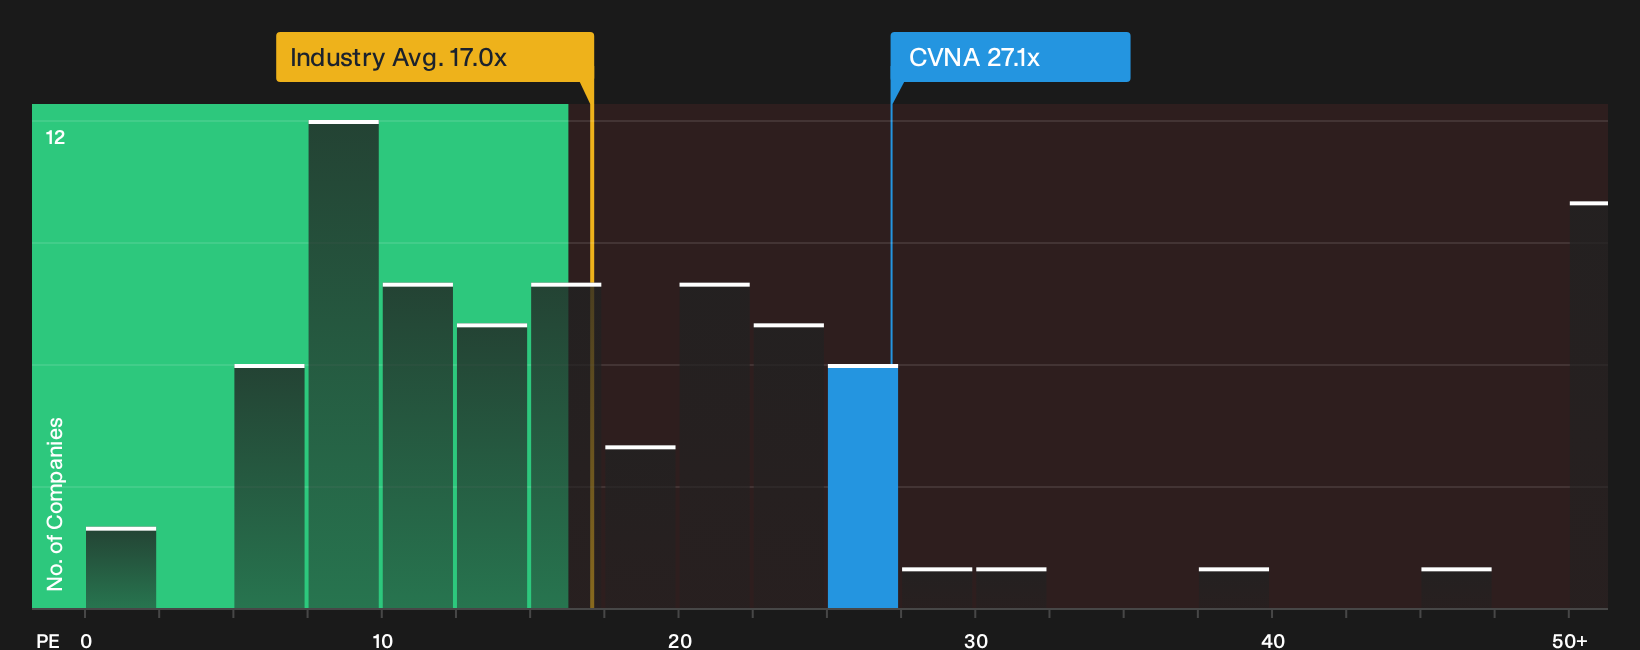
P/E works well for Carvana because the recent focus has been on earnings power rather than just revenue scale. On that score, the stock trades on a P/E of about 27.1x, compared with roughly 17.0x for the broader Specialty Retail industry and around 19.5x for close peers. That is a clear premium, and the market is paying more for each dollar of Carvana earnings than for many other retailers.
The in house fair multiple for Carvana, which blends its growth profile, margins, sector and risk, sits just below the current P/E, so the valuation screens about right rather than extremely stretched or obviously cheap. Because the latest Q2 update paired strong revenue growth with lower full year EBITDA guidance, this earnings multiple already bakes in optimism that the profit story can catch up over time. To judge whether that still works for you, it helps to weigh how much confidence you have in the business reaching the economics implied by a high teens to mid 20s P/E range. Explore the numbers behind Carvana's P/E valuation.
The Carvana Narrative: What Would Justify Today's Price?
For Carvana, Simply Wall St Narratives pick up where that P/E puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price. They sit on the Community page so you can track them over time. Rather than relying on a single multiple or model output, each narrative sets out the key assumptions behind its fair value so you can compare those inputs with actual results as they arrive.
One of the top community narratives on Carvana: 29% undervalued
"The main thing that has to go right is Carvana executing its inventory and reconditioning expansion so that unit growth, delivery speed and unit economics stay aligned..."
Discover why this Narrative puts Carvana at 29% undervalued.
Before You Decide On Carvana, There Is One More Piece To Check
Everything so far has focused on what Carvana looks like today, yet professional analysts have already mapped out where they think this business could be a few years from now and that reference point can sharpen how you read the current valuation. Explore where analysts expect Carvana to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com