


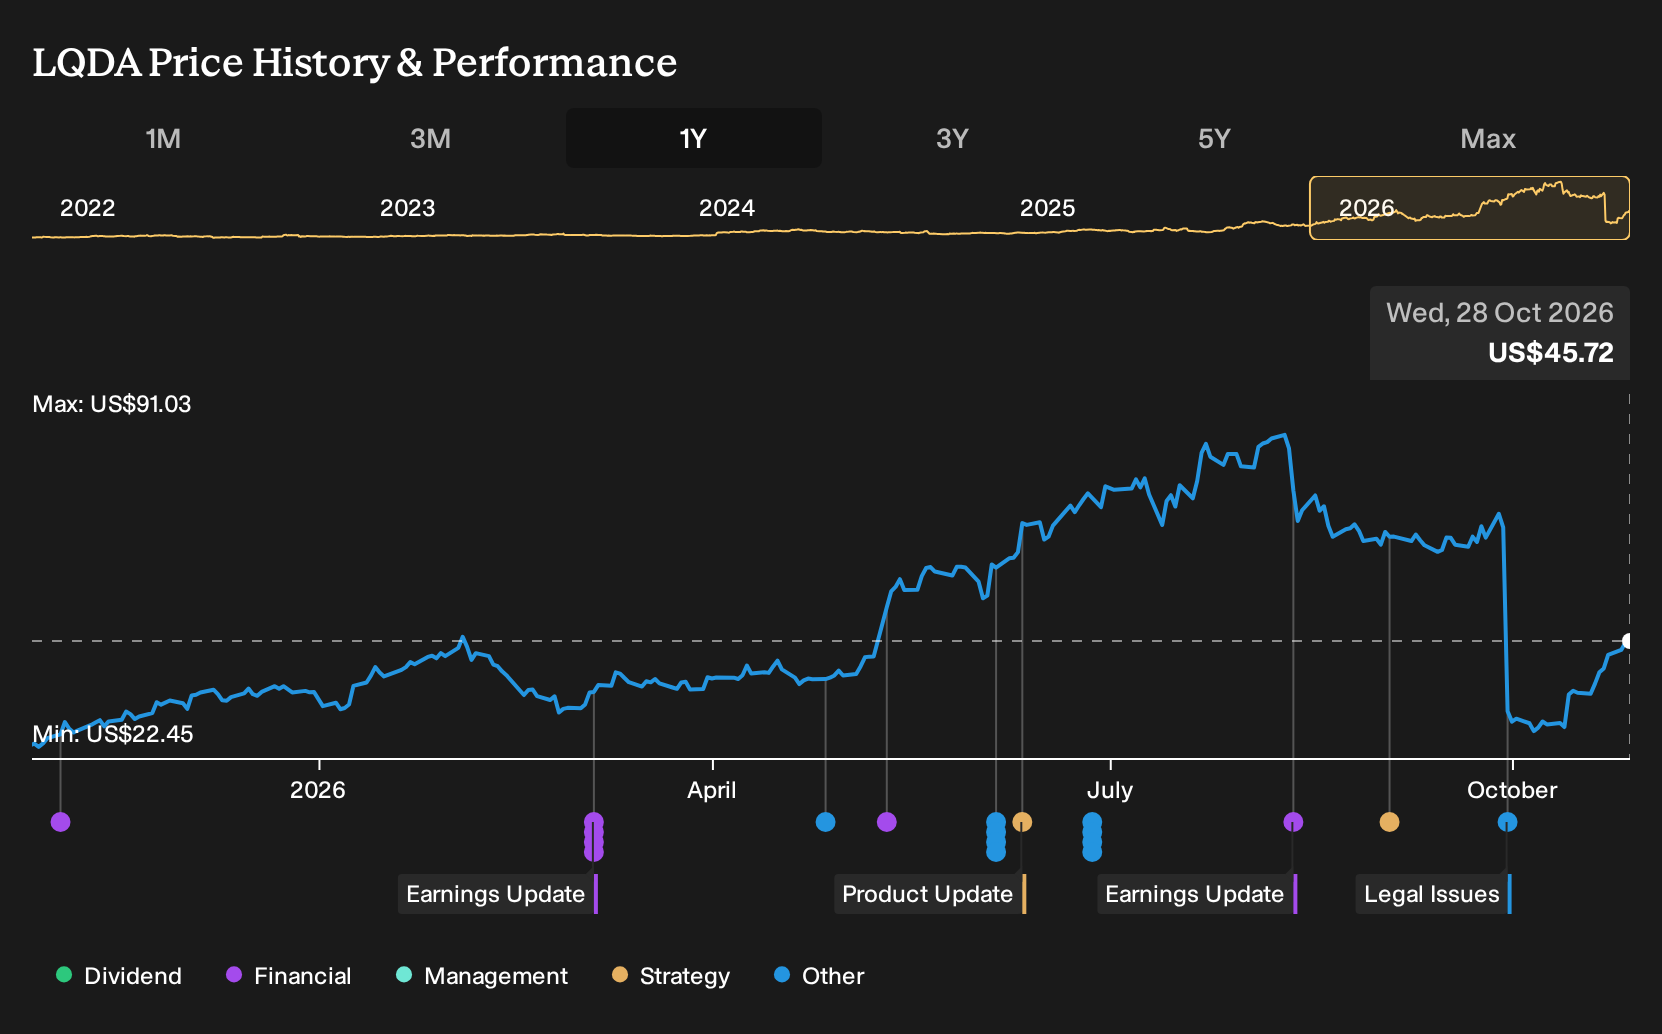
- Liquidia is heading into its September 2026 quarter with a consensus earnings forecast of $0.77 per share and expectations for materially higher revenue than the prior year period, while analysts have sharply reduced their EPS projections over the past month.
- The 84.6% cut to the consensus EPS estimate in just 30 days highlights growing concern about near term profitability, even as Liquidia continues to build out its pulmonary hypertension franchise and operational footprint.
- We will now look at how Liquidia's investment narrative intersects with sharply reduced near term earnings expectations and what that signals.
Broaden your watchlist by comparing Liquidia's setup with a curated pool of 26 high quality undervalued stocks showing strong fundamentals and cleaner earnings narratives.
Liquidia Investment Narrative Recap
To own Liquidia, you need to believe its pulmonary hypertension platform, led by YUTREPIA and followed by L606, can support durable prescriptions, solid payer access and efficient use of its PRINT and manufacturing assets. The sharp reset in near term earnings expectations mainly reflects the timing of profitability in the near term rather than a clear break in that longer thesis.
The more immediate swing factors still look operational. Prescription volume, gross to net dynamics as voucher patients convert to paid scripts, and how quickly the new North Carolina facility fills are likely to matter more than a single quarter. The biggest risk remains that real world usage or coverage terms eventually fall short of what this expanded infrastructure is built to handle.
With no fresh company specific announcements tied directly to this earnings update, the earlier decision to build out North Carolina manufacturing capacity stays front and center for this story. Management is preparing for potentially higher demand for YUTREPIA and future products like L606, which could support scale benefits if volumes are sufficient.
That same facility also concentrates execution risk. If longer term treprostinil demand, treatment patterns or competitive data soften usage, underused capacity could pressure cost of goods and margins just as earnings are under scrutiny. Looking across the coming quarters, the key question remains how efficiently Liquidia can translate clinical and payer momentum into profitable, repeatable product sales.
What Liquidia’s Long Range Assumptions Are Telling You
Liquidia's longer dated analyst models lean heavily on both revenue expansion and margin lift. The story in those spreadsheets is simple to describe even if it is complex to achieve in real life. Analysts are building in 26.8% yearly revenue growth over the next three years, along with a step up in profit margins from 30.7% today to 38.7% by year three. That combination assumes the pulmonary hypertension portfolio scales efficiently through the North Carolina facility and that payer contracts support cleaner conversion from prescriptions to net sales.
Earnings expectations in those same forecasts are sizeable. Consensus points to earnings of US$356.1 million in 2029 compared with US$138.6 million today. That is an increase of about US$217.5 million in absolute profit. For context, analysts see that outcome lining up with earnings per share of US$3.41, which implicitly bakes in share count growth of 2.89% a year over the next three years. The range of views is wide though, with the highest estimate at US$531.5 million and the lowest at US$283.1 million, which signals real disagreement about how effectively Liquidia can translate its pulmonary hypertension pipeline into cash flow.
On these figures, the long term framework for Liquidia rests on investors being comfortable with a different P/E profile than the wider US pharmaceuticals peer group. The current forward looking work assumes the stock would trade on a P/E of 18.1x those 2029 earnings, compared with 21.9x today and a sector level multiple of 14.8x. That means the thesis is not just about hitting a revenue and earnings path. It also assumes the market continues to ascribe a premium multiple to the business relative to the broader industry, even as growth matures and the story shifts from launch phase to a more recurring profit base.
Liquidia's narrative projects US$919.4 million revenue and US$356.1 million earnings by 2029. This requires 26.8% yearly revenue growth and an earnings increase of about US$217.5 million from US$138.6 million today.
For readers weighing these estimates against their own expectations, the key filters are straightforward. First, decide how comfortable you are with 26.8% annual top line expansion over several years in a specialist pulmonary hypertension market. Second, assess whether margin expansion from 30.7% to 38.7% feels realistic given the fixed cost of the new plant, potential pricing pressure and the mix of voucher versus paid prescriptions. Finally, consider whether a P/E near 18x in 2029 aligns with your view of where a focused biotech with concentrated product exposure should trade once YUTREPIA and a potential L606 follow on are more seasoned assets.
Uncover why Liquidia's fair value indicates a 17% potential upside to its current price, which suggests a valuation gap that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Liquidia focuses on the bullish catalyst of higher long term earnings. Before this earnings reset, the most optimistic analysts were modeling revenue growth of 36.8% a year and 2029 earnings of about US$589.5 million. That is far above the US$356.1 million consensus, so you should expect those views to evolve as you weigh fresh numbers of your own.
Explore 4 other Liquidia fair value estimates, including one that suggests up to 266% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Liquidia research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Liquidia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Liquidia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Liquidia?
If Liquidia has sharpened your thinking about risk, reward and timing, broaden the field a bit. Use the Simply Wall St Screener to scan for other businesses that line up with the kind of balance sheet strength, income profile or upside potential you want to target next.
- If capital protection is high on your list, start with companies that pair resilience with measured return potential by reviewing 32 resilient stocks with low risk scores.
- For readers who care about financial strength first, focus on businesses with cleaner leverage and liquidity profiles through the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for mispriced opportunities, concentrate on quality companies trading below their estimated worth using the 26 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com