


AMC Entertainment Holdings has seen its share price swing sharply in recent years, which puts a fresh spotlight on whether the current US$2.99 level lines up with what its sales can support. For anyone still following the cinema chain after that volatility, the real puzzle is how the stock now stacks up against the revenue the business brings in.
- Over the past 5 years the stock has fallen 98.6%, which puts long term shareholders squarely focused on whether the revenue base can justify even the current market value.
- With the business model still heavily reliant on box office and related in-theater spending, any change in how effectively AMC converts ticket and concession revenue into sustainable cash flow can reshape how investors think about the value of each dollar of sales.
- The analysts covering AMC Entertainment Holdings have run their own numbers. See what analysts think AMC Entertainment Holdings's shares could be worth.
The stock's next move may depend on whether AMC Entertainment Holdings' present share price looks aligned with its sales when judged against the Fair Ratio benchmark.
If you want to benchmark AMC Entertainment Holdings against other businesses where price is weighed directly against sales, take a look at 26 high quality undervalued stocks.
Is AMC Entertainment Holdings Still Cheap on Sales?
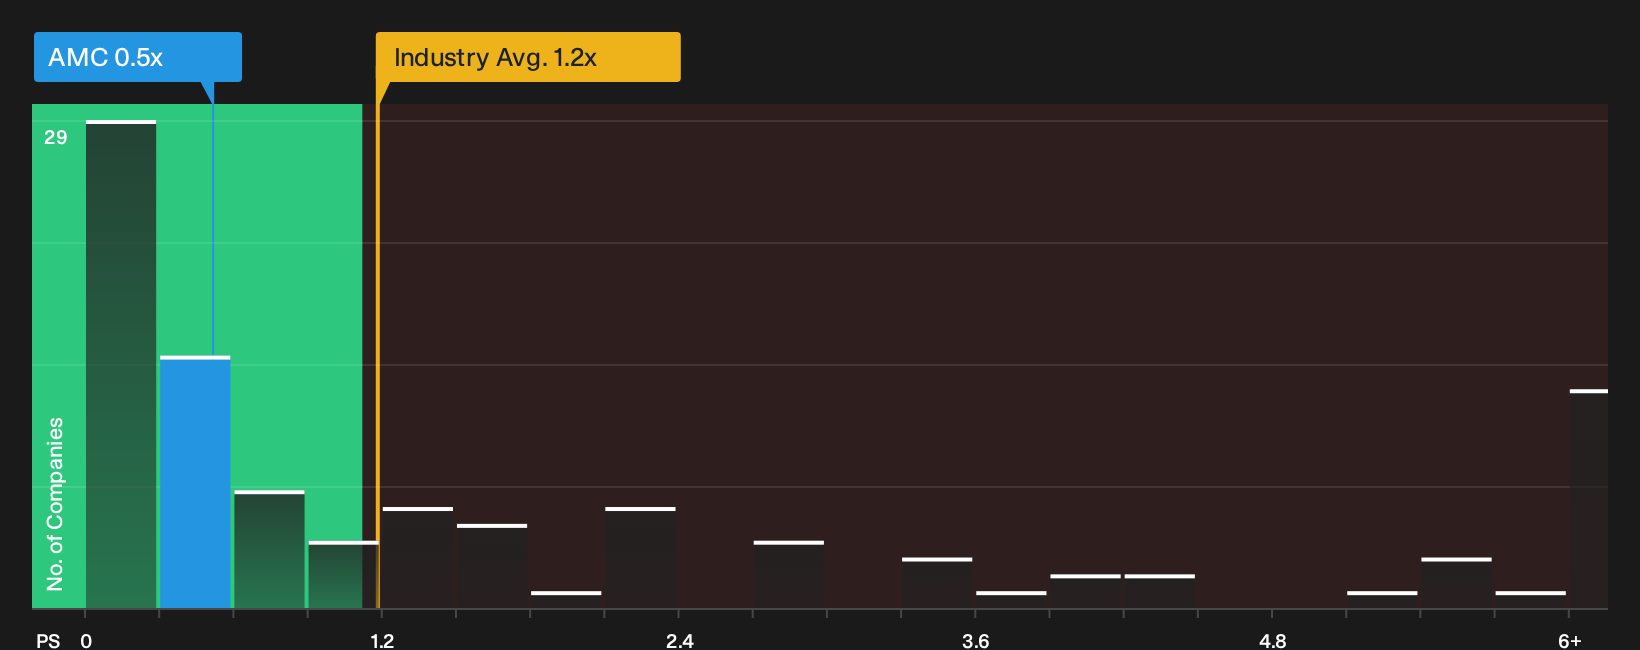
P/S works well for AMC Entertainment Holdings because investors are essentially paying for ticket and concession turnover rather than current earnings. At the moment the stock trades on a P/S of 0.5x, which is below both the wider entertainment industry average of 1.2x and the peer group on 3.9x. As a result, the market is attaching a relatively low price tag to each dollar of AMC’s revenue.
The Fair Ratio, which adjusts the P/S benchmark for AMC’s own scale, margins and risk profile, indicates that this 0.5x level is below where the multiple might typically sit for a business with these characteristics. For you as a shareholder or potential buyer, the key question is whether AMC Entertainment Holdings can sustain and monetise its sales base strongly enough for that gap to matter over time, or whether the discount simply reflects ongoing uncertainty around the cinema model. Explore the numbers behind AMC Entertainment Holdings's P/S valuation.
The AMC Entertainment Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AMC Entertainment Holdings link the current valuation question to explicit scenarios for the company’s revenue, margins and earnings that would need to play out for the stock to be worth materially more or less than today’s price. Each narrative lays out the assumptions behind its fair value so you can compare them with AMC Entertainment Holdings' actual results as they are reported. Narratives sit on Simply Wall St’s Community page and give you a structured way to test your own expectations against those scenarios.
Community narratives around AMC Entertainment Holdings split between a cleaner balance sheet helping the turnaround and heavy debt plus fee and content risks capping the upside.
Bull case: 11% undervalued
"Significant deleveraging progress, extension of debt maturities, and tight cost controls have improved AMC's balance sheet and freed up cash for reinvestment in high-return growth initiatives..."
Discover why this Narrative puts AMC Entertainment Holdings at 11% undervalued.
Bear case: 36% overvalued
"Despite extensive refinancing and interest savings with maturities pushed out to 2031 and 2033, AMC still carries high leverage..."
Explore why this Narrative puts AMC Entertainment Holdings at 36% overvalued.
AMC Entertainment Holdings: why the story is not just about the share price
Valuation only shows part of what you are weighing with AMC Entertainment Holdings, because our research has also highlighted specific checks that raise concerns investors may want to review closely. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com