


Oil prices just swung sharply again, with WTI crude snapping back after a 3% jump and fresh headlines out of the Middle East reminding investors how quickly supply risk can flare up. That kind of whiplash can punish some stocks and open the door for others. This piece walks through three global integrated oil and gas majors that are particularly exposed to this news flow, and why their different business mixes may matter for your portfolio.
The stocks highlighted below are only a sample. The full screen surfaces 12 more large integrated groups with equally compelling narratives that are not covered here. To identify and analyze the highest conviction global majors that fit your own risk profile, head straight into the Global Integrated Oil & Gas Majors screener.
Cavvy Energy (TSX:CVVY)
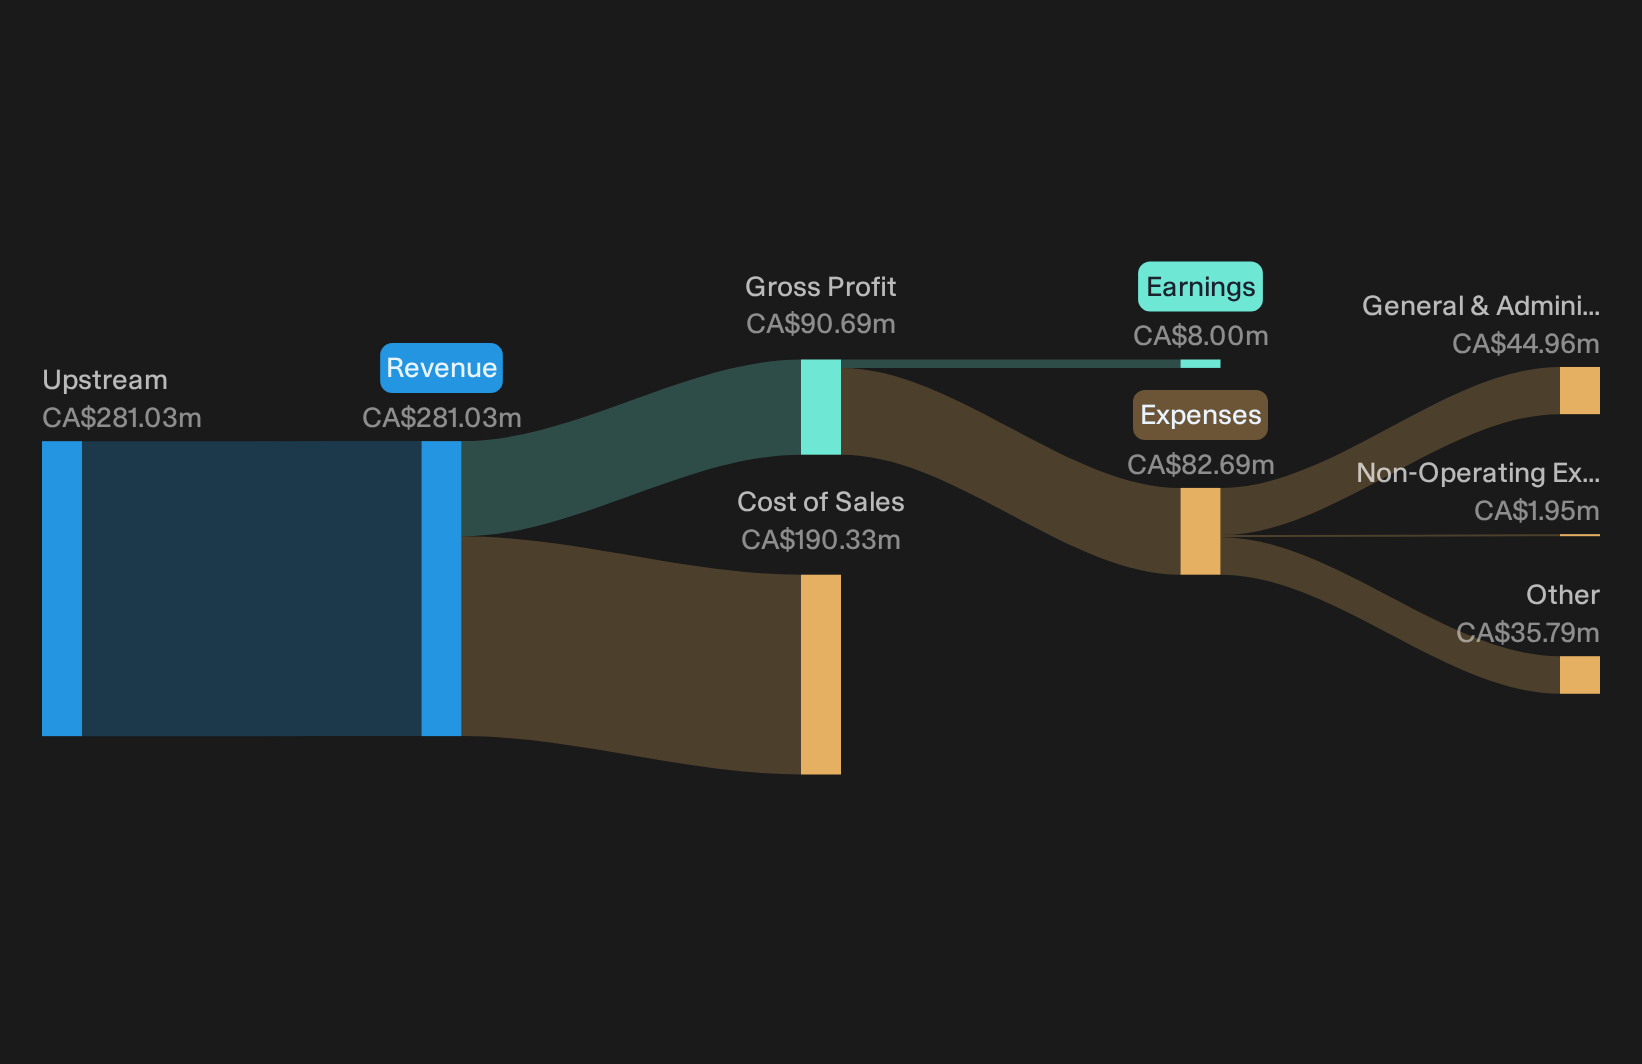
Overview: Cavvy Energy is a Canadian producer and processor of natural gas and related products, combining upstream wells with midstream sour gas plants in Western Canada.
Operations: Cavvy Energy generates all its CA$281 million revenue from upstream activities in Canada, centered on its Alberta and northeast British Columbia assets.
Market Cap: CA$792 million
Cavvy Energy fits this integrated energy screen through its blend of producing wells and processing hubs, which puts its sour gas and sulfur exposure firmly in focus when commodity headlines start to move.
"The 2026 sulfur pricing agreement, which replaces the long running CAD 6 per metric ton contract, is expected to lift realized pricing materially above historical contractual levels. High capacity sour gas processing hubs, described as industrial centers with room for new energy related uses and active discussions in power and AI data centers, offer optionality for incremental fee based revenue streams that may smooth earnings through commodity cycles."
What happens if a single assumption about future demand around those industrial hubs shifts even modestly could matter a great deal for Cavvy.
That kind of shift risk cuts both ways, and Cavvy Energy’s optionality is exactly what the full narrative for Cavvy Energy unpacks, including scenarios the sulfur contract only hints at.
Japan Petroleum Exploration (TSE:1662)
Overview: Japan Petroleum Exploration develops and produces oil and gas across Japan and overseas, while supplying domestic gas and LNG infrastructure.
Operations: Japan Petroleum Exploration generated ¥235.4b revenue in Japan, ¥51.7b in North America, and ¥30.9b in the Middle East, with minimal European contribution.
Market Cap: ¥445.2b
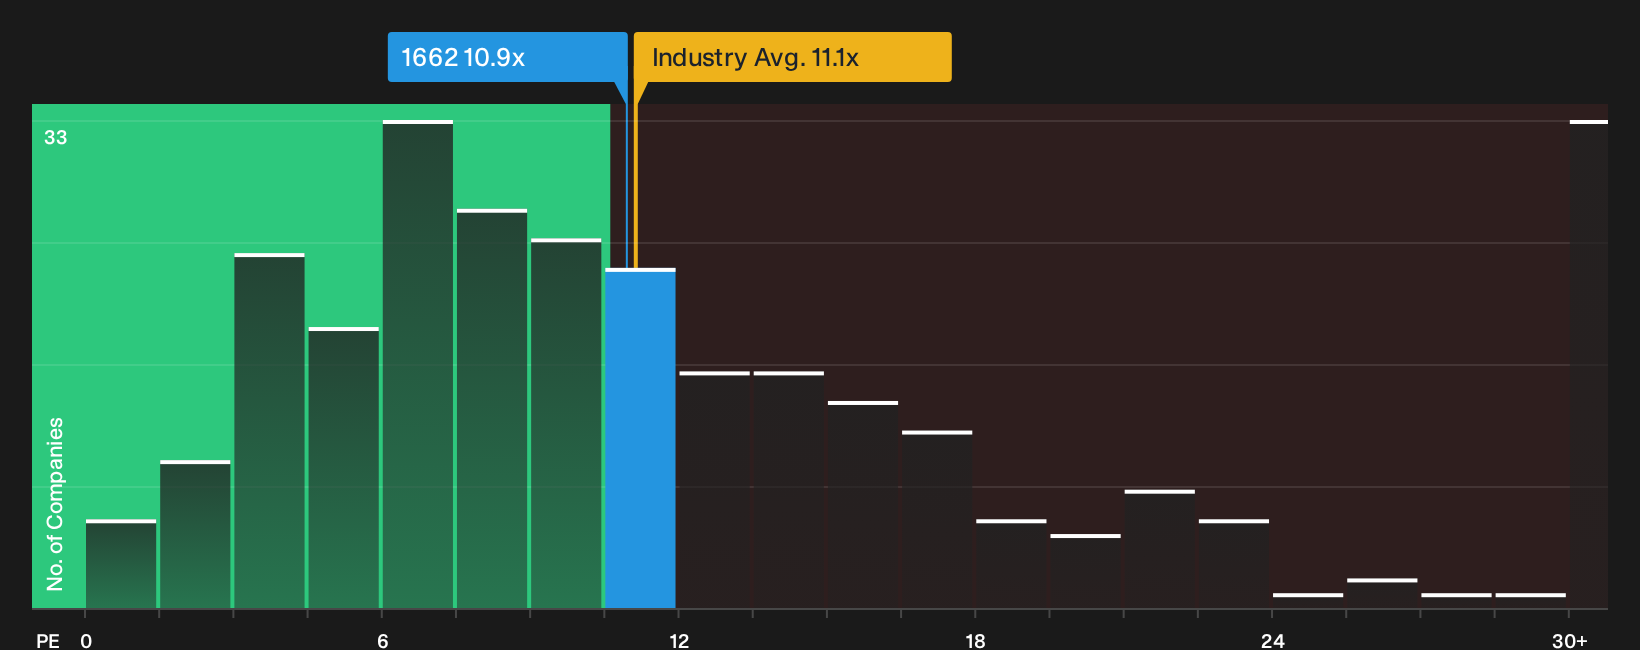
Japan Petroleum Exploration provides exposure to an upstream-weighted oil and gas producer that is integrated into Japan’s gas and LNG system, with meaningful Middle East exposure that is directly connected to the current reassessment of supply risk. The stock trades on a modest P/E with mixed earnings momentum, so any change in how investors price that regional exposure could affect the valuation gap and future margin views.
That valuation gap is the real story, and the 2 key rewards and 2 important warning signs highlights where Japan Petroleum Exploration could be mispriced as sentiment shifts around supply risk.
California Resources (CRC)
Overview: California Resources produces oil and gas in California while building a carbon management and power platform tied to local energy security.
Operations: California Resources generated US$3.41b from Oil and Natural Gas, with total US revenue of US$3.74b after a US$211 million segment adjustment.
Market Cap: US$4.81b
California Resources offers pure play exposure to California crude within a majors-style screener. Its integrated carbon and power assets give it a somewhat different profile compared with global refining giants.
"Recent and potential regulatory reforms in California aimed at improving oil and gas permitting and supporting local energy security may provide California Resources with increased operational flexibility and access to its extensive project inventory, which could support higher production levels and revenue growth."
Even a modest change in assumptions regarding future California policy support could have a meaningful impact on margins and cash flow.
If that policy mix is what catches your eye, the full narrative for California Resources outlines how California Resources’ permitting, carbon projects and cash generation stories could be decoupling from headline oil sentiment.

Curious About What You Might Be Missing?
Fresh ideas often appear before they are widely discussed. By the time momentum headlines arrive, early entries may have already moved. Review these under the radar lists before the broader market focuses on them and decide whether they fit your strategy.
- Identify strong balance sheets before they become widely recognized and track potential breakout candidates using the curated list of solid balance sheet and fundamentals (6 results).
- Explore resilient income opportunities while yields remain attractive by using the hand picked 3 dividend fortresses.
- Find early growth stories in a fast changing sector by reviewing the focused 6 healthcare AI stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com