


The Morning Bull - US Market Morning Update Thursday, Oct, 29 2026
US stocks look set for a softer open, with sentiment tilted cautious as inflation takes center stage again. The focus is squarely on September PCE data, the Federal Reserve’s preferred gauge, which is expected to show firmer price pressure.
Economists see the PCE price index at +0.5% month on month, with core PCE at +0.3%. On a yearly basis, headline PCE is projected at 3.6% and core at 3.1%. These readings matter because they directly inform how restrictive Fed policy may need to be.
Hotter PCE readings tend to keep Treasury yields elevated, which raises borrowing costs for households and companies. Higher discount rates can weigh on equity valuations and squeeze interest rate sensitive areas of the market that rely heavily on cheap funding.
The open question is whether inflation pressure coexists with still firm growth. Today’s advance Q3 GDP report is expected at 3.2% annualized, and the outcome could lead investors to reassess how long the Fed can maintain current rate levels.
Stocks to Watch Before the Opening Bell
Okta (OKTA)
A hacker group claims to have leaked records on more than 40,000 U.S. Department of Homeland Security employees through an Okta single sign on system. Details reportedly include work locations, system permissions, and undercover roles. Investors are watching how Okta communicates about whether its own infrastructure was affected and how federal customers respond to the incident.
Visa (V)
Visa just signed an expanded agreement with Tencent after securing approval from the People’s Bank of China to prepare a domestic bank card clearing business. The move deepens cooperation on cross border payments, AI powered commerce, and money transfers into Weixin Pay. Attention now turns to how quickly Visa builds transaction volume inside China’s tightly regulated payments market.
Coinbase Global (COIN)
Coinbase Global sits at the center of two crypto storylines today. A Bitcoin whale sent 438.37 BTC, about US$35 million, to Coinbase Prime at a reported US$15 million paper loss, which traders see as potential supply. Ripple’s RLUSD stablecoin also went live across Coinbase venues under a new national trust bank charter, expanding regulated dollar based liquidity on the platform.
Top Movers
Vertiv Holdings Co (VRT) jumped 16.48% after Q3 results beat expectations and full year 2026 guidance was raised sharply.
Flex (FLEX) surged 11.61% on strong Q2 results, higher full year guidance, and progress on its Axiom spin off.
Oracle (ORCL) rallied 10.73% after Investor Day targets highlighted large 2030 revenue ambitions and sizeable future free cash flow.

Top Losers
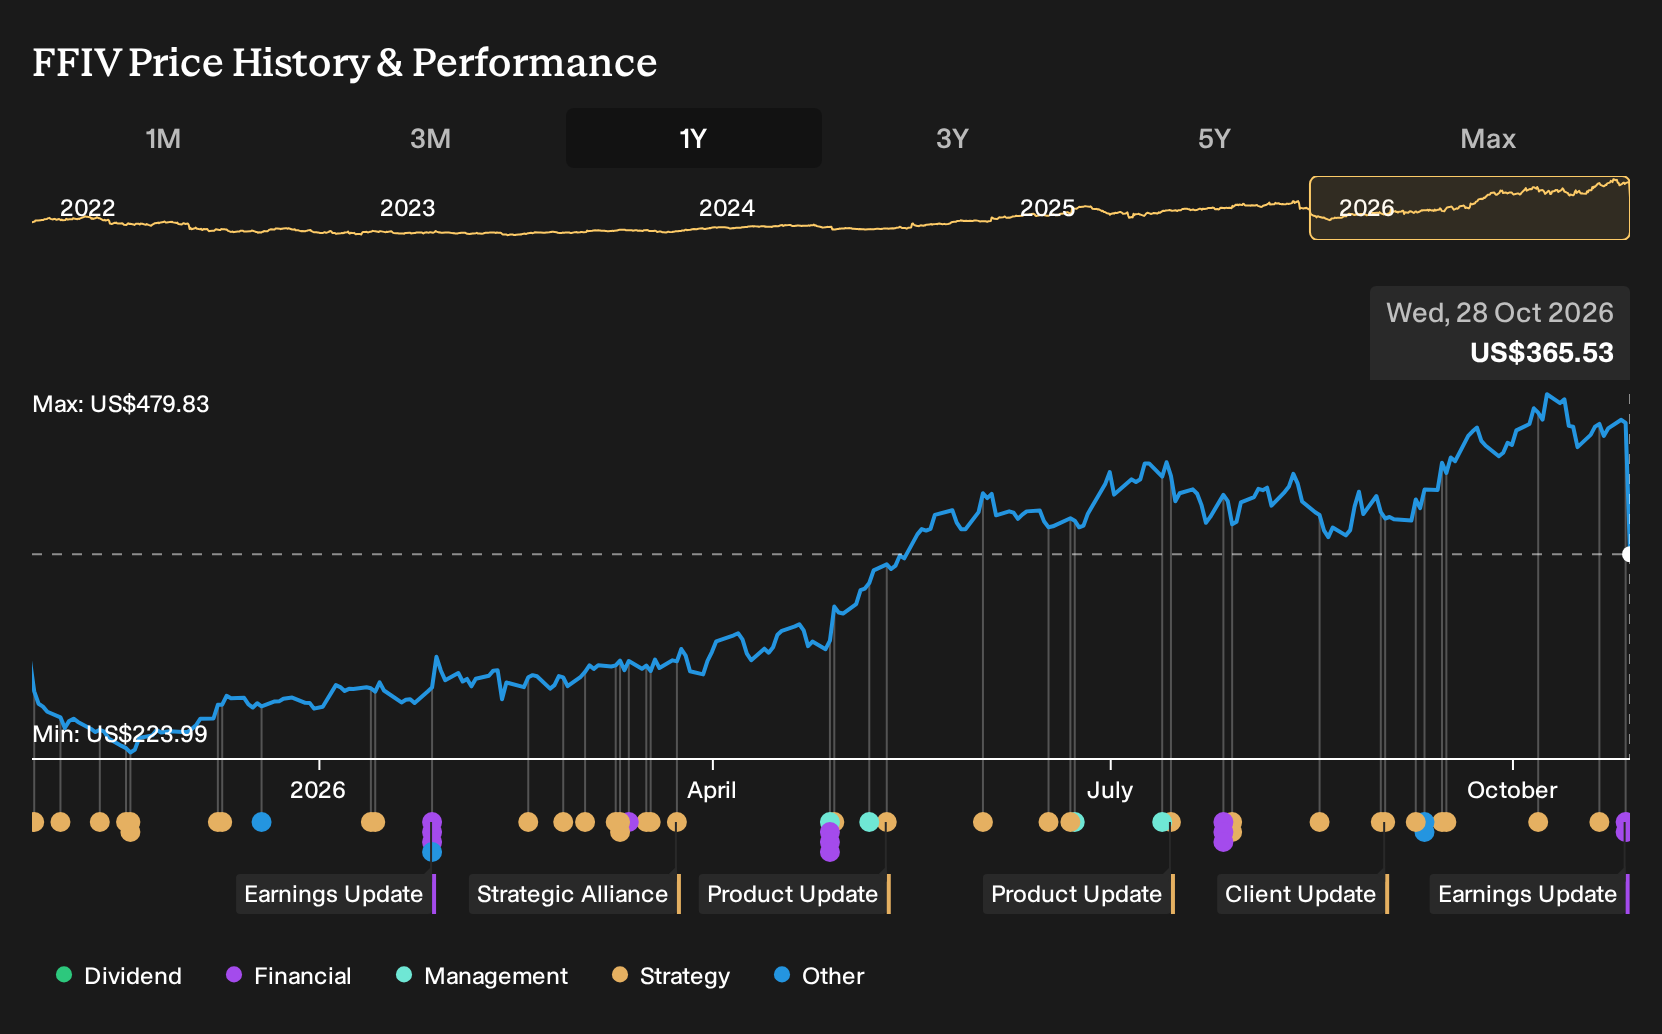
F5 (FFIV) fell 20.43% after investors reacted to weaker fiscal 2027 guidance and a valuation-driven downgrade.
LPL Financial Holdings (LPLA) declined 15.23% after strong Q3 results, while reduced Commonwealth asset retention guidance pressured sentiment.
Baker Hughes (BKR) fell 7.36% as analysts cut price targets despite Q3 earnings and order intake beating expectations.
On The Radar
US macro data and a heavy slate of large cap earnings are lining up to test how comfortable investors really are with current growth and inflation readings.
- US Core PCE Price Index MoM, Thu 29 Oct. The core reading is forecast at 0.3% versus a previous 0.2%. A result above that would pressure Fed rate cut hopes and keep borrowing costs and the US dollar firm.
- US GDP Growth Rate QoQ Adv, Thu 29 Oct. Consensus sits at 3.2% after 2.2% previously. A softer figure would raise questions about how long the economy can absorb higher policy rates without denting corporate revenue expectations.
- US Employment Cost Index QoQ, Fri 30 Oct. Total compensation is forecast around 0.8% after 0.9%. A stronger print would underline wage pressure that feeds into inflation and margin risk for labor heavy sectors like retail and hospitality.
- US ISM Manufacturing PMI, Mon 2 Nov. Forecast near 54.7 after 54.5. A reading above that range would back the idea that factory activity remains solid, supporting sentiment around industrials and capital goods stocks.
- Apple, Fri 30 Oct. Q4 2026 results will put the spotlight on hardware revenue and any commentary on device demand, which matters for how investors think about broader consumer electronics spending.
Sector & Industry Watch
Energy: Fuel producers still on the front foot
Energy has edged higher over the past week, with the 7 day return a little above 1%, adding to already strong 30 day and 1 year numbers. News from Cactus, Phillips 66, Marathon Petroleum, Weatherford and Prairie Operating highlights active drilling, refining and LNG related projects alongside dividends and buybacks.
If you hold energy ETFs or individual producers, today’s US PCE inflation and GDP data matter because any sign that fuel costs are feeding into broader prices can influence how comfortable investors are with the sector’s cash generation at current demand levels.
Real Estate: Data centers and rent checks vs higher rates
Real Estate has been close to flat over the last week, with slightly positive 30 day and year to date returns and a small 1 year gain. Earnings and deals from Equinix, VICI Properties, EPR Properties, Urban Edge, Broadstone Net Lease, Gaming and Leisure Properties and others show steady interest in data centers, logistics, gaming and net lease income.
If REITs are part of your income sleeve, keep an eye on today’s GDP and PCE releases because the mix of rental growth and borrowing costs is what ultimately drives dividends, especially for owners funding data center and experiential projects with significant debt.
Tech: AI spend supports sector resilience
Tech has picked up over the past 7 days, with the sector’s weekly gain near 2% and 1 year and year to date returns still well ahead of the US Market. Oracle’s long term revenue targets, Microsoft’s OpenAI related cloud revenue, Flex’s cloud spin plans and a long list of cybersecurity and software results all point to real AI and cloud contracts, while headlines around Okta, Super Micro and big cap regulation keep risk in the picture.
If you are heavily exposed to large US software, hardware or cloud stocks, today’s PCE and GDP bundle is important because hotter inflation paired with solid growth keeps the focus on how easily companies can fund big AI and data center builds when interest rates remain elevated.
Semiconductors: Chipmakers rebound as AI orders stay firm
Semiconductors have rebounded over the past week, with a roughly 2.8% 7 day move after a weaker 30 day patch, and still show strong year to date and 1 year gains versus the broader market. Earnings and updates from KLA, FormFactor, Micron related news, Nvidia, Wolfspeed, Cohu, ACM Research and others underline ongoing AI, memory and equipment demand even as funding costs and regulatory reviews sit in the background.
If chip ETFs or GPU exposed stocks are a big part of your portfolio, treat today’s Core PCE inflation print and Q3 GDP report as a funding check, since capital hungry fabs and AI server projects depend on both solid end demand and borrowing costs that do not eat into expected returns.
Consumer Discretionary & Automobiles: Spending patchy, autos see a sharp bounce
Consumer Discretionary is slightly softer over 7 days despite a strong 30 day run, while Automobiles show a sizeable 7 day gain of just over 7% on top of weaker 1 year and year to date returns. Company news ranges from Wendy’s take private bid, Chipotle and Cheesecake Factory growth, to Tesla, Ford, Dana, LCI Industries and Patrick Industries deal activity, painting a mixed picture for restaurants, retailers and car makers.
If you own retailers, restaurants or auto stocks, today’s US PCE and Personal Spending data give a clean read on whether households are still willing to pay for eating out, travel and vehicles, or starting to trim discretionary purchases after a long stretch of higher prices and borrowing costs.
How To Find Stocks That Fit Your Strategy
If high borrowing costs are your main concern after today’s PCE and GDP focus, start with this list of 32 resilient stocks with low risk scores that aim to keep overall portfolio risk in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com