


Air Canada has climbed 31.4% over the past three years, yet recent share price weakness and fresh regulatory headlines are pushing investors to reassess whether today's valuation lines up with its earnings power. With the stock at $21.82 after a softer past month, the core issue is how much of its current and future profit stream is already reflected in that price.
- The 31.4% gain over three years puts real weight on the question of whether Air Canada's earnings profile can support that kind of compounding return over time.
- Regulatory scrutiny of the expanded arrangement with United Airlines, together with new route and partnership plans, can influence future traffic mix, pricing power, and ultimately the earnings base that underpins the stock.
- Your read on Air Canada is one view; the desks covering it have another. See what analysts think Air Canada's shares could be worth.
The issue now is whether Air Canada's current share price is justified by the earnings it generates today and what investors reasonably expect it to produce over the coming years.
To stress test whether Air Canada's recent 31.4% three year gain and current earnings story stack up, it can help to line it up against other 4 high quality undervalued stocks.
Is Air Canada a Bargain on Earnings?
P/E fits Air Canada because earnings now drive more of the story than asset values or headline revenue.
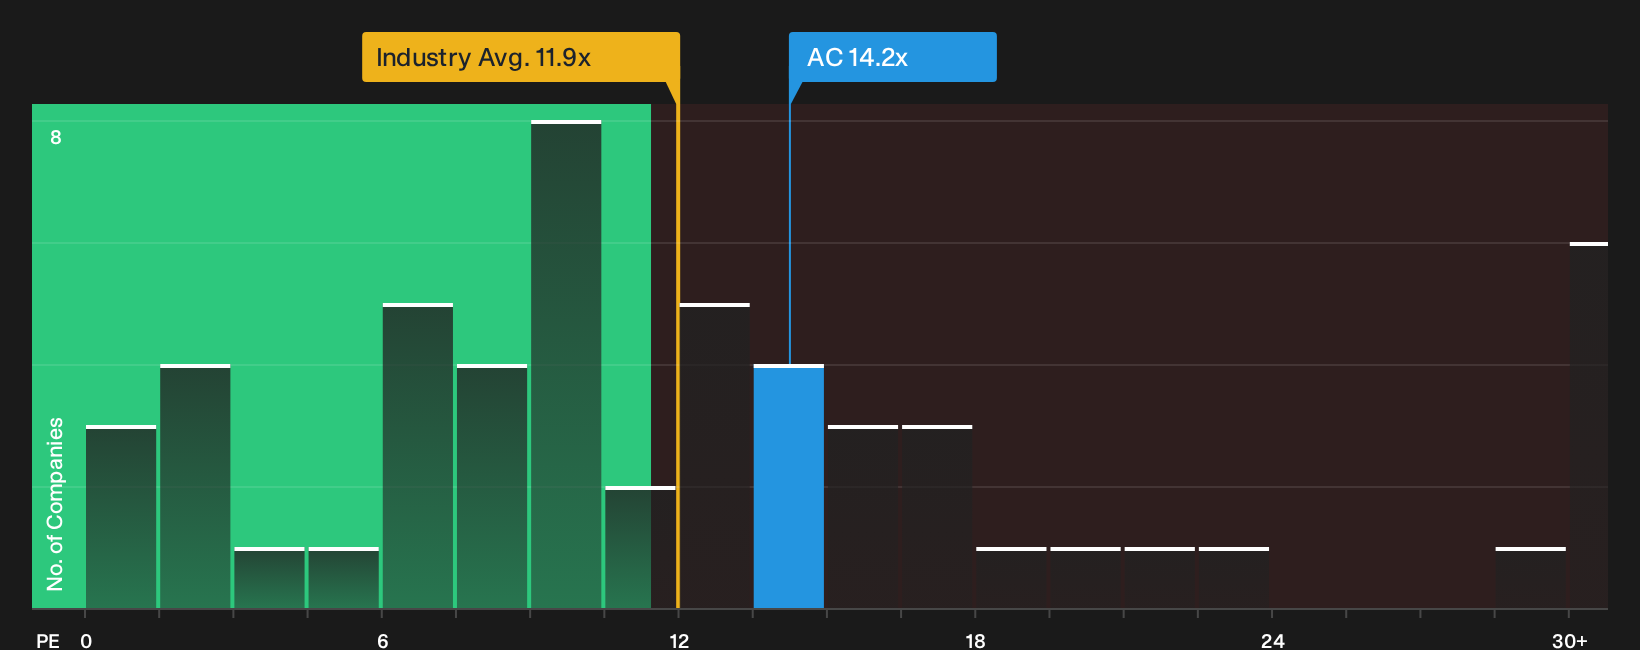
On this lens, the stock trades at about 14.2x earnings. That level sits below the broader Airlines industry average of roughly 11.9x but even further below the peer group closer to 24.4x, so investors are paying less than some comparable carriers but not the lowest multiple in the sector. The fair P/E that lines up with Air Canada's growth profile, profitability, size and risk is higher than where the shares change hands today. This suggests the market is applying a discount to its earnings stream.
Because the Competition Bureau has raised concerns about the expanded United Airlines partnership, part of that discount may reflect uncertainty over how any final ruling affects future route economics and pricing power. For a reader weighing the stock, the key question is whether those risks justify Air Canada trading below the P/E level implied by its fundamentals. Explore the numbers behind Air Canada's P/E valuation.
The Air Canada Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Air Canada valuation puzzle leaves off by explaining which paths for growth, margins and earnings would need to occur for the stock to be worth meaningfully more or meaningfully less than today's price. Each one links its number to a concrete view on how Air Canada's growth, profitability and risks might change over time, giving you something specific to compare against as new information on the business becomes available.
One of the top community narratives on Air Canada: 34% undervalued
"Analysts expect Air Canada to keep benefiting from structurally higher premium and corporate demand, an expanding international and Sixth Freedom network…"
Discover why this Narrative puts Air Canada at 34% undervalued.
One more Air Canada angle that could change how you see the stock
Valuation checks tell you what investors are paying today, but the projections that analysts build for Air Canada over the next few years offer a different lens on what might be baked in or missing. Explore where analysts expect Air Canada to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com