


Satellite radio and media company Sirius XM (NASDAQ:SIRI) met Wall Street’s revenue expectations in Q3 2026, but revenue was flat year on year at $2.15 billion. On the other hand, the company’s full-year revenue guidance of $8.55 billion at the midpoint came in 0.5% below analysts’ consensus estimates. Its GAAP profit of $0.78 per share was in line with analysts’ consensus estimates.
For more on Sirius XM, read our free full research report.
Sirius XM (SIRI) Q3 2026 highlights:
- Revenue $2.15 billion vs S&P analysts’ consensus estimates of $2.16 billion (flat year on year, in line)
- EPS (GAAP) $0.78 vs analysts’ consensus estimates of $0.79 (in line)
- Adjusted EBITDA $694 million vs analysts’ consensus estimates of $664.8 million (32.2% margin, 4.4% beat)
- EBITDA guidance $2.65 billion at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 22.2%, in line with the same quarter last year
- Free cash flow margin 13.6%, up from 11.9% in the same quarter last year
- Subscribers 38.37 million, in line with the same quarter last year
- Market capitalization $9.21 billion
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Sirius XM struggled to consistently increase demand as its trailing 12-month revenue of $8.60 billion was close to its revenue five years ago. This fell short of our standards and points to poor business quality.
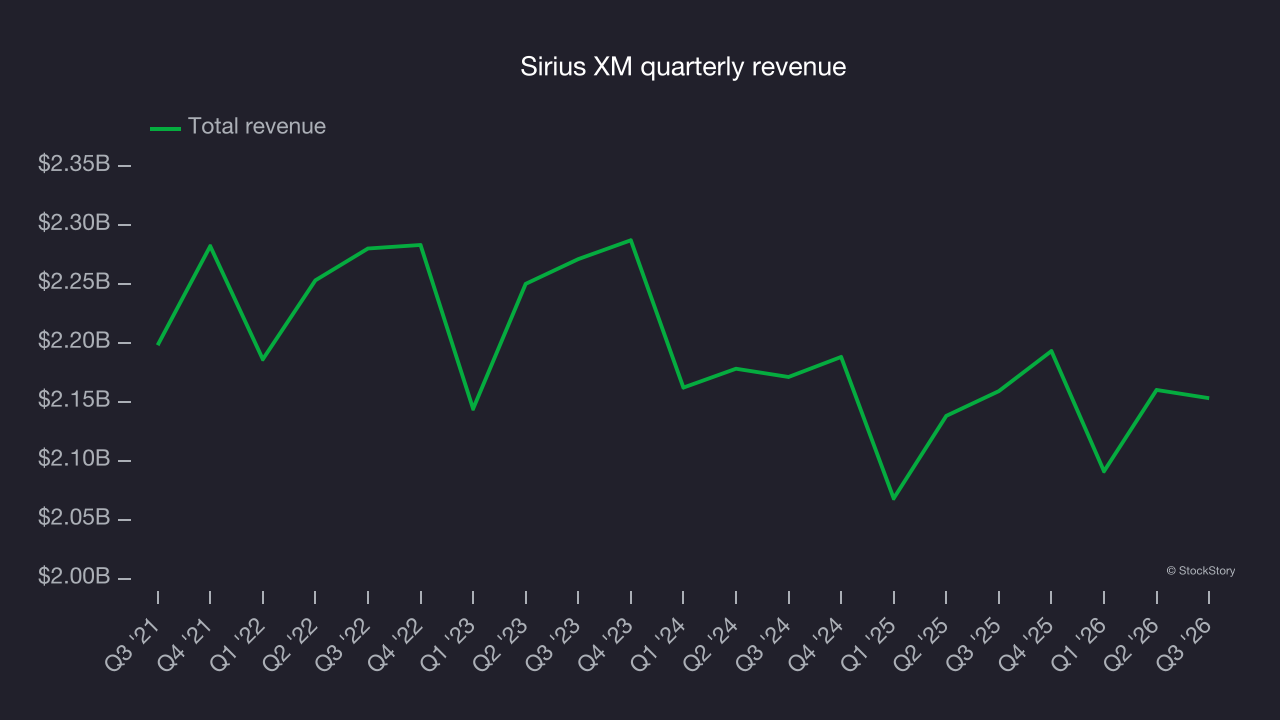
Long-term growth matters most, but within consumer discretionary, a longer historical view may miss a company riding a successful new product or trend. Sirius XM’s recent performance shows its demand remained suppressed as its revenue has declined by 1.1% annually over the last two years. 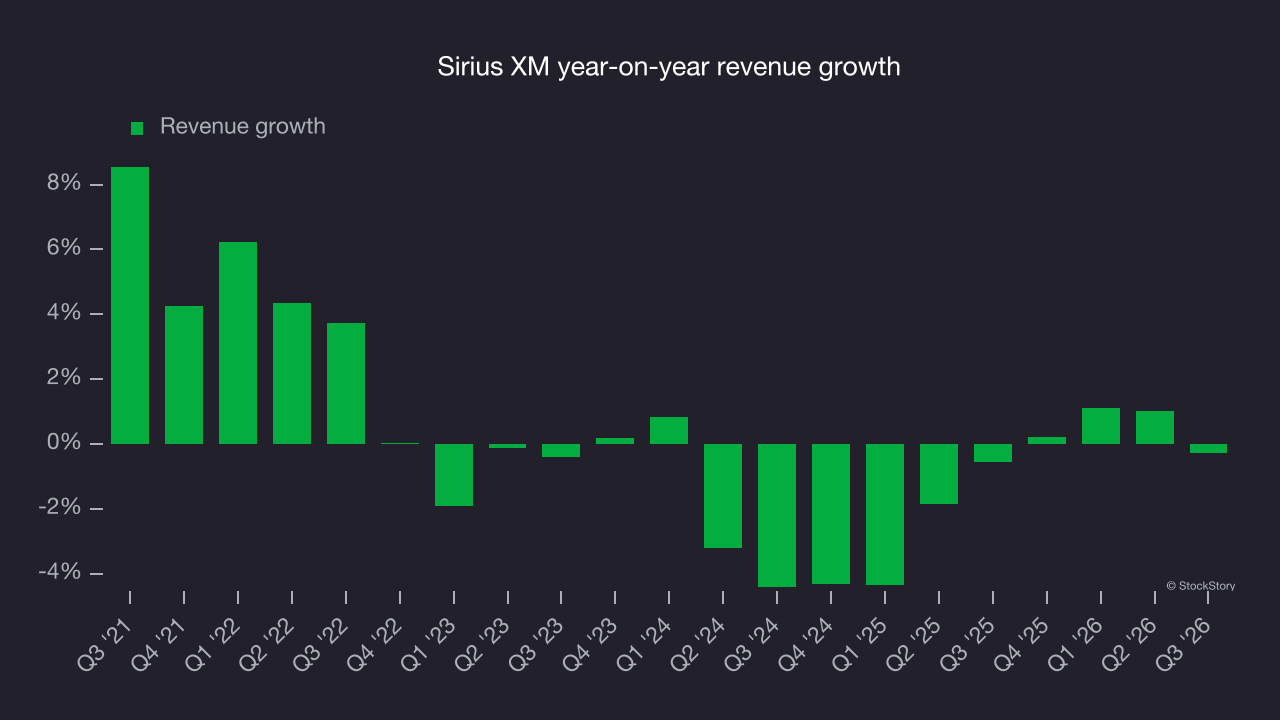
This quarter, Sirius XM’s $2.15 billion of revenue was flat year on year and in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. Although this projection implies its newer products and services will fuel better top-line performance, it is still below the sector average.
Operating margin
Sirius XM’s operating margin has been trending down over the last 12 months and averaged 19.7% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses onto its customers.
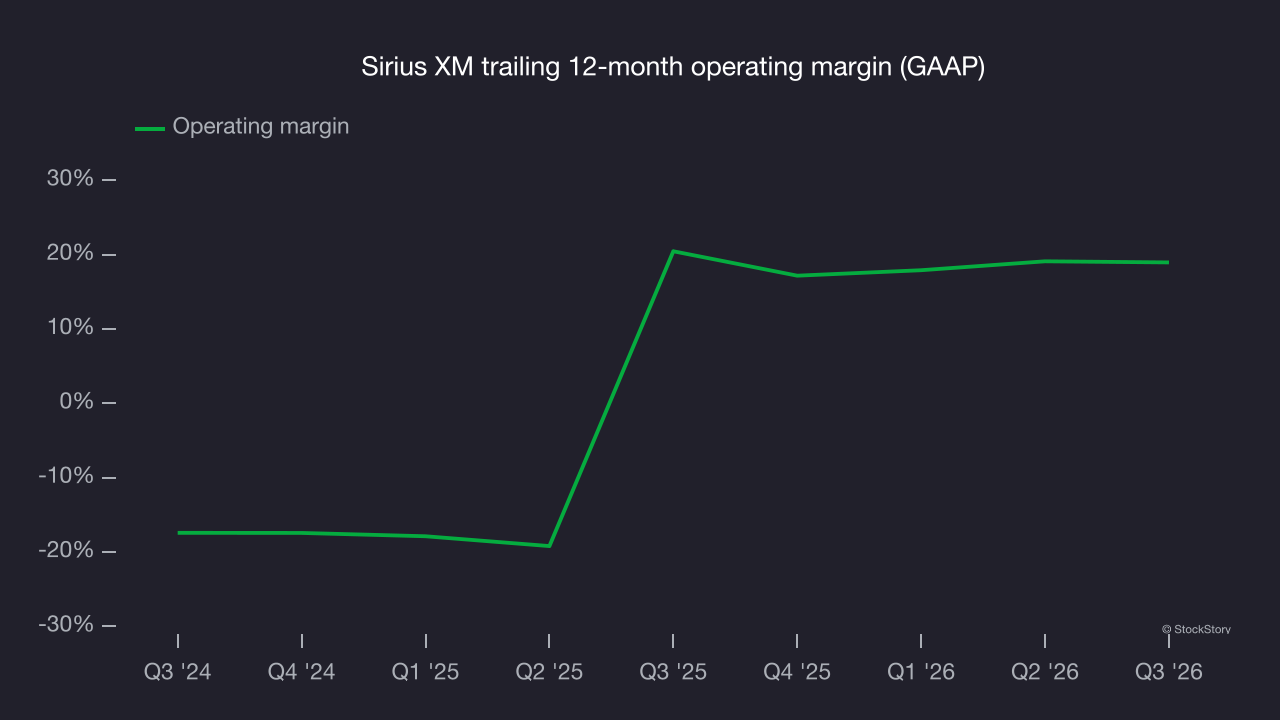
In Q3, Sirius XM generated an operating margin of 22.2%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Sirius XM’s EPS grew at a 24.6% compounded annual growth rate over the last five years. This performance was better than its flat revenue but doesn’t tell us much about its business quality because its operating margin didn’t improve.
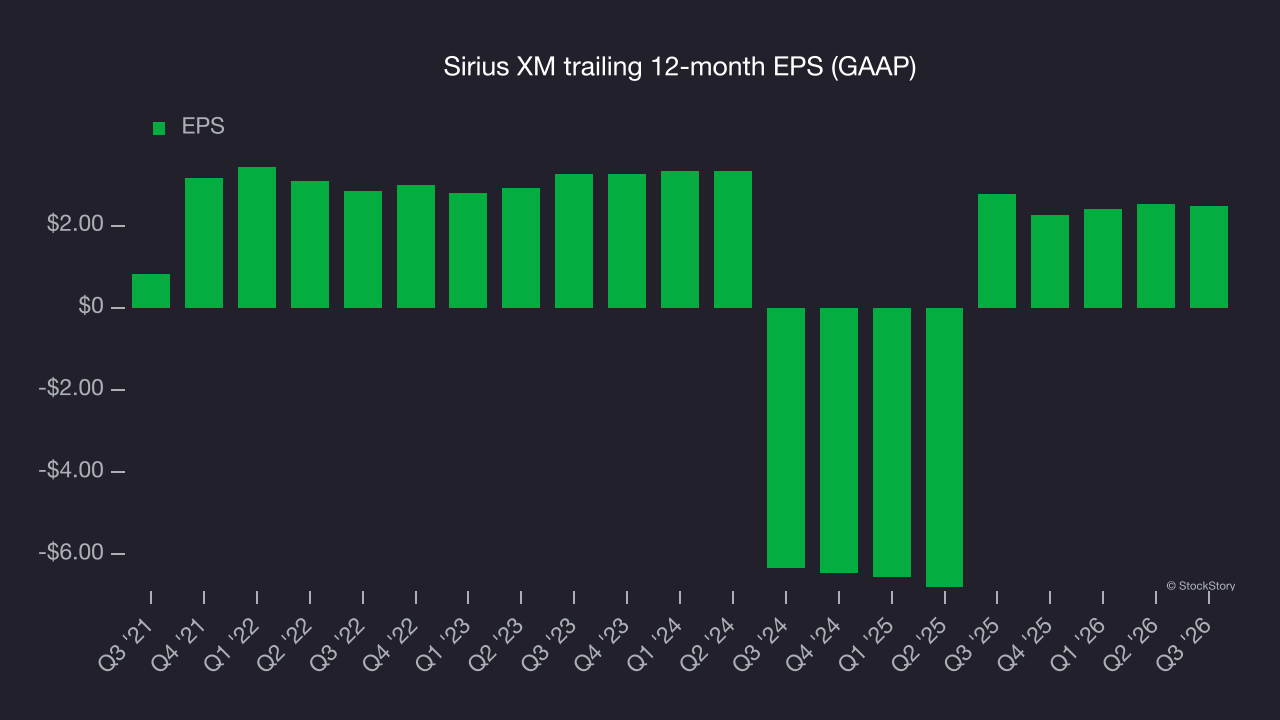
In Q3, Sirius XM reported EPS of $0.78, down from $0.83 in the same quarter last year. This result was close to analysts’ consensus estimates. Over the next 12 months, Wall Street expects Sirius XM’s full-year EPS to grow 28.9% from $2.48 to $3.20, according to S&P.
Key takeaways from Sirius XM’s Q3 results
Sirius XM’s EBITDA beat analysts’ consensus estimates, but a slight miss in its full-year revenue guidance left this looking like a weaker quarter overall. Shares edged lower 1.1% to $27.01 immediately after the results.
When deciding whether to invest in this stock, the latest quarter matters, but not as much as longer-term business quality and valuation. For more on that, read our full research report here (it’s free).