


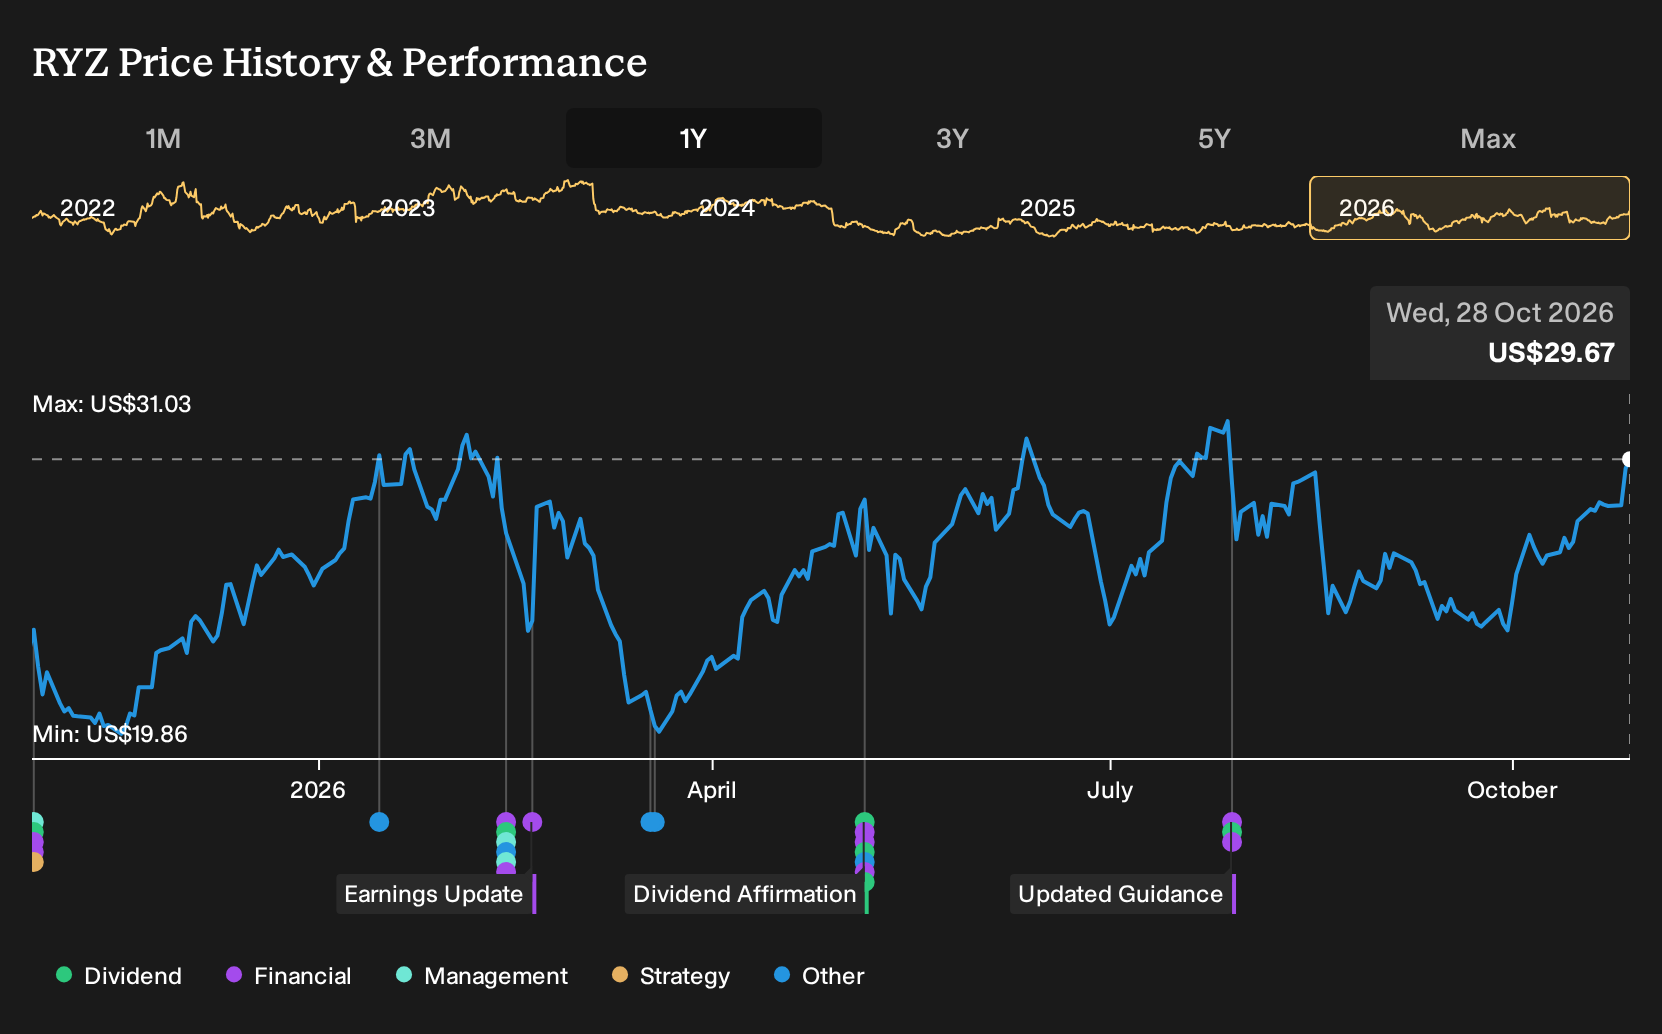
- Ryerson Holding reported third quarter 2026 results with US$2,177.8 million in sales and US$32 million in net income, issued fourth quarter guidance for US$1.96 billion to US$2.04 billion in net sales and US$16 million to US$20 million in net income, and affirmed a US$0.1875 quarterly dividend declared on 28 October 2026.
- Management paired the profit turnaround with explicit fourth quarter earnings targets and a maintained cash payout. Together, these factors highlight how Ryerson Holding is balancing reinvestment needs with returning capital to shareholders.
- Next, the focus shifts to how Ryerson Holding's new fourth quarter earnings guidance could shape the investment narrative that investors use to assess it.
Compare Ryerson Holding's latest guidance and dividend stance with other potential opportunities by scanning our hand picked 26 high quality undervalued stocks that pair earnings power with balance sheet strength.
What Is Ryerson Holding's Investment Narrative?
To own Ryerson Holding, you need to be comfortable with a metals service center that lives and dies by execution, pricing discipline, and capital demands in a heavy industrial supply chain. The recent swing back to a US$32 million quarterly profit and the new fourth quarter guidance put the focus on whether this level of earnings generation can support both reinvestment and shareholder payouts. Management is signalling confidence by pairing explicit net income targets of US$16 million to US$20 million with a maintained dividend of US$0.1875 per share.
In the short term, the key questions are simple. Does underlying demand and pricing hold up well enough for Ryerson Holding to stay profitable while carrying interest costs that are not well covered by earnings, and while paying a dividend that recent analysis flagged as not well supported by earnings or free cash flow? The guidance and dividend affirmation ease concern on the income line for now, yet they also raise the bar for execution in a business that still looks capital intensive and sensitive to volume mix and service margins.
Yet there is a lingering issue around the way Ryerson Holding funds itself that could become far more important if ...
There's only one way to know the right time to buy, sell or hold Ryerson Holding. Head to Simply Wall St's company report for the latest analysis of Ryerson Holding's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight US$29 to roughly US$40 band, which shows how even a small group of retail views on Ryerson Holding can spread out. Those opinions pre date the fresh earnings, guidance and dividend news, so treat them as one input, and compare several other viewpoints before deciding how the story fits your own expectations.
Explore another Ryerson Holding fair value estimate, including one that suggests as much as 35% upside from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ryerson Holding research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Ryerson Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ryerson Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ryerson Holding?
Once you have a view on Ryerson Holding, it often helps to compare it with other companies that share similar qualities or offer a different risk and return profile.
- If you want potential mispriced opportunities with solid fundamentals, start with a curated 19 high quality undiscovered gems that may not yet be widely followed.
- For investors who prefer financial resilience over excitement, filter for a 32 resilient stocks with low risk scores that scores well on balance sheet strength and earnings consistency.
- If reliable finances matter most to you, scan a list of solid balance sheet and fundamentals (24 results) to find businesses backed by sturdier capital structures.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com