


Healthcare company Baxter International (NYSE:BAX) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 5% year on year to $2.98 billion. Its non-GAAP profit of $0.58 per share was 11.9% above analysts’ consensus estimates.
For more on Baxter, read our free full research report.
Baxter (BAX) Q3 2026 highlights:
- Revenue $2.98 billion vs S&P analysts’ consensus estimates of $2.91 billion (5% year-on-year growth, 2.3% beat)
- Adjusted EPS $0.58 vs S&P analysts’ consensus estimates of $0.52 (11.9% beat)
- Adjusted operating income $432 million vs analysts’ consensus estimates of $402.9 million (14.5% margin, 7.2% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $2.10 at the midpoint, a 2.4% increase
- Operating margin 7.6%, up from 6.1% in the same quarter last year
- Free cash flow margin 15.1%, up from 4.4% in the same quarter last year
- Constant currency revenue rose 5% year on year (2% in the same quarter last year)
- Market capitalization $13.16 billion
“We delivered a strong third quarter, with growth across all segments and divisions globally,” said Andrew Hider, president and CEO. “We continue to make steady progress stabilizing the business, strengthening the balance sheet and driving continuous improvement. Our results reinforce our confidence in this direction as we build a stronger foundation for sustainable growth and long-term value creation.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. Baxter struggled to consistently generate demand over the last five years as its revenue dropped at a 1.4% annual rate. This was below our standards and suggests it’s a lower-quality business.
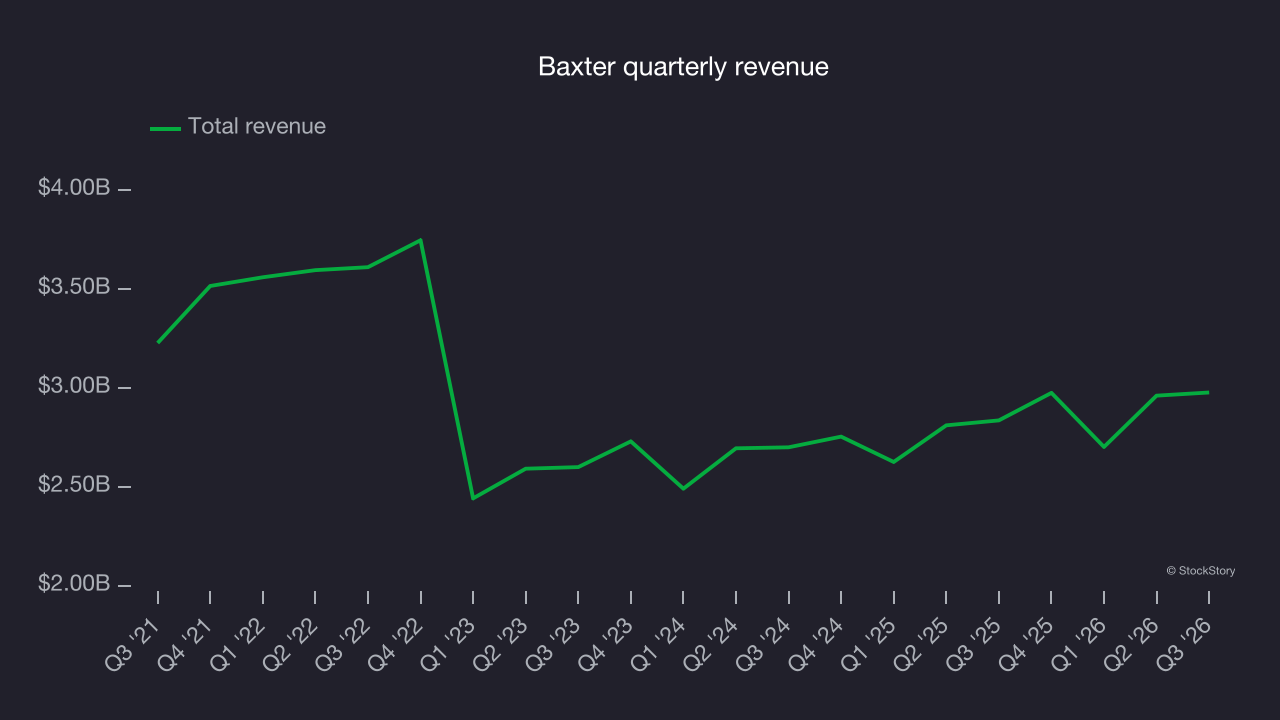
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. Baxter’s annualized revenue growth of 4.6% over the last two years is above its five-year trend, which is encouraging. 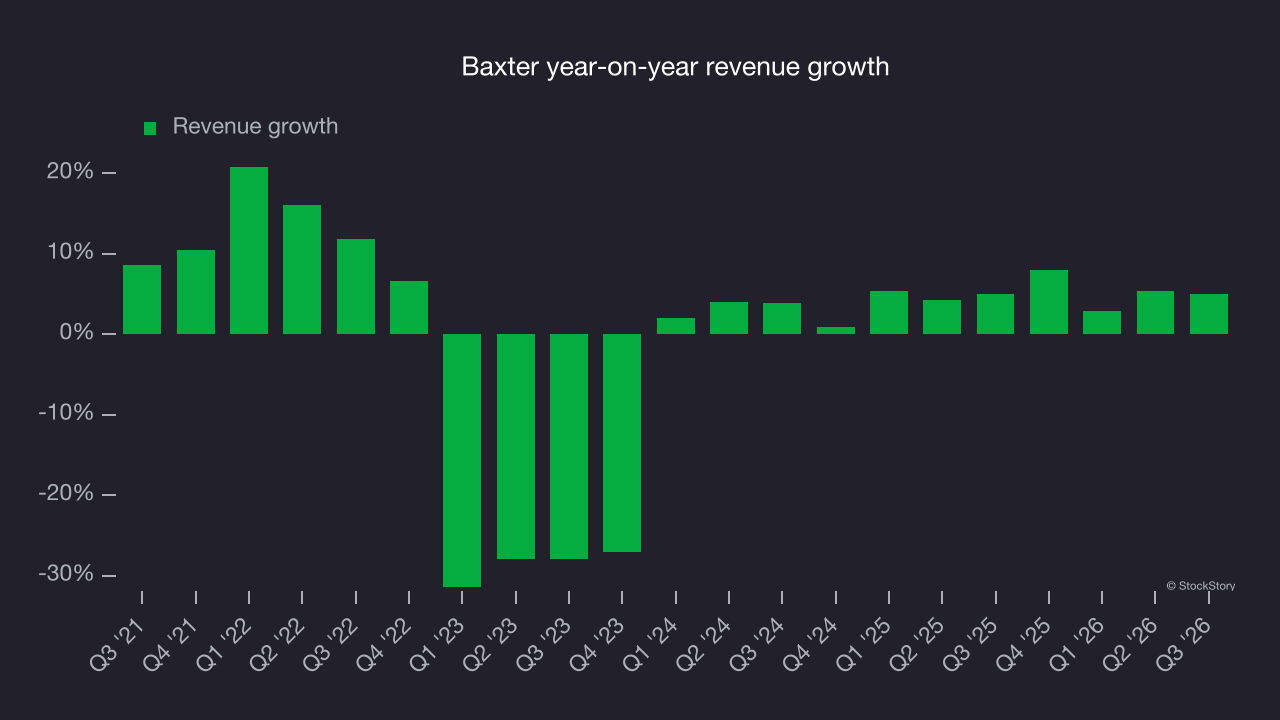
Baxter also reports revenue performance excluding currency movements, which are outside the company’s control and not indicative of demand. Over the last two years, its constant currency revenue averaged 2.8% year-on-year growth. Reported revenue growth outpaced constant currency growth, indicating that foreign exchange rates boosted Baxter’s performance. 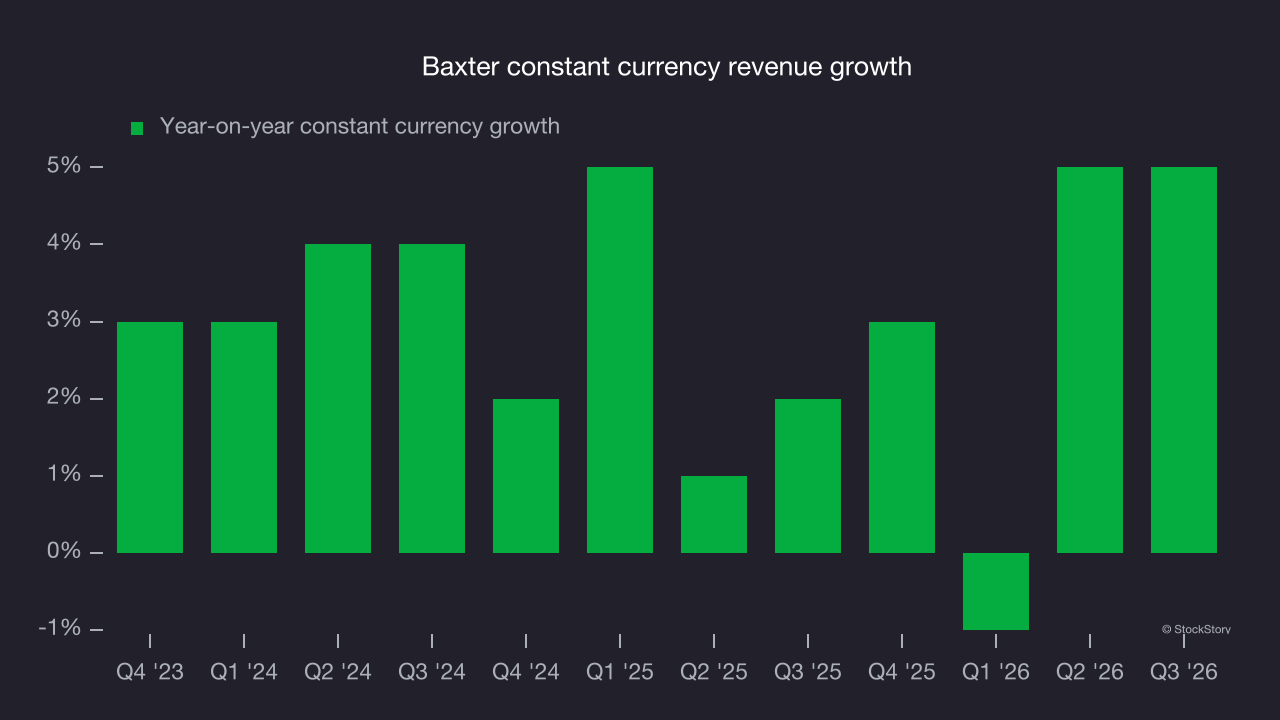
This quarter, Baxter reported modest year-on-year revenue growth of 5% but beat Wall Street’s consensus estimates by 2.3%.
Looking ahead, sell-side analysts expect revenue to grow 1.5% over the next 12 months, according to S&P, a deceleration versus the last two years. This lackluster projection implies its products and services will see some demand headwinds.
Adjusted operating margin
Baxter has done a decent job managing its cost base over the last five years. The company has produced an average adjusted operating margin of 14.8%, higher than the broader healthcare sector.
Baxter’s adjusted operating margin decreased by 3.9 percentage points over the last five years. The company’s two-year trajectory also shows it failed to regain peak profitability as its margin fell by 1.4 percentage points. This performance was poor, indicating that its expenses were rising and it couldn’t pass those costs on to customers.
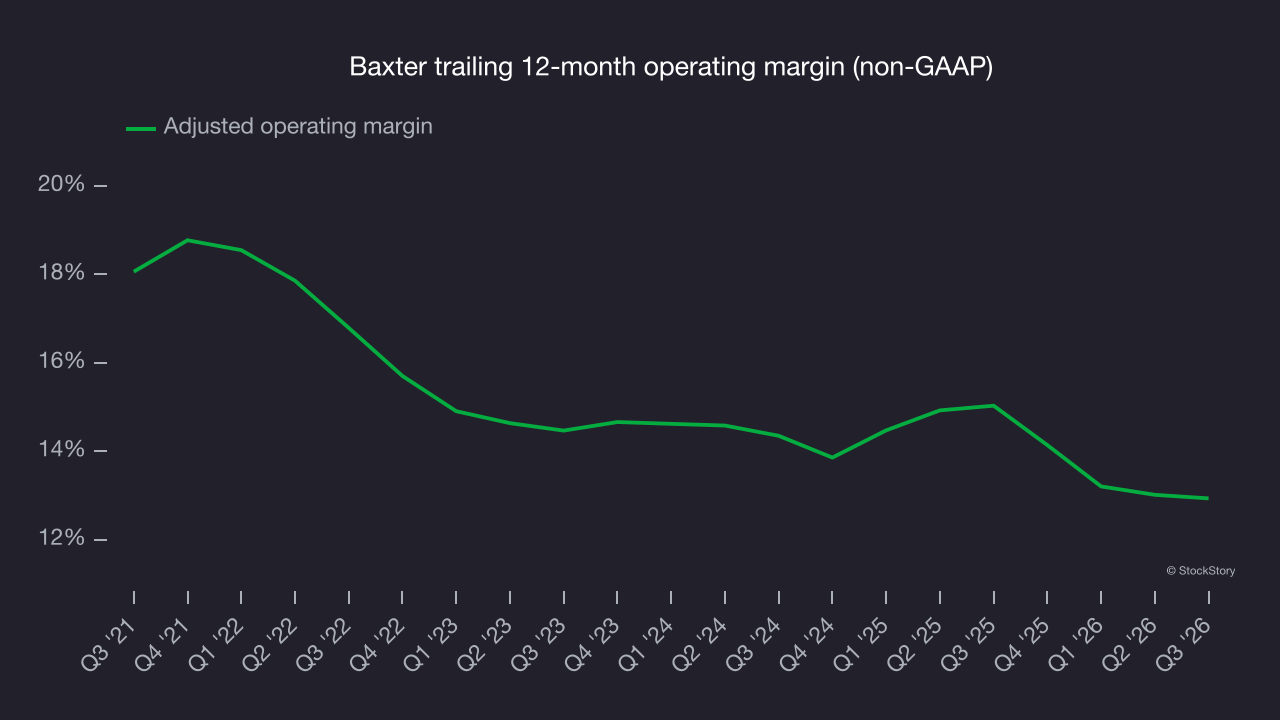
This quarter, Baxter generated an adjusted operating margin of 14.5%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Baxter’s EPS declined by 10.5% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
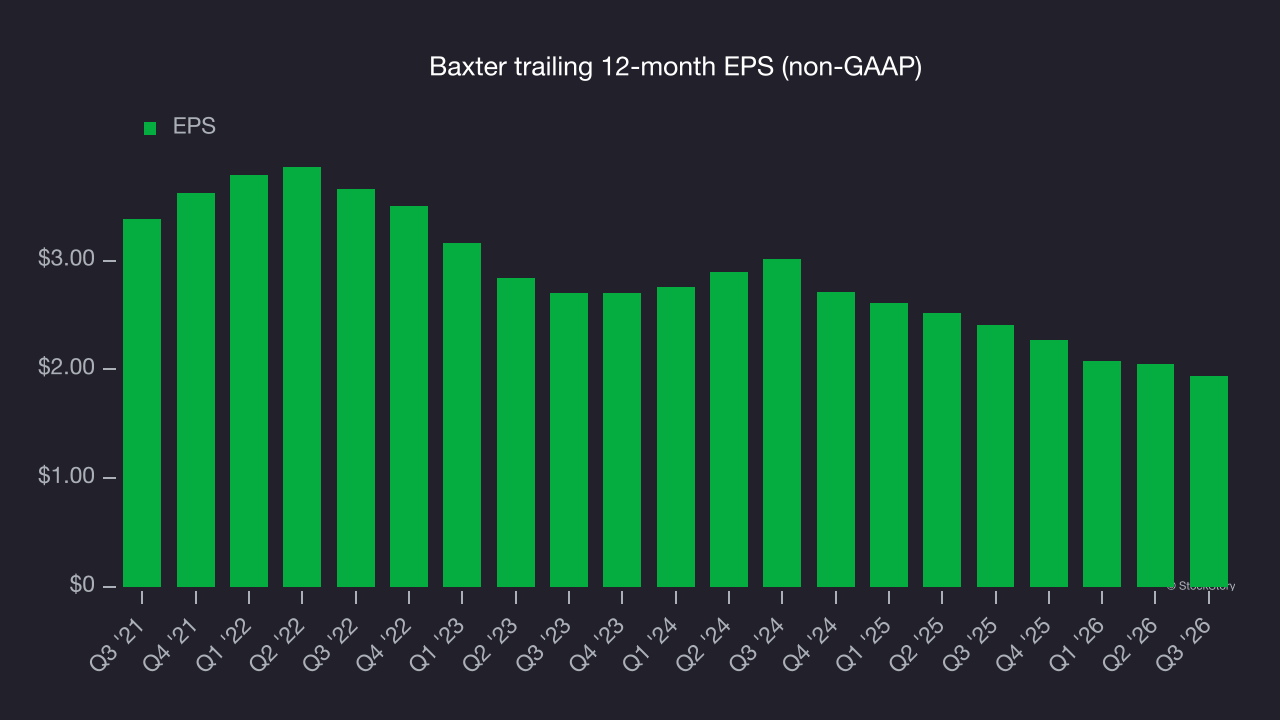
A closer look at Baxter’s earnings helps explain the drivers of its performance. Baxter’s adjusted operating margin was flat this quarter but declined by 3.9 percentage points over the last five years. Its share count also grew by 2.8%, meaning the company not only became less efficient with its operating expenses but also diluted its shareholders. 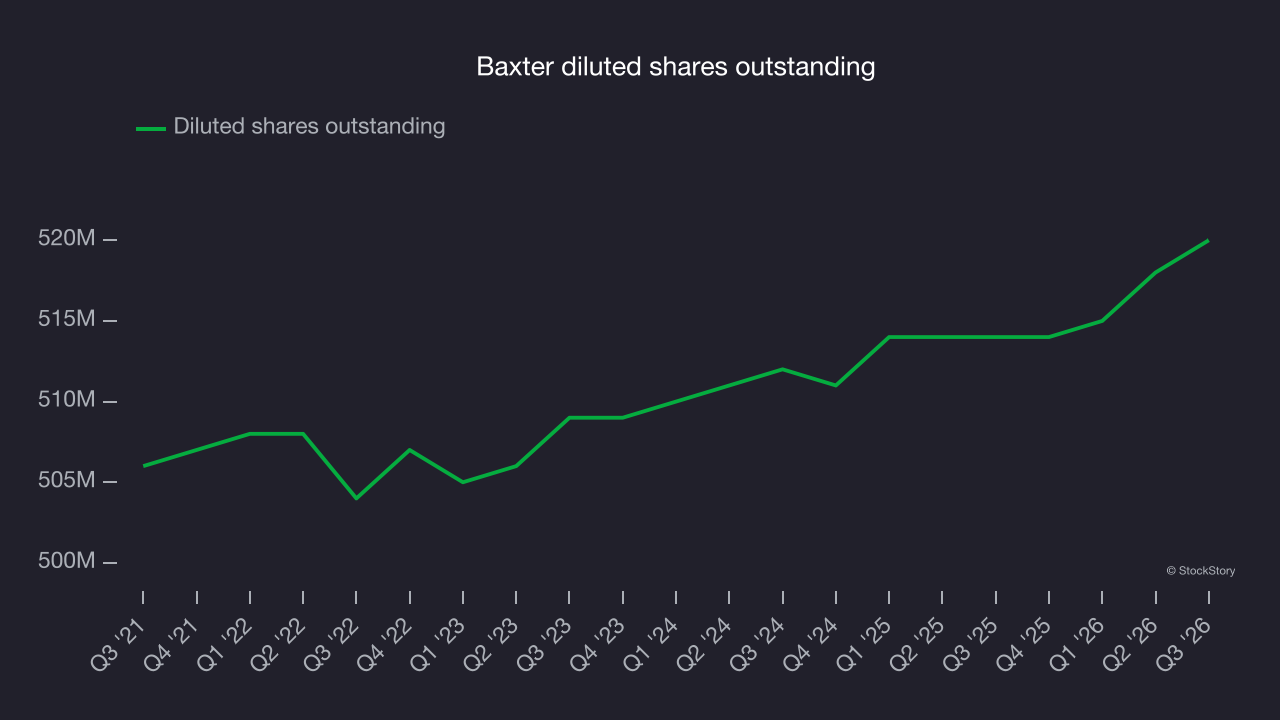
In Q3, Baxter reported adjusted EPS of $0.58, down from $0.69 in the same quarter last year. Despite falling year on year, this result came in well above analysts’ consensus estimates. Over the next 12 months, Wall Street expects Baxter’s full-year EPS to grow 9.1% from $1.94 to $2.12, according to S&P.
Key takeaways from Baxter’s Q3 results
Baxter delivered a solid quarter, with EPS topping Wall Street’s consensus estimates and full-year EPS guidance also coming in above analysts’ expectations. Shares rose 3.4% to $26.34 immediately after the report.
Baxter had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. The investment case requires a closer look. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. For more on Baxter, read the full research report here (it’s free).