


Befesa (XTRA:BFSA) just released third quarter and nine month results, giving investors fresh numbers on sales, earnings and profitability at a time when the stock’s valuation is already under closer scrutiny.
That earnings update landed after a strong run, with Befesa’s share price up 16.32% year to date at €34.85 and the 1-year total shareholder return at 22.09%, while the 5-year total shareholder return is still down 36.54%. Recent momentum is therefore rebuilding from a weaker long-term base.
Spot similar earnings-driven momentum and rebuilding stories to Befesa by scanning our hand-picked 608 high quality undiscovered gems, which are poised to attract more attention from investors.Befesa’s earnings are moving in the right direction while the share price only recently started to recover. Is this rebound mainly about improving fundamentals, or is it driven by a shift in sentiment around the stock as investors reassess valuation?
Most Popular Narrative: 18% Undervalued
Befesa’s most followed valuation narrative pegs fair value at €42.70, compared with the latest close at €34.85, which puts the recent share price recovery in a different light.
The main thing that has to go right is that Befesa sustains high utilization and stable earnings in steel dust and salt slag recycling while keeping capex below €80m and net leverage around or below 2x as management plans.
The current valuation implies that the share price does not fully reflect the company’s delivery on EBITDA growth, deleveraging and cash generation targets alongside multi year zinc price hedging at around $3,000 to $3,100/t.
See why 8 investors see Befesa as 18% undervalued.
Result: Fair Value of €42.70 (UNDERVALUED)
Still, the Befesa story can change quickly if U.S. and China utilization stalls or if cost inflation keeps eroding already tight aluminum recycling margins.
Find out about the key risks to this Befesa narrative.
Another View: What P/E Says About Befesa
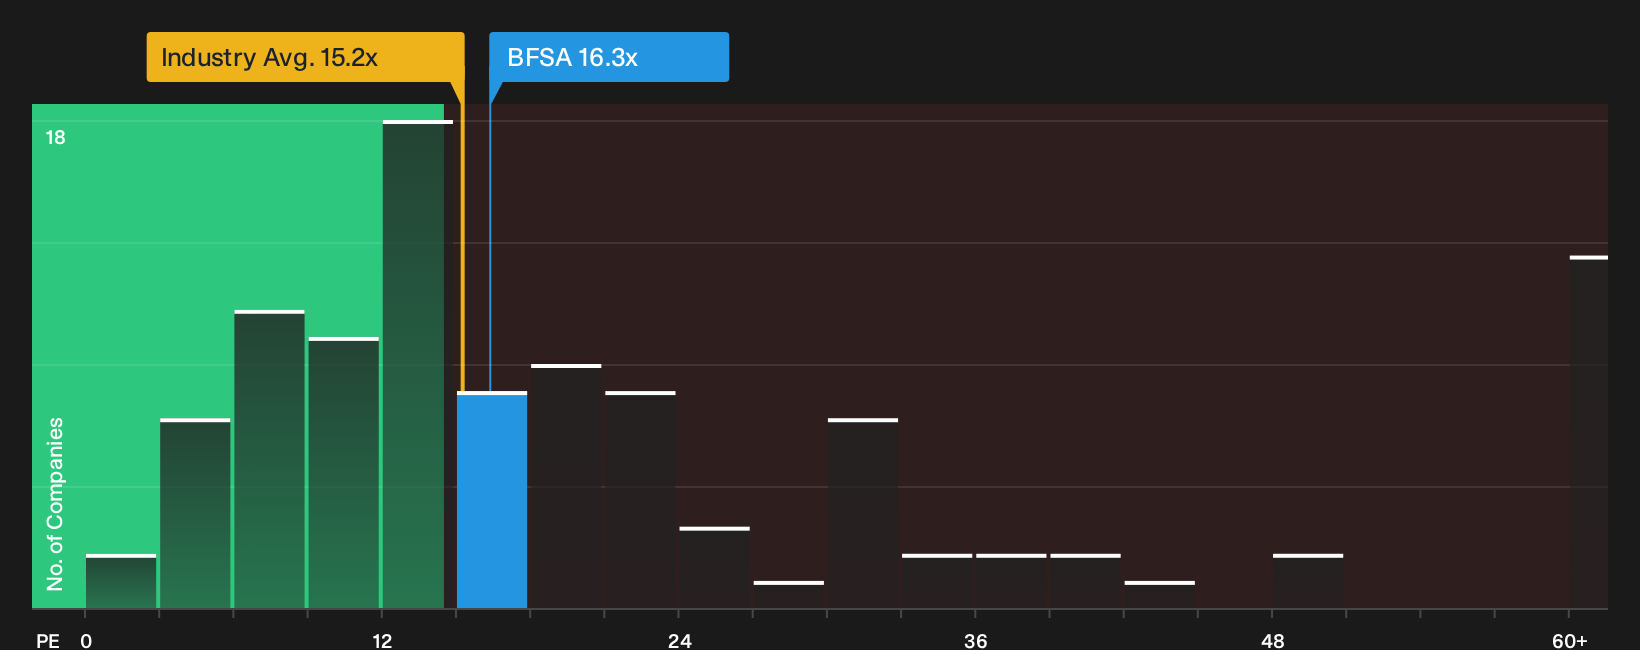
The analyst narrative points to Befesa trading below a fair value of €42.70, yet the market is not giving the stock away cheaply. At a P/E of 16.3x, the shares are priced higher than the European Commercial Services industry on 15.2x and above a fair ratio of 13x that the market could move toward. This raises the risk that sentiment, not just fundamentals, may need to do more work here.
For investors weighing this, the question is simple: Does paying more than peers and that fair ratio feel like a reasonable entry point, or does it narrow the margin of safety too much for your taste?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Befesa’s valuation can either feel like noise or a useful prompt to dig deeper into the story yourself. If you want the full picture of what the market is worried about and what could go right, start by weighing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Befesa?
If Befesa has sharpened your focus on valuation and earnings quality, broaden your opportunity set now with a few targeted stock lists before the next move passes you by.
- Target resilient potential by reviewing companies on our 229 resilient stocks with low risk scores that score well on risk metrics and may help steady your portfolio.
- Hunt for pricing gaps by scanning the 190 high quality undervalued stocks that combine quality fundamentals with valuations that screens flag as appealing.
- Strengthen your foundation by checking the list of solid balance sheet and fundamentals (206 results) that pair robust finances with underlying business performance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com