


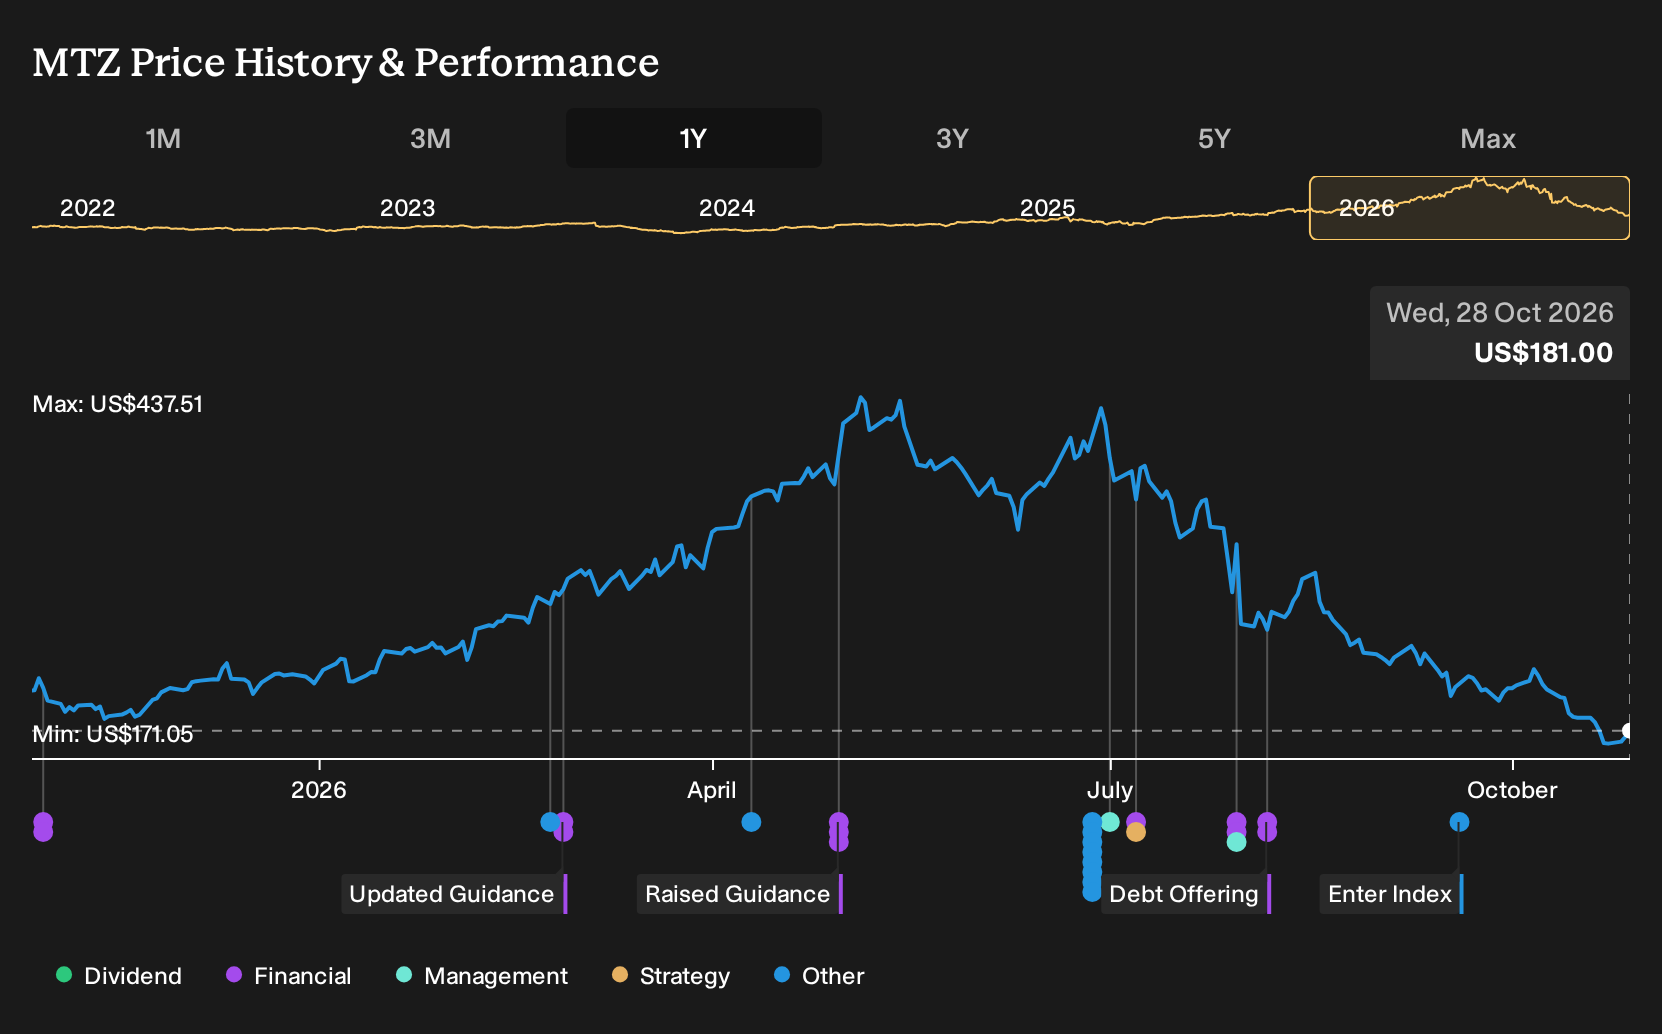
- MasTec plans to report Q3 2026 results after the market close on October 29, with consensus pointing to double digit gains in both revenue and earnings from its infrastructure construction work.
- The key operational focus is whether MasTec turns its large multi segment project backlog into profitable work across Power Delivery, Clean Energy & Infrastructure, Pipeline and Communications.
- We will examine how MasTec's investment narrative compares with these high expectations for converting backlog into profitable reported earnings.
Scan how MasTec's setup compares by reviewing 43 power grid technology and infrastructure stocks that could also be gearing up for outsized attention around grid upgrades and large project backlogs.
MasTec Investment Narrative Recap
To own MasTec, you need to believe its record backlog in Power Delivery, Clean Energy & Infrastructure, and Pipeline can be turned into steady, high quality earnings while Communications gradually stabilises. The Q3 2026 release on October 29 is a near term check on that thesis. It tests whether execution, cash generation and margins are lining up with the bigger project pipeline.
The near term catalyst is delivery against already high expectations for double digit revenue and profit growth. The biggest risk remains an earnings miss that revives concerns about Communications softness or project execution. If the quarter is in line with guidance, the long project queue likely remains the main driver of sentiment.
The key announcement tied to all of this is MasTec confirming it will report Q3 2026 results after the market close on October 29. That timing focuses attention on how efficiently the enterprise converts its US$21.4b style backlog into actual revenue and EBITDA across segments, especially grid, clean energy and pipeline work.
The call is likely to focus on mix and profitability rather than just headline growth. Communications weakness, previously flagged in the reduced 2026 outlook, still looks like the swing factor for consolidated margins. The key question for shareholders is whether demand in Power Delivery, Clean Energy & Infrastructure and Pipeline is offsetting that drag and supporting an earnings profile that justifies MasTec’s higher P/E multiple versus construction peers.
MasTec Consensus Targets and Embedded Assumptions
MasTec's current analyst setup is built around sizable growth expectations rather than minor tweaks at the margin. The focus is on whether the construction group can move from today’s earnings base to the much larger profit pool analysts have sketched out, while keeping return expectations grounded in realistic execution on its backlog.
MasTec's narrative projects US$26.2b revenue and US$1.2b earnings by 2029. This implies 17.7% yearly revenue growth and an earnings increase of about US$705.7m from current earnings of US$494.3m.
Uncover why MasTec's fair value indicates a 113% potential upside to its current price. This gap could narrow quickly as expectations reset.
Exploring Other Perspectives
Some of the lowest MasTec forecasts lean hard into a different risk. They worry that AI and cloud data center clients slow or resize projects, leaving 2029 revenue closer to US$26.0b and earnings around US$1.1b. Those numbers, set before this Q3 report date, show how far views can diverge and why it helps to compare several narratives yourself.
Explore 4 other MasTec fair value estimates, including one that suggests it could be worth just $280.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MasTec research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MasTec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MasTec's overall financial health at a glance.
Looking for more MasTec sized investment ideas?
Once you have a view on MasTec, it can help to line it up against other opportunities that match different risk, income and balance sheet profiles using the Simply Wall St Screener.
- If you want potential value with quality fundamentals, start by scanning a focused group of 26 high quality undervalued stocks that pair resilient cash generation with sturdier balance sheets.
- For investors who care most about capital preservation and smoother ride potential, filter for 32 resilient stocks with low risk scores that score well on financial strength and risk checks.
- If you are hunting for future leaders before the crowd, compare MasTec with a curated pool of 19 high quality undiscovered gems that already show solid fundamentals but attract less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com