


Disco (TSE:6146) moved back into focus after its board approved an interim dividend of ¥186 per share, updated earnings guidance, and reported higher half year sales and net income on October 22, 2026.
Against this backdrop, Disco’s share price has eased in the short term, with the stock down about 8% over the past month and 11% over the past quarter. At the same time, the 3-year total shareholder return of about 92% and 5-year return of roughly 4x continue to indicate a strong longer run outcome. Recent dividend guidance, fresh earnings numbers and updated forecasts give investors new information to weigh these mixed short term moves against that longer record.
Scan other semiconductor players showing strong earnings trends and dividend momentum with our hand picked 15 high quality undervalued stocks that share some of the qualities investors are watching in Disco today.
Disco now trades below aggregate analyst targets after a sharp pullback. Is that a reasonable safety margin given recent earnings and dividend signals, or is it a sign that the market remains wary for good reason?
Price-to-Earnings of 35.4x: Is it justified for Disco?
Disco closed at ¥52,170, and on a P/E of 35.4x it trades on a richer earnings multiple than both the broader Japanese semiconductor group and its own estimated fair ratio.
The P/E ratio compares the current share price to earnings per share, so it effectively shows how much investors are paying for each unit of Disco’s profit. For a specialist equipment maker with 26.6% earnings growth over the past year and current net profit margins of 32%, a higher multiple often reflects the value the market places on that profit profile.
There is still a clear premium. Disco’s 35.4x P/E is sharply higher than the 20.1x average for the JP semiconductor industry, which indicates investors are paying materially more for each yen of earnings than they would for the typical peer. Against the estimated fair P/E of 30.3x, the current level also sits above a ratio the market could move toward if sentiment cools or if earnings delivery does not keep pace with expectations.
Explore the SWS fair ratio for Disco.
Result: Price-to-Earnings of 35.4x (OVERVALUED)
Still, the bullish case for Disco can stumble if demand for precision cutting and grinding equipment softens, or if competitors pressure pricing and compress those current margins.
Find out about the key risks to this Disco narrative.
Another View: Disco through a cash flow lens
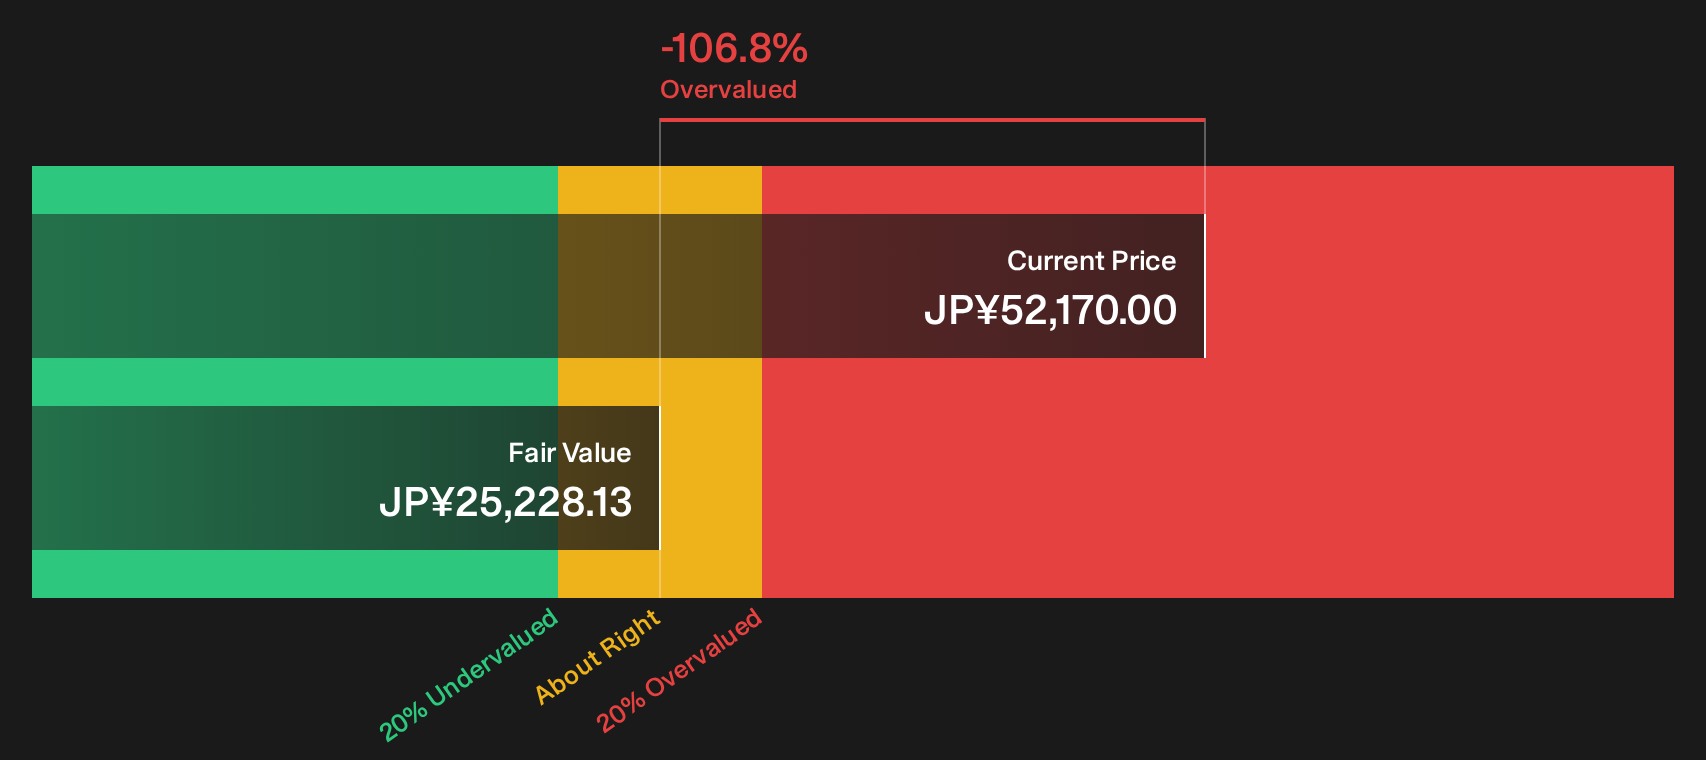
The P/E ratio paints Disco as expensive, yet the SWS DCF model goes even further. It values the shares at about ¥25,228 per share based on future cash flows versus a market price of ¥52,170, which points to a stock trading well above that cash flow estimate.
For investors, that sort of gap can look like a rich valuation rather than a cushion, especially if future cash generation tracks closer to the DCF assumptions than the upbeat earnings multiple. The question is whether you trust the market’s current optimism or the more cautious cash flow math.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Disco for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Disco’s valuation and cash flows are one thing; your judgment is another. Move quickly, review the full picture, and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Disco?
If Disco is on your radar, do not stop there. Broaden your watchlist now so you are not relying on a single opportunity to do all the work.
- Target resilient balance sheets and steady fundamentals with a list of solid balance sheet and fundamentals (23 results) that can help you filter for financial strength fast.
- Hunt for stocks that pair quality with attractive pricing by scanning a 15 high quality undervalued stocks before the crowd catches on.
- Spot companies flying under the radar by checking a 72 high quality undiscovered gems that highlights lesser known opportunities with solid underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com