


West Pharmaceutical Services (WST) just paired a third quarter earnings update with higher full year 2026 net sales guidance, a combination that tends to sharpen investor focus on the stock.
The recent guidance lift lands after a busy few weeks for West Pharmaceutical Services, with the 1-month share price return of 7.45% and 90-day share price return of 18.86% pointing to building momentum as investors digest stronger quarterly results, a higher dividend and a fresh credit facility, even though the 5-year total shareholder return is slightly negative at 6.67% while the 1-year total shareholder return of 42.14% has been far more supportive.
Capitalize on the momentum around West Pharmaceutical Services by lining it up against a hand picked 32 resilient stocks with low risk scores that have shown resilience through recent earnings seasons.After a sharp rerating on stronger guidance and a richer dividend, West Pharmaceutical Services now asks a simple question of new money: Does the current price still leave enough upside to justify the risk?
Most Popular Narrative: 2% Undervalued
On the most followed narrative, West Pharmaceutical Services screens as modestly undervalued, with a fair value of $413.73 versus a last close of $403.64. This puts the spotlight on whether execution can keep supporting that premium setup.
The key factor is successful execution on higher margin opportunities such as drug handling and other value-added work in West Vantage, while maintaining HVP capacity, quality and pricing.
The numbers suggest the share price already reflects a premium valuation for West Pharmaceutical Services, so the view that the stock is undervalued depends on the company meeting expectations for higher growth and margin expansion.
See why 15 investors see West Pharmaceutical Services as 2% undervalued.
Result: Fair Value of $413.73 (UNDERVALUED)
Still, the risk is clear if West Pharmaceutical Services falls short on high value component growth or if premium valuation expectations decline in response to any earnings wobble.
Find out about the key risks to this West Pharmaceutical Services narrative.
Another View: Rich Multiples Around West Pharmaceutical Services
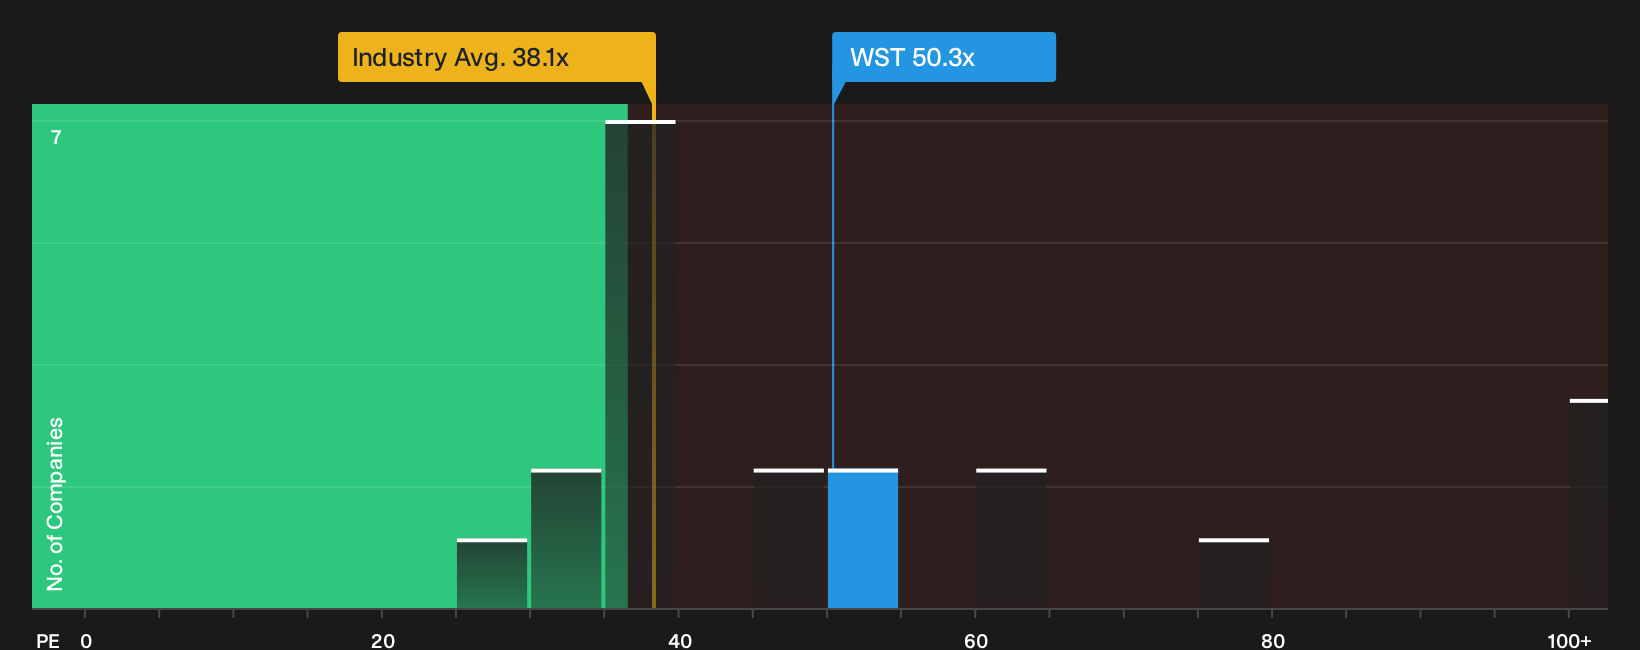
There is a catch. While one narrative tags West Pharmaceutical Services as about 2% undervalued, the current P/E of 50.3x sits well above the Global Life Sciences average of 36.9x and more than double its own fair ratio of 24.6x. That gap points to valuation risk if sentiment cools.
See what the numbers say about this price in more detail in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around West Pharmaceutical Services is charged right now, so move quickly. Test the assumptions against the raw numbers, and then back your own judgment by weighing the 2 key rewards.
Looking for more investment ideas beyond West Pharmaceutical Services?
West Pharmaceutical Services might be front of mind today, but a broader watchlist gives you more ways to react when the next opportunity shows up.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio when sentiment swings.
- Hunt for quality at a discount by reviewing a curated 26 high quality undervalued stocks that pairs fundamentals with compelling pricing.
- Put your capital to work for income by focusing on a 6 dividend fortresses built around higher-yield payers with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com