


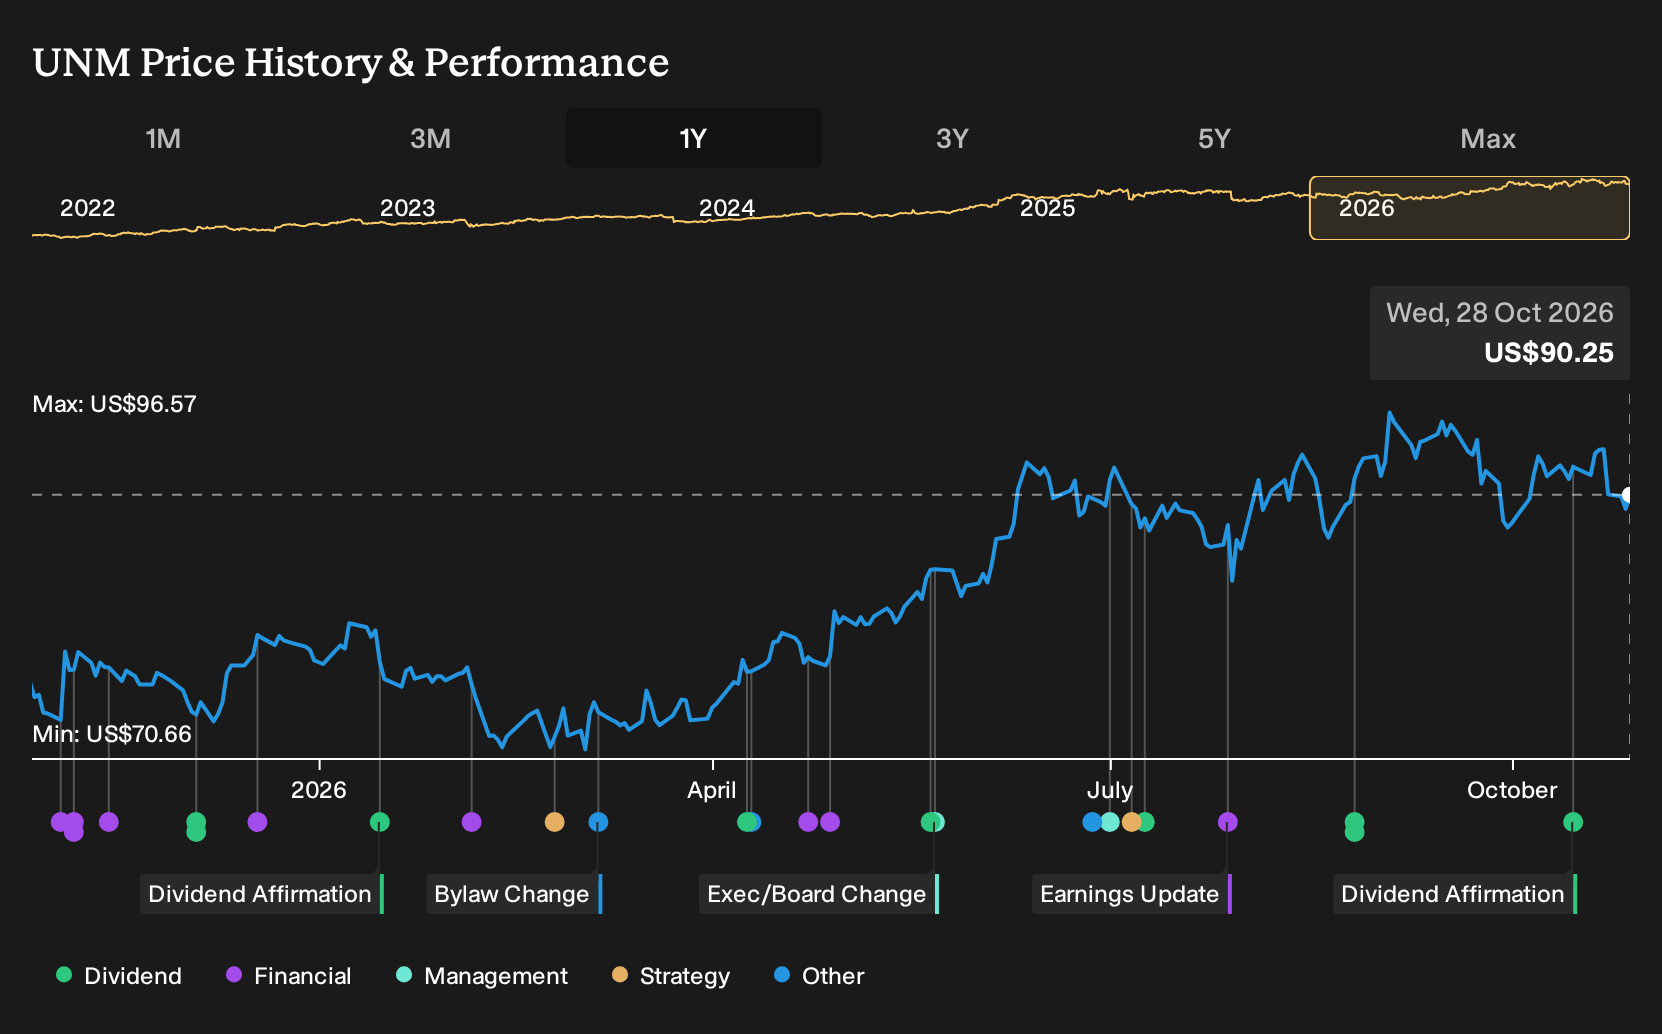
- Unum Group's board previously declared a quarterly dividend of $0.505 per share on its common stock, payable on November 20, 2026, to shareholders of record as of October 30, 2026.
- The dividend decision arrives as analysts raise earnings estimates ahead of the November 3 quarterly report, indicating confidence in Unum Group's underlying employee benefits franchise.
- We will examine how Unum Group's investment narrative is influenced by this affirmed dividend in combination with expectations for another earnings beat.
Unum Group Investment Narrative Recap
To own Unum Group, you need to be comfortable with a benefits insurer that leans on disciplined pricing, digital tools and capital return while working through uneven profit margins. The big near term swing factor is whether group disability, group life and paid family and medical leave benefit ratios settle closer to management’s targets or keep squeezing earnings.
The largest operational risk still sits in claims behavior. Elevated disability ratios, weaker paid family and medical leave results and the long term care closed block all have potential to pressure reserves and capital if experience worsens. The latest dividend affirmation does not materially change those underlying exposures.
The fresh quarterly dividend declaration of US$0.505 per share on Unum Group’s common stock matters most as a signal on balance sheet flexibility and cash generation. Management is committing to a regular cash outlay while analysts expect another possible earnings beat for the September 2026 quarter.
For you, the link between that payout and the upcoming November 3 earnings report is simple. Consistent dividends plus any upside in earnings versus expectations would support the view that the core employee benefits engine and digital platforms are doing the heavy lifting, even as long term care and benefit ratios remain the key items to watch.
Unum Group's current analyst story points to revenues of US$13.1b and earnings of US$1.6b by 2029. That outcome lines up with analyst assumptions of fairly flat annual revenue trends and an earnings increase of about US$897.3m from US$702.7m today.
Discover how Unum Group's fair value indicates a 13% potential upside to its current price, which could narrow faster than income investors expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$101.85 and US$165.23 per share, which shows how far apart views on Unum Group can be. You are weighing those dispersed opinions against risks around benefit ratios and long term care reserves, with dividend commitments and digital initiatives acting as possible counterweights.
Explore 2 other Unum Group fair value estimates, including one that suggests as much as 83% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Unum Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Unum Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unum Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Unum Group?
Once you have a view on Unum Group, it can help to line it up against other opportunities that match your income, quality or risk preferences using the Simply Wall St Screener.
- For investors who want potential upside with strict balance sheet discipline, scan a list of solid balance sheet and fundamentals (24 results) that can complement an insurer like Unum Group.
- If your priority is resilience over excitement, review a 32 resilient stocks with low risk scores that may offer steadier business profiles alongside more cyclical holdings.
- When you want something less crowded by attention, look across a 19 high quality undiscovered gems that might sit off the usual radar but still show robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com