


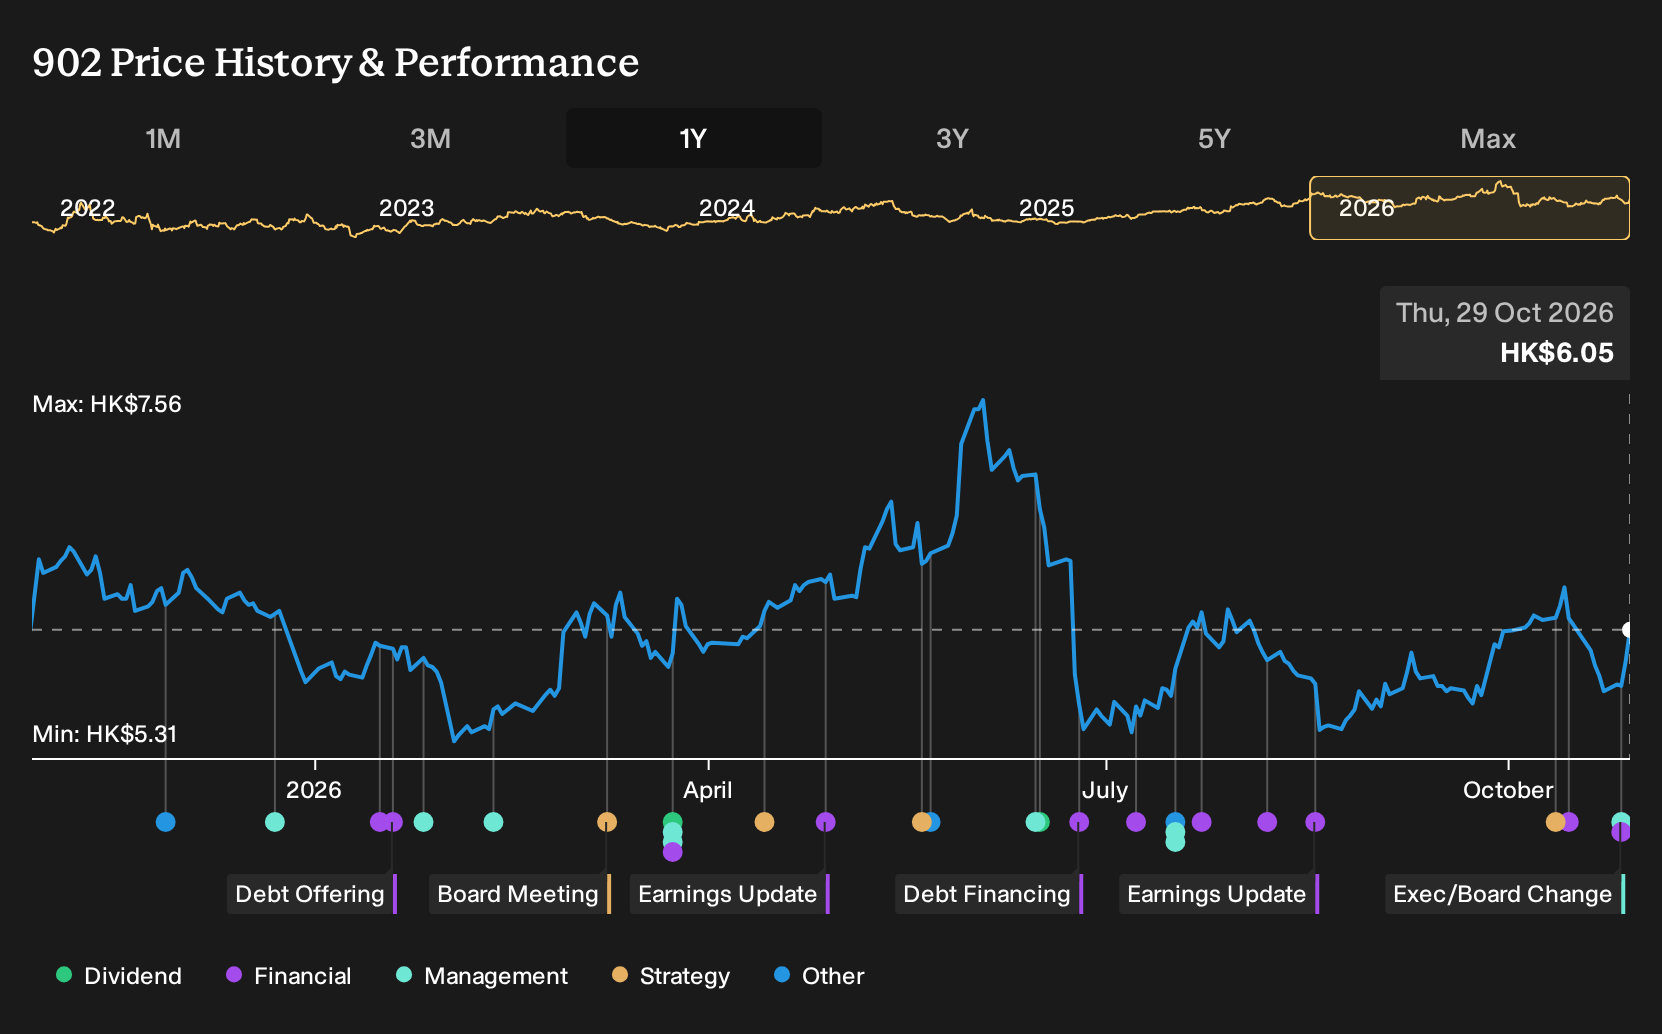
- Huaneng Power International reported basic and diluted earnings per share from continuing operations of CNY 0.39 for the nine months to September 30, 2026, compared with CNY 0.81 a year earlier, alongside upcoming board changes as two non executive directors step down following the election of a new board session.
- The sharp year over year drop in earnings per share points to pressure on underlying profitability, which puts fresh attention on how Huaneng Power International balances fuel costs, tariffs and the economics of its growing low carbon portfolio.
- We will assess how Huaneng Power International's investment narrative holds up against this earnings per share compression and profitability signal.
Huaneng Power International Investment Narrative Recap
For an investor to back Huaneng Power International, the core belief is that the shift toward cleaner generation and capacity-based coal earnings can offset tariff pressure, weaker volumes and fuel cost swings. The sharp earnings per share compression to CNY 0.39 puts that thesis under strain in the near term and keeps attention on cash flow and project returns.
The key short-term catalyst still lies in how quickly new wind, solar and gas capacity can contribute at acceptable margins. The biggest current risk is that lower on-grid tariffs and softer profitability in parts of the renewable portfolio persist, which would make it harder for Huaneng Power International to support both debt service and dividends.
The earnings announcement for the nine months to September 30, 2026 is the clearest signal to focus on. Basic and diluted earnings per share from continuing operations of CNY 0.39 compared with CNY 0.81 a year earlier highlight profit compression that interacts directly with existing concerns about margin pressure and tariff softness.
For you as a shareholder or prospective investor, that drop tightens the margin for error around the current build-out plan and high payout ambitions. It also makes fuel procurement discipline, capacity payments and the economics of loss-making PV farms more central catalysts, since weaker earnings coverage can amplify the impact of any further cost or pricing shocks on Huaneng Power International.
What The Current Forecasts Assume For Huaneng Power International
Analyst expectations for Huaneng Power International sketch out a tight balancing act. Revenue is projected to decline by 1.4% a year over the next 3 years, even as consensus models build in higher profit margins and bigger earnings by 2029.
Forecasts point to earnings today of CNY 9.3b and consensus earnings of CNY 11.8b by 2029, which implies an increase of about CNY 2.5b. That step up in profit, alongside a margin move from 4.1% to 5.5% on a shrinking top line, indicates that analysts are focusing on mix, cost control, and asset productivity rather than headline growth.
Revenue projections also feed directly into the valuation story that now underpins Huaneng Power International. To line up with current targets, models assume 2029 revenue of CNY 215.1b and profit of CNY 11.8b, with the stock trading on a P/E of 9.8x compared with about 9.0x today and a reported 8.9x for the US Renewable Energy sector.
Huaneng Power International's narrative projects CNY 215.1b revenue and CNY 11.8b earnings by 2029. This involves a 1.4% yearly revenue decline and an earnings increase of about CNY 2.5b from CNY 9.3b today.
Uncover why Huaneng Power International's fair value aligns with its current price.
Exploring Other Perspectives
One alternate angle on Huaneng Power International focuses on the boardroom rather than the turbines. The most optimistic analysts were already pencilling in CNY 224.3b of revenue and CNY 12.3b of earnings by 2029, assuming cleaner assets and new projects shine. With two non executive directors set to depart and weaker earnings now disclosed, those upbeat forecasts may be revisited. Use this as a prompt to compare several viewpoints before deciding how you interpret the new information.
Explore another Huaneng Power International fair value estimate, including one that suggests it could be worth as much as HK$5.98.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own analysis.
- A great starting point for your Huaneng Power International research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Huaneng Power International. The report includes a fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Huaneng Power International's overall financial profile at a glance.
Looking For More Investment Ideas Beyond Huaneng Power International?
Once you have a view on Huaneng Power International, it can help to widen the lens and compare it with other companies that share some of the qualities you are looking for. The Simply Wall St Screener offers curated sets of stocks so you can quickly focus on the types of businesses that best fit your approach.
- If capital preservation sits near the top of your priorities, review a group of companies screened for resilience and relatively low risk profiles through the 229 resilient stocks with low risk scores.
- For readers who want balance sheet strength to support future decisions, start with a list of solid balance sheet and fundamentals (206 results) and see which businesses pair financial stability with fundamental support.
- Those searching for potential mispricing opportunities can scan a 191 high quality undervalued stocks and compare these candidates with your thesis on Huaneng Power International.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com