


- Arch Capital Group reported third quarter 2026 results with revenue of US$4.655b, net income of US$1.035b, and diluted EPS from continuing operations of US$3.00.
- The insurer’s combined ratio of 82.5% and other underwriting metrics outperformed analyst estimates, indicating tight risk selection despite catastrophe losses and uneven market conditions.
- This article examines how Arch Capital Group's investment narrative is influenced by stronger underwriting efficiency highlighted in its latest quarterly results.
Arch Capital Group Investment Narrative Recap
To be comfortable owning Arch Capital Group, you need to believe its underwriting discipline and cycle management still matter more than headline revenue or quarterly earnings swings. The latest quarter showed lower revenue and net income than a year ago, yet an 82.5% combined ratio and strong EPS point to tight risk selection as the real engine.
The key short-term swing factor remains how Arch Capital Group handles catastrophe-exposed property and reinsurance as markets soften and competition increases. The biggest risk is a cluster of large loss events or faster-than-expected pricing pressure, which would strain combined ratios. This quarter does not materially change that balance.
The third quarter 2026 earnings release is the clearest reference point for those catalysts right now. Revenue of US$4.655b and net income of US$1.035b came in below the prior year, yet diluted EPS from continuing operations of US$3.00 and the EPS surprise suggest underwriting and investment income are still pulling weight together.
For an investor watching execution, the interesting part is how Arch Capital Group is absorbing catastrophe losses, including exposure linked to the Iran conflict, while keeping underwriting profitable across Insurance, Reinsurance and Mortgage. That supports the idea that portfolio reweighting and data-heavy underwriting remain central levers, even as analysts expect softer conditions ahead.
What The Arch Capital Group Forecasts Are Really Saying
Arch Capital Group's narrative projects forecast revenue of US$15.1b and consensus earnings of US$3.2b by 2029. This projection is based on an assumption that revenue will decline 7.8% per year and that earnings will fall by US$1.5b from US$4.7b today.
Uncover why Arch Capital Group's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
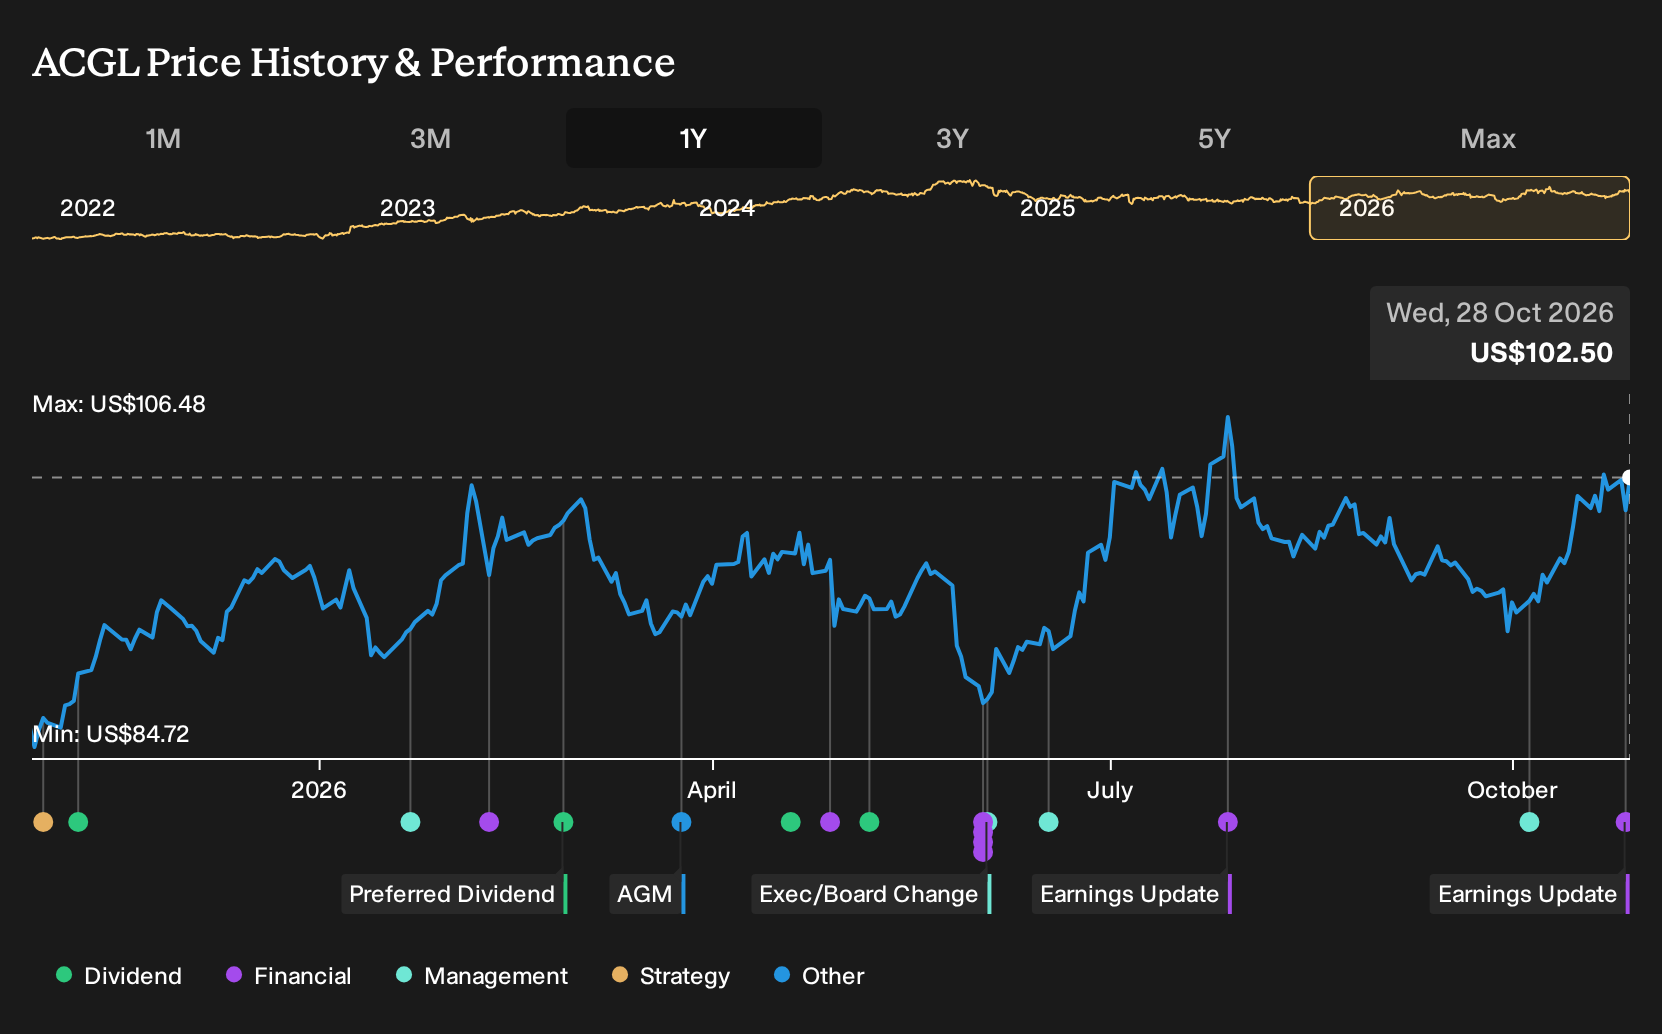
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit far apart, from about US$112 up to roughly US$222 per share. This already shows how wide opinion on Arch Capital Group can run. Layer in catastrophe risk, a softening insurance cycle, and mortgage sensitivity, and you have plenty of reasons to compare viewpoints before deciding your own stance.
Explore another Arch Capital Group fair value estimate, including one that suggests as much as 116% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Arch Capital Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Arch Capital Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arch Capital Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Arch Capital Group?
Once you have a view on Arch Capital Group, it helps to compare it with other opportunities that share similar qualities or offer a very different risk profile. The Simply Wall St Screener lets you do that quickly by filtering for specific traits you care about, whether that is balance sheet strength, income potential, or under followed quality.
- If you want companies that aim for robust finances first, start with a list of solid balance sheet and fundamentals (24 results) that filters for stronger balance sheets and cleaner fundamentals.
- For investors hunting for a mix of quality and valuation support, scan a curated set of 19 high quality undiscovered gems that may not yet be widely followed.
- If income is a priority, focus on potential cash return with a Screener built around 6 dividend fortresses that concentrates on higher yielding dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com