


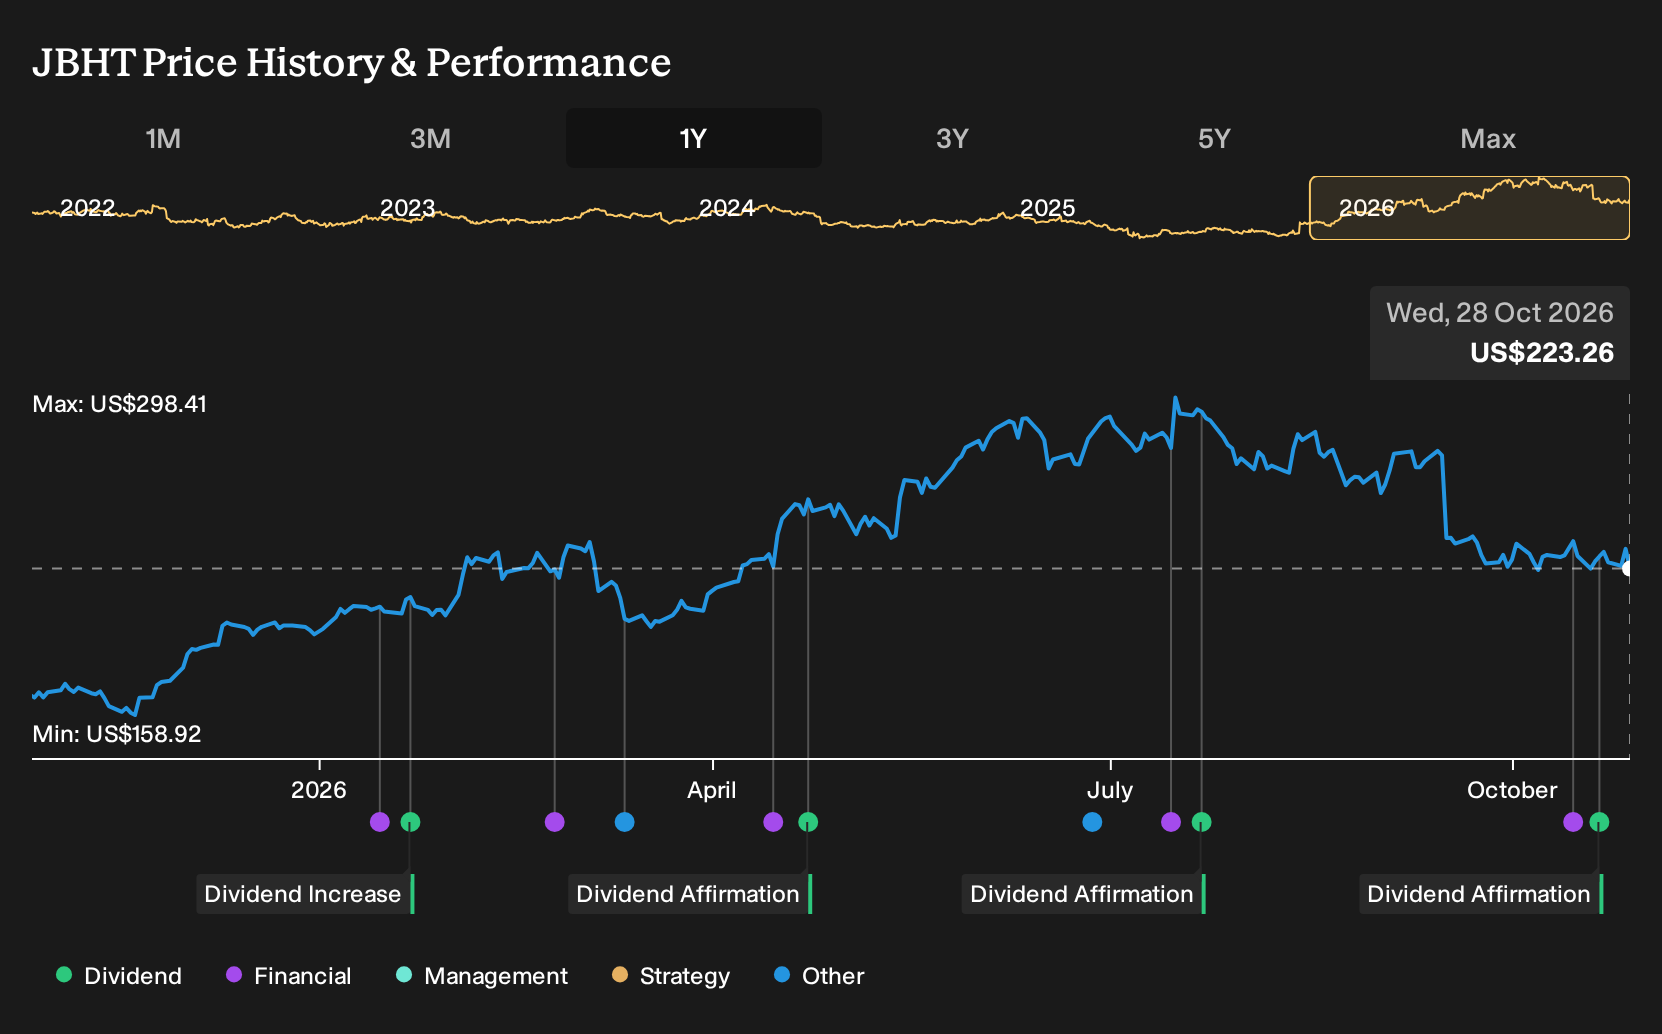
- J.B. Hunt Transport Services reported third quarter 2026 results with sales of US$3,006.02m, revenue of US$3,676.81m, net income of US$172.42m, and diluted EPS from continuing operations of US$1.82. The company also announced a US$0.45 quarterly dividend and ongoing share repurchases completed under the October 2025 authorization.
- The combination of higher year on year sales, revenue and earnings through the first nine months of 2026 and the completed US$383.83m buyback indicates that J.B. Hunt Transport Services has been returning capital to shareholders while supporting its operating performance.
- This sets the context for how J.B. Hunt Transport Services' investment narrative aligns with its latest earnings progress and ongoing share repurchases.
J.B. Hunt Transport Services Investment Narrative Recap
For J.B. Hunt Transport Services, the core belief for a shareholder is that intermodal and Dedicated growth, cost removal and the AI freight platform can offset driver and fuel pressure. The latest quarter delivered higher sales, revenue and earnings versus a year ago, which helps keep that execution story intact despite earlier guidance for softer Q3 profit versus Q2.
The near term swing factor remains how efficiently the network runs if fuel and wage costs stay elevated. Inflation that persists or worsens is still the key risk because it could cap margin recovery in Dedicated and intermodal, even if volume and contract wins progress as planned.
The completed US$383.83m buyback is the most relevant new data point for that thesis. J.B. Hunt Transport Services retired 1,671,435 shares, or 1.77% of the float, including 704,000 shares in Q3 alone. That sits alongside earnings per share from continuing operations of US$1.82 for the quarter and US$5.21 for the first nine months of 2026.
For you as an investor, this capital return only matters if the core freight engine keeps doing the work. The buyback does not reduce fuel, wage or legal risks, and it does not change the need for the intermodal conversion opportunity, Dedicated pipeline and AI freight platform to translate into durable margins through the next bid cycles.
J.B. Hunt Transport Services' narrative projects US$16.7b revenue and US$1.1b earnings by 2029. That path assumes 9.5% yearly revenue growth and requires an earnings increase of about US$425.5m from US$674.5m today.
Uncover why J.B. Hunt Transport Services' fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame tighter truckload capacity as the real swing factor for J.B. Hunt Transport Services, not just inflation risk. Before this earnings and dividend news, that group was pencilling in 15.5% annual revenue growth and about US$1.3b in earnings by 2029. Their view may shift. Yours does not have to match. It is worth comparing several angles before you decide how this story fits your portfolio.
Explore 3 other J.B. Hunt Transport Services fair value estimates, including one that suggests potential upside of as much as 35% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own informed judgment when assessing opportunities.
- A great starting point for your J.B. Hunt Transport Services research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for J.B. Hunt Transport Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate J.B. Hunt Transport Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond J.B. Hunt Transport Services?
If you want to put J.B. Hunt Transport Services in context, it helps to scan a wider field of companies that match clear financial themes. The Simply Wall St Screener can help you move from one interesting story to a short list of candidates that fit your income, quality or risk preferences.
- For investors who want income that does more of the heavy lifting, start with a curated set of companies offering resilient payouts through our 6 dividend fortresses.
- If value and balance sheet strength sit at the top of your checklist, filter for financially robust businesses using the list of solid balance sheet and fundamentals (24 results).
- When you want to get ahead of the crowd, focus on under-followed companies with strong fundamentals by scanning our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com