


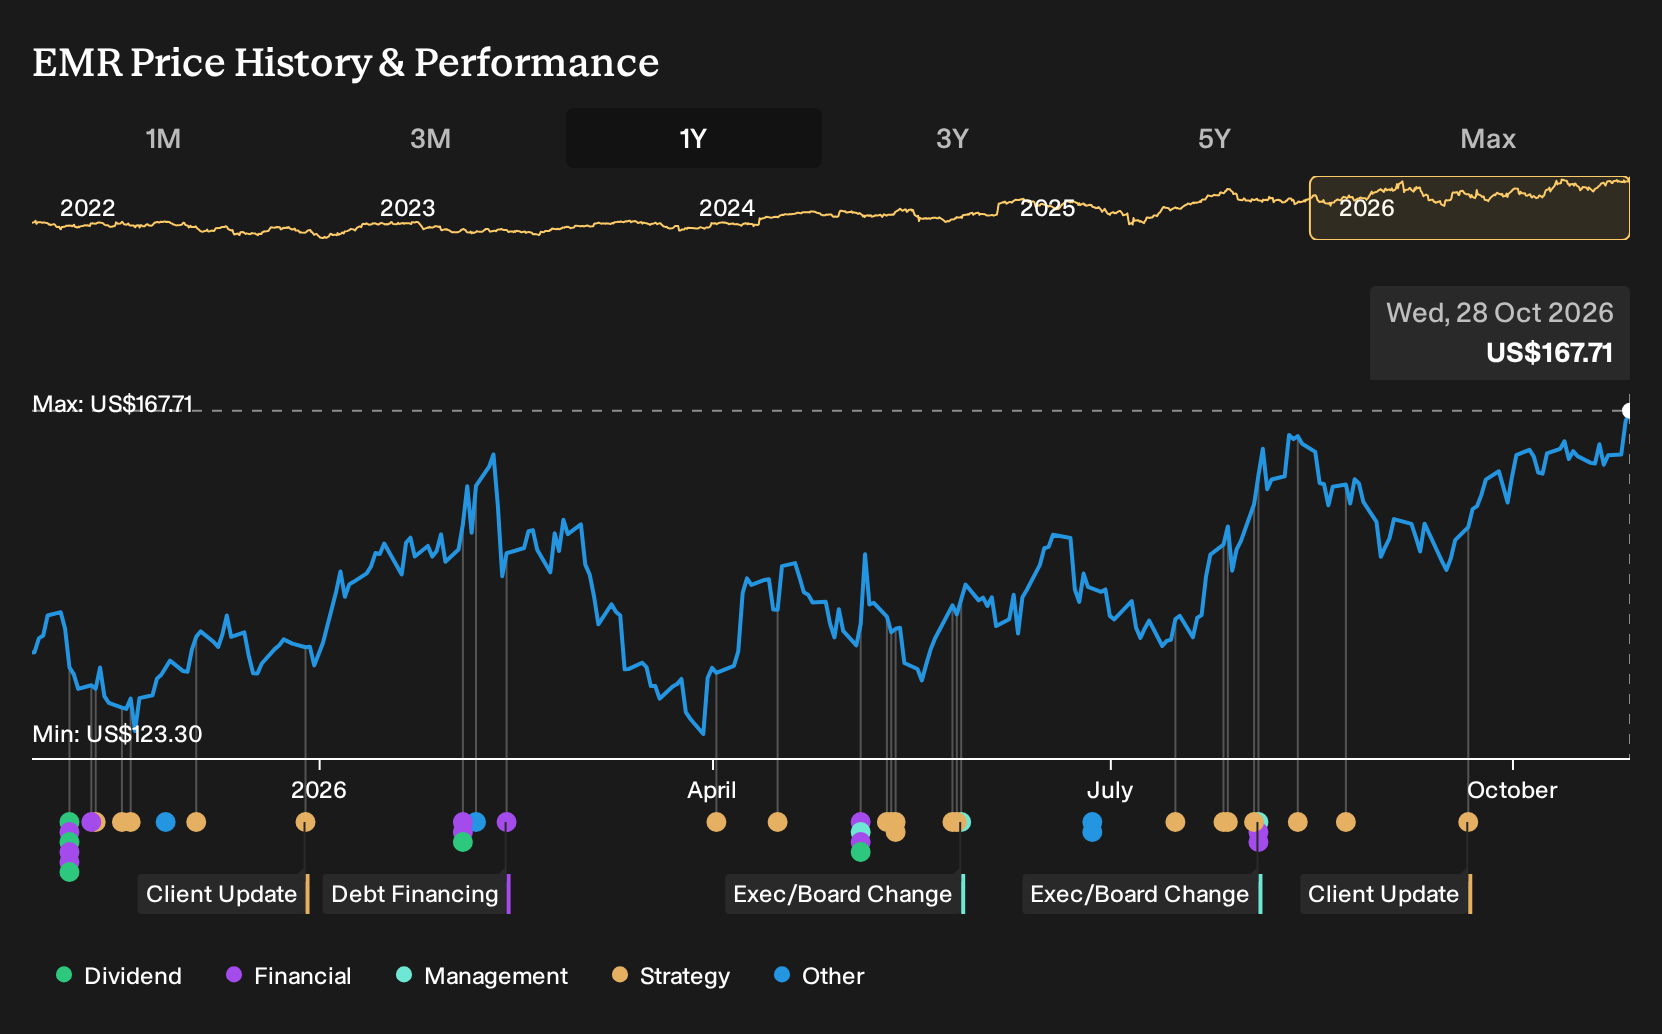
- Emerson Electric is heading into its 4 November 2026 earnings release with enthusiasm around its digital automation and AI-enabled product portfolio and a recent Zacks Rank of #2 that reflects constructive analyst views on current business conditions.
- Investor focus has turned to how effectively Emerson Electric converts its growing project funnel in areas like software and Test & Measurement into sustained, profitable revenue while dealing with softer demand in China chemicals and operational exposure to geopolitical conflict.
- Now the focus shifts to how this earnings anticipation around Emerson Electric's AI and digital automation momentum could reshape its investment narrative.
Scan other industrials riding the same digital and AI wave as Emerson Electric by zeroing in on a curated short list of 54 AI infrastructure stocks.
Emerson Electric Investment Narrative Recap
To be comfortable owning Emerson Electric, you need to believe its push into digital automation, AI software and Test & Measurement can keep offsetting weaker pockets like China chemicals and Middle East disruption. The near term hinge is simple. Can management keep converting that large power, LNG and software project funnel into clean, on time revenue?
The latest pre earnings optimism and recent share price strength do not materially change the immediate swing factor. Execution on those complex projects still matters most, while the key risk remains any further conflict related shutdowns or extended softness in Chinese process industries that drags on orders and squeezes operating margins.
The most relevant fresh data point is the setup into the 4 November 2026 earnings release for Emerson Electric, with expectations of strong EPS and revenue for the quarter and clear enthusiasm around AI enabled products. That upcoming report is the next real test of how well the order book is turning into actual sales and profit.
If the update shows power, LNG, software and Test & Measurement projects tracking well despite roughly US$100m of conflict related sales impact and ongoing China chemicals weakness, investors get more evidence that the digital and AI story is holding up under pressure. Any signs of project delays or broader regional softness would instead push execution risk back to the foreground.
Emerson Electric's current analyst narrative points to revenues of US$21.9b and earnings of US$3.8b by 2029, based on an assumed 5.6% annual revenue growth rate and an earnings increase of US$1.2b from US$2.6b today.
Uncover how Emerson Electric's fair value indicates a 4% potential upside to its current price before sentiment closes that discount.
Exploring Other Perspectives
One bullish twist on Emerson Electric centers on AI software momentum rather than geopolitical risk. The most optimistic analysts were penciling in revenues of about US$22.8b and earnings of roughly US$4.0b by 2029 before this earnings update, and they see that stronger AI driven mix as a reason sentiment could shift further if the story evolves.
Explore 3 other Emerson Electric fair value estimates, including one that suggests it could be worth as much as $175.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Emerson Electric research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Emerson Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Emerson Electric's overall financial health at a glance.
Looking for more investment ideas beyond Emerson Electric?
Once you have a view on Emerson Electric, it can help to line it up against other opportunities using a broader stock search.
- For those hunting for strong businesses that the market might be overlooking, start with a 26 high quality undervalued stocks that combine quality fundamentals with appealing pricing.
- If capital preservation and steadier profiles matter most to you, filter for 32 resilient stocks with low risk scores that score well on resilience and downside protection measures.
- When balance sheet strength sits at the top of your checklist, narrow the field to a list of solid balance sheet and fundamentals (24 results) that can better endure tougher operating conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com