


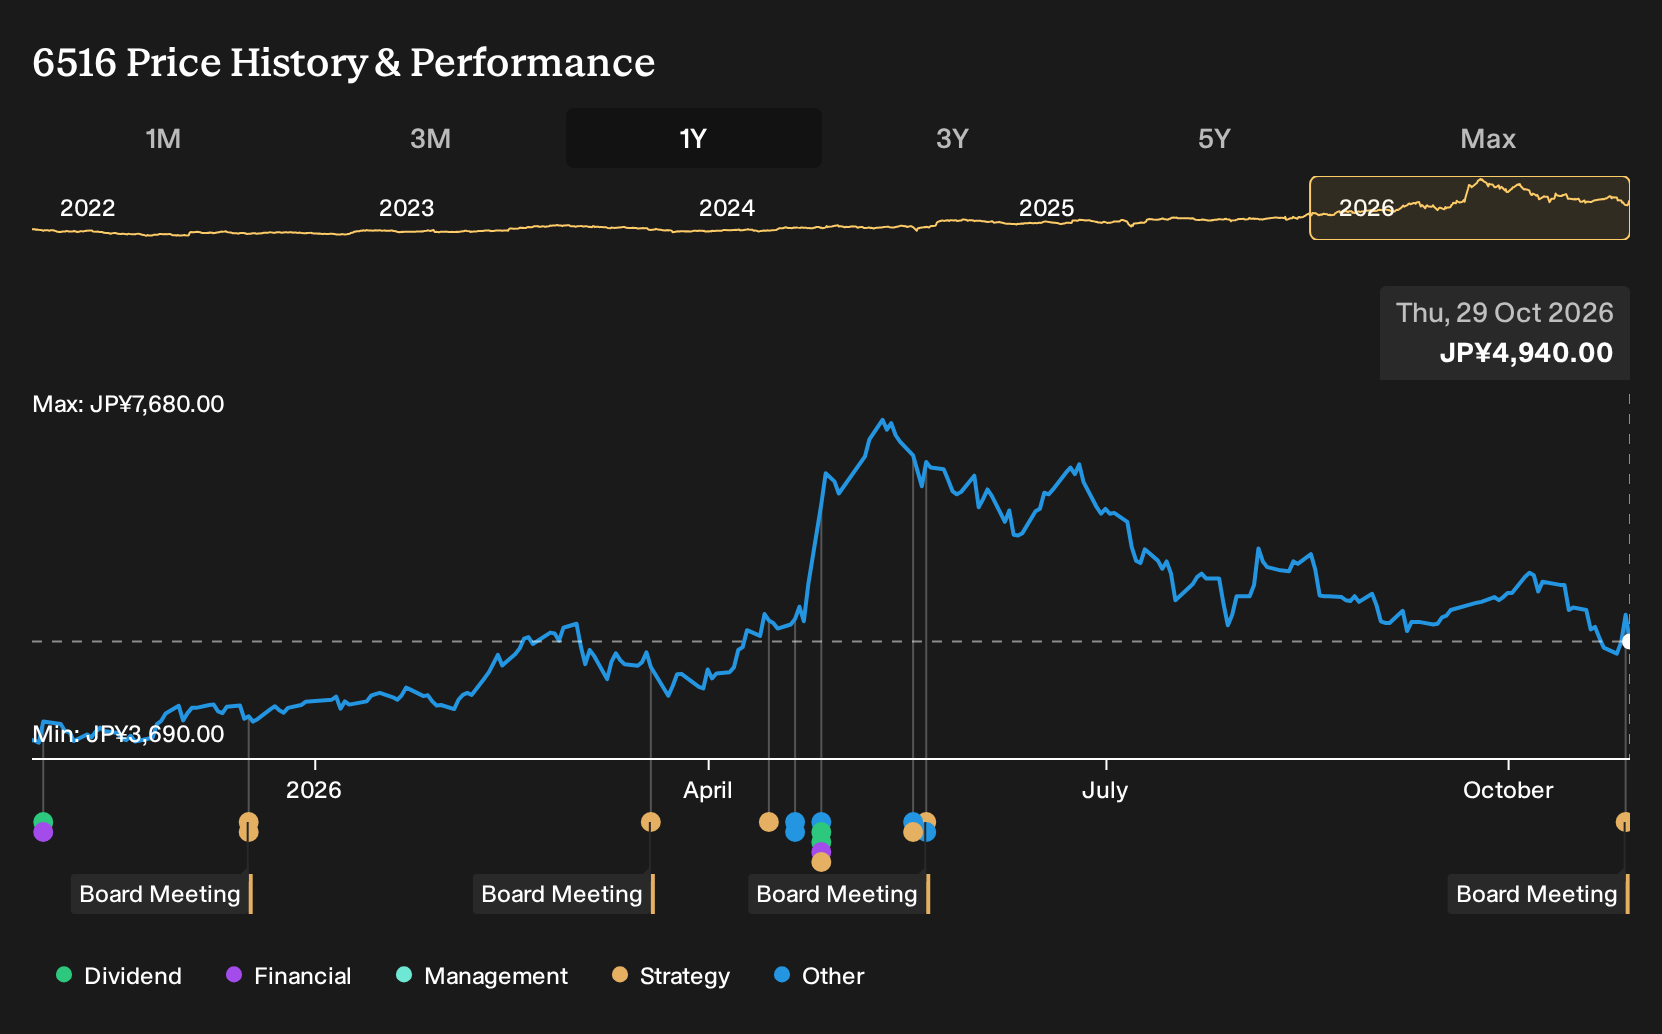
- Sanyo Denki held a board meeting on 28 October 2026 and resolved to pay an interim dividend based on a 30 September 2026 record date, while also revising the dividend forecast that had been released on 27 April 2026.
- The revised dividend outlook gives investors a fresh view of Sanyo Denki’s current cash generation and capital allocation priorities, which directly relates to how the business balances investment needs with shareholder returns.
- Next, the focus turns to how Sanyo Denki’s updated interim dividend plan could influence the investment narrative around its approach to capital discipline.
Scan how Sanyo Denki’s dividend update compares with other income ideas by checking our hand picked list of 29 dividend fortresses in the current market.
What Is Sanyo Denki's Investment Narrative?
Sanyo Denki appeals to investors who buy into a very simple idea. The business needs to keep turning strong demand for cooling, power and motion systems into consistent earnings, while reinvesting enough to stay relevant in sectors like ICT, semiconductors and factory automation. Recent profit growth and a P/E of 16.5x that sits below both an estimated fair P/E of 18.4x and a peer average of 19.1x suggest the market is still weighing that story carefully.
The new board decision on an interim dividend and revised forecast plugs directly into that belief. It hints at how management is weighing cash returns against capital intensive needs such as new equipment, product development and global sales support. Existing concerns around a 3.44% yield that is not well covered by free cash flow now feel more immediate, because the payout call is being made into a share price that has fallen around 10% over 90 days yet is still trading above one estimate of future cash flow value at ¥334.04 per share.
That said, sitting beneath the appeal of Sanyo Denki as a growing industrial supplier is one awkward issue that could reshape how this dividend story is viewed if ...
There's only one way to know the right time to buy, sell or hold Sanyo Denki. Head to Simply Wall St's company report for the latest analysis of Sanyo Denki's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Sanyo Denki research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sanyo Denki. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sanyo Denki's overall financial health at a glance.
Looking For More Ideas Beyond Sanyo Denki?
If Sanyo Denki has you thinking harder about income, value, and balance sheet strength, it can help to compare it with other businesses that have clear financial traits using the Simply Wall St Screener.
- For investors prioritizing resilience, start with a shortlist of companies that score well on stability using our 25 resilient stocks with low risk scores.
- If capital protection and solid finances matter most to you, compare Sanyo Denki with businesses that have stronger balance sheets via this list of solid balance sheet and fundamentals (23 results).
- Those looking for potentially mispriced quality can broaden their watchlist by reviewing a focused set of candidates through the 15 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com