


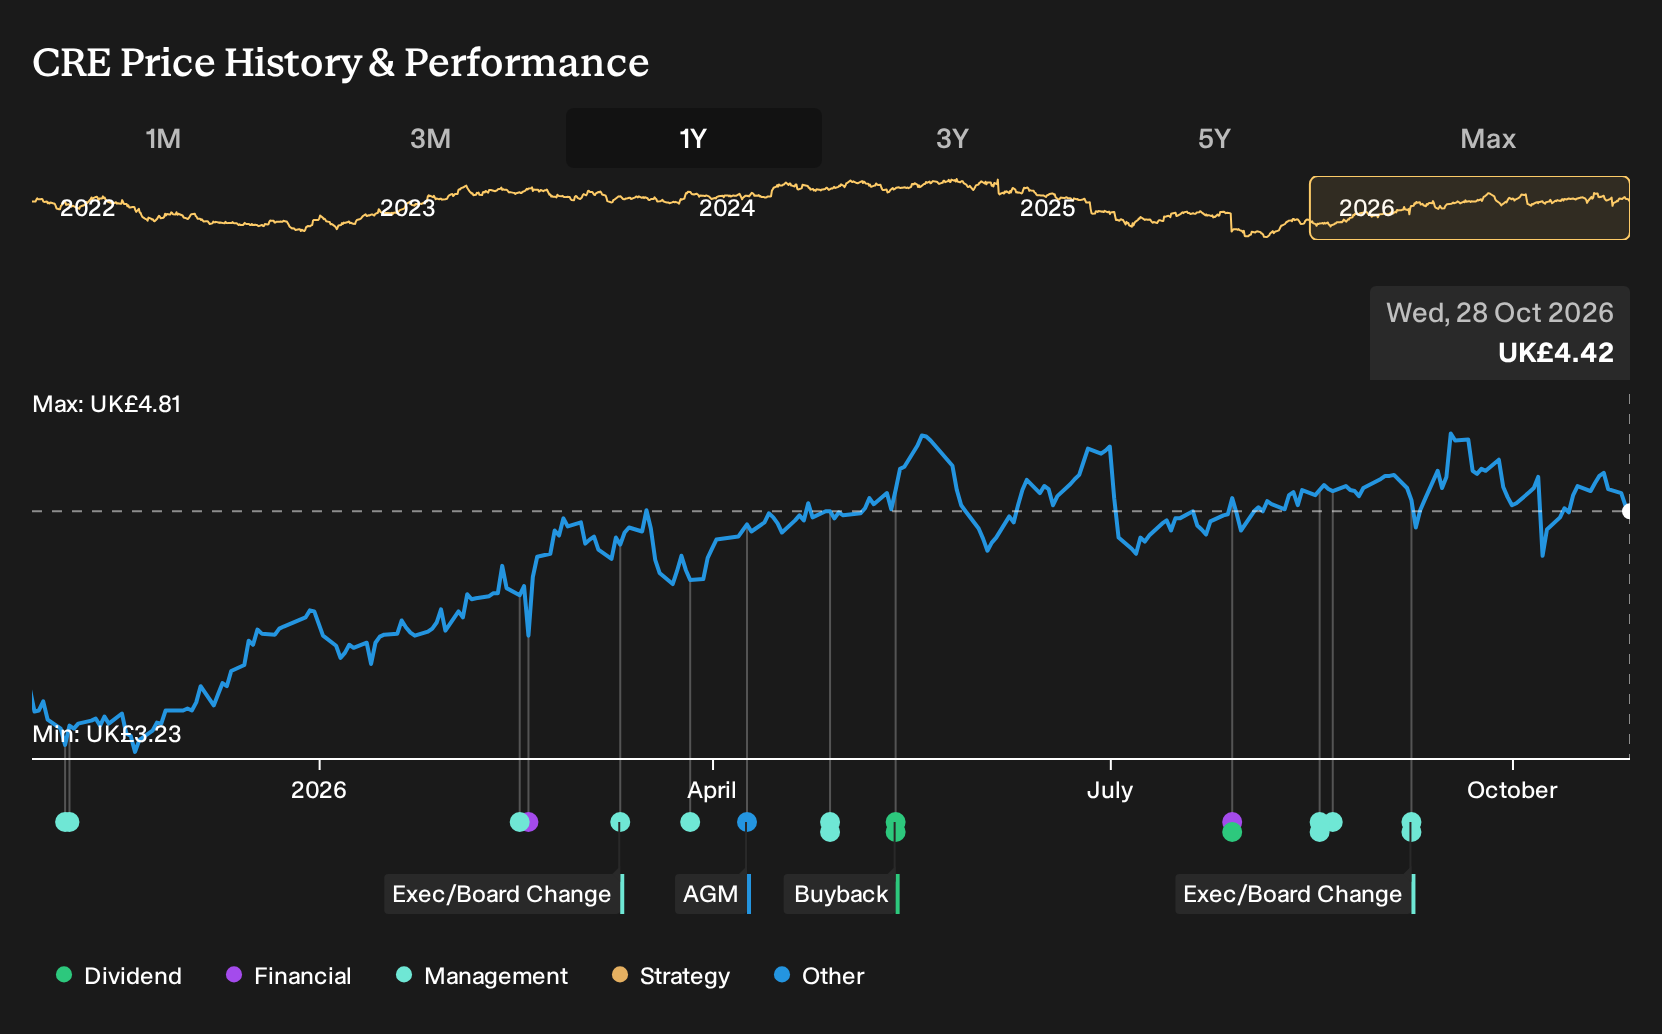
If you had bought Conduit on 28 October 2025 and simply sat tight, the result would look very different today. Investors who held Conduit over the past year are up 36.8%, including dividends. That outcome now sits against a split record at the start, with bullish analysts modelling higher margins from excess loss focus and digital analytics, while bears flagged North American catastrophe exposure and fierce competition. Which of those concerns and hopes deserved more weight at the time?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Conduit harder to judge, start where the gap is still open and scan 10 high quality undervalued stocks.
The Two Conduit Stories Investors Had To Weigh
The shares cost £3.43 at the start of the period, and Conduit sat between two very different stories about what might happen next.
The bullish narrative put Fair Value at £4.97, which was 45% above the start price. Supporters focused on excess of loss reinsurance and digital analytics, expecting 1.8% annual revenue growth with profit margins reaching 30.8% on a future P/E assumption of 3.6x.
The bearish view suggested Fair Value of £3, or 13% below the start price. This camp worried about North American catastrophe events and climate driven claims, and assumed revenue would decline 4.7% a year even as margins moved to 26.5% on a future P/E assumption of 4.0x.
What The Conduit Results Actually Tested
Conduit moved from a net income loss of US$13.5 million in H1 2025 to a profit of US$80.3 million in H1 2026, with net margin shifting from -3.4% to 20.3%. That stronger profitability supported the bullish focus on higher margins, although revenue slipped from US$402.8 million to US$394.6 million, so the evidence cut both ways.
The key assumption here was margin improvement. When you weigh another insurer, track whether net income and net margin move in the direction the upbeat case set out, even if the top line drifts.
What Conduit’s Price Now Asks You To Believe
Conduit trades at £4.42 today, after a 36.8% gain over the past year. The selected Narrative places its Fair Value above that level, arguing that the current valuation still reflects market doubt rather than full conviction in the recent shift.
The focus is on tighter underwriting, more excess of loss, casualty expansion and a larger investment book doing the heavy lifting. For that higher Fair Value to be reached, a buyer now would need to believe Conduit can keep protecting earnings through disciplined underwriting and an actively used retrocession programme.
"The ongoing shift by Conduit Holdings away from quota share deals and toward a higher mix of excess of loss contracts, which is already feeding through into a faster earning pattern for reinsurance revenue as seen in H1 2026, can continue to reshape the portfolio toward business that supports combined ratios and net margins."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 18% below our estimate - converts expanded production capacity and broader distribution into higher demand for wellness products.
- Company 2 - 31% below our estimate - grows fee income as more clients channel capital into real assets and tax efficient funds.
- Company 3 - 20% below our estimate - attracts senior lawyers leaving partnerships for a tech enabled, higher share of fees platform.
Three companies from the same screener. Open every one of the 10 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com