


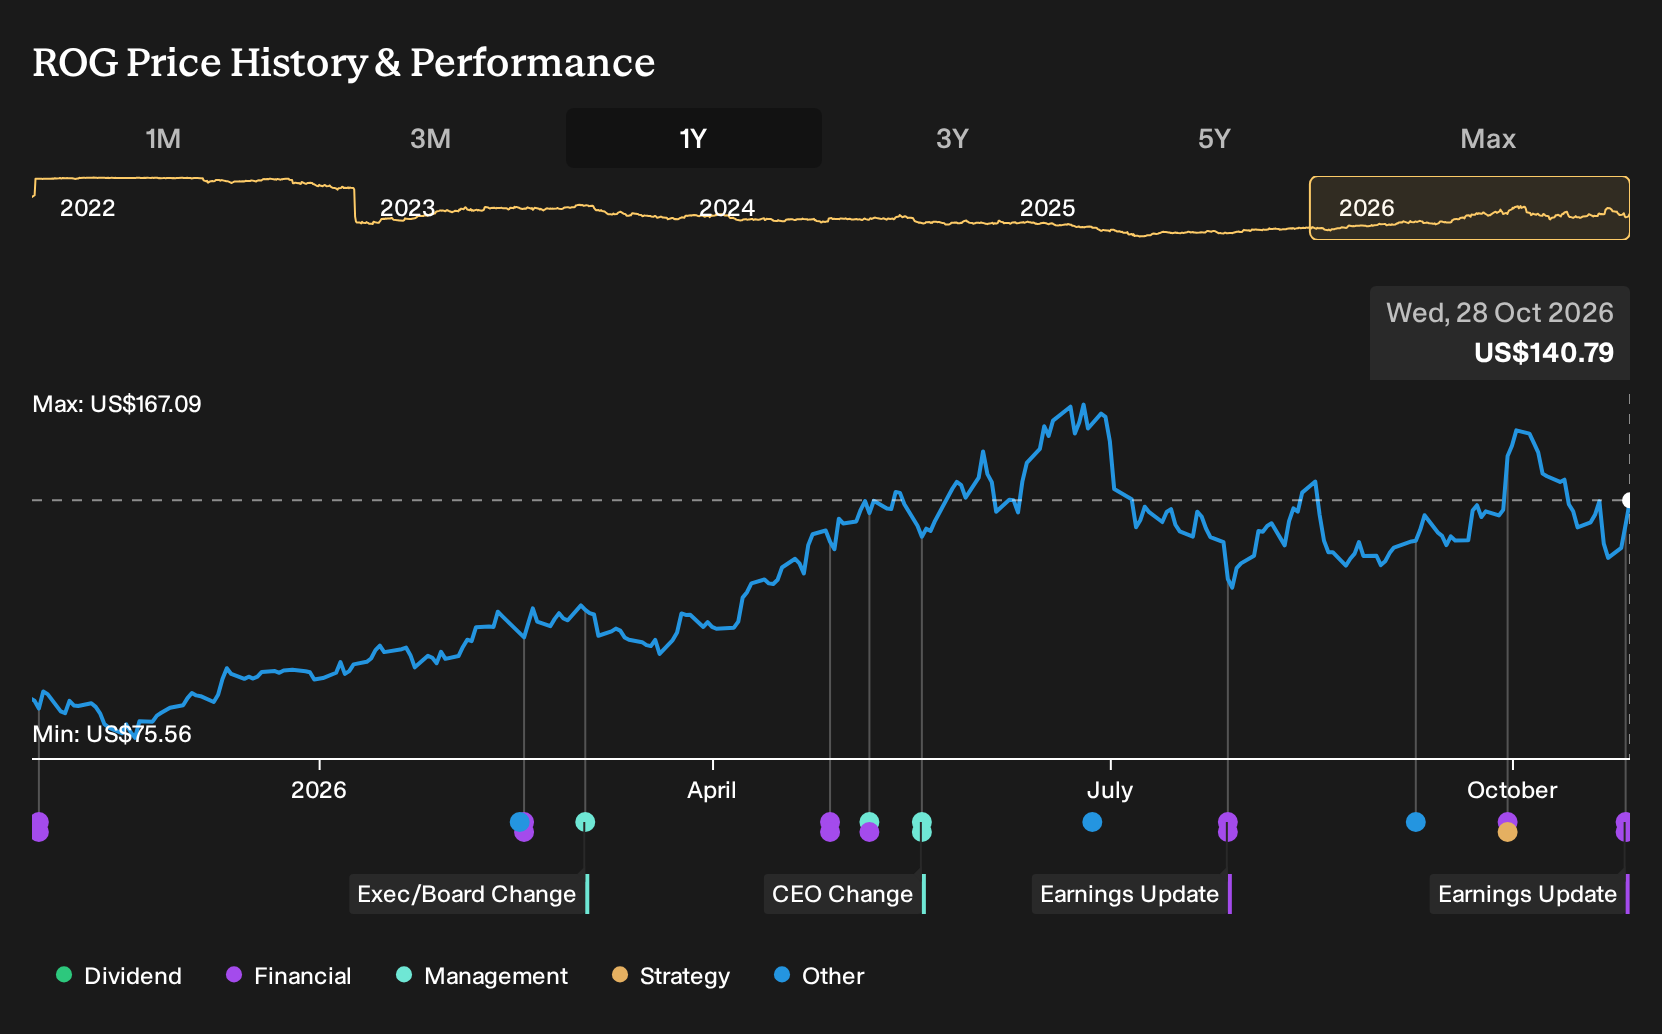
- Rogers Corporation reported third quarter 2026 basic earnings per share from continuing operations of US$1.27 and diluted EPS of US$1.26, with nine month EPS turning from a loss a year earlier to basic EPS of US$2.29 and diluted EPS of US$2.27.
- Alongside record profitability and improved operating margins, Rogers highlighted new design wins in electric vehicles, data centers, aerospace and energy storage, as well as a growing footprint in China that collectively reshape the earnings mix and capacity story.
- We will now look at how Rogers' stronger than expected Q3 earnings and higher Q4 profit guidance influence the investment narrative.
Rogers Investment Narrative Recap
For Rogers, the core belief is that its materials portfolio in EVs, AI data centers and high performance electronics can sustain healthy demand, while its new capacity and cost programs lift profitability. The latest quarter helped that case. EPS from continuing operations moved firmly into positive territory and margins improved, which supports the operational turnaround story.
The near term swing factor is execution on the ceramic substrate ramp and broader efficiency efforts. Strong Q3 adjusted margins and higher Q4 profit guidance ease some concern about underutilization and restructuring drag. The biggest risk still sits with weaker than expected EV power substrate demand that could keep the new Chinese facility under earning.
The most relevant fresh data point is Rogers' Q4 2026 outlook. Management guided net sales to US$215 million to US$225 million and expects adjusted EPS around US$1 at the midpoint of guidance, above prior analyst expectations. That pairing of revenue guidance roughly in line with Street numbers and stronger profit suggests cost and mix actions are gaining traction.
For you as a shareholder, the guidance ties directly back to the key catalysts. It tests whether recent AI data center and EV design wins can hold revenue, while margin programs offset any underutilization at the ceramic substrate plant. Execution against this Q4 bar will help clarify if current profitability is sustainable or still heavily reliant on short term efficiency gains.
Rogers' current earnings are reported at US$31.3 million, while analysts project revenues of US$1.1b and earnings of US$117.0 million by 2029. This reflects assumed annual revenue expansion of 9.2% and an earnings increase of about US$85.7 million from today.
Discover how Rogers' fair value indicates a 37% potential upside to its current price, which could close quicker than many investors expect.
Exploring Other Perspectives
One alternate view puts the curamik China ramp at the center of the Rogers story. The most optimistic analysts were already modeling about US$1.1b of revenue and US$125.7 million of earnings by 2029 before this Q3 beat. If you are bullish on that capacity payoff, these fresh numbers may push those forecasts even higher, so it is worth comparing several viewpoints.
Explore another Rogers fair value estimate, including one that suggests up to 37% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rogers research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rogers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rogers' overall financial health at a glance.
Looking For More Ideas Beyond Rogers?
Once you have formed a view on Rogers, it can help to line it up against other opportunities that fit your preferred style, whether that is value, income, or capital protection. The Simply Wall St Screener is built for that kind of comparison, so you can quickly filter for companies that match the fundamentals you care about most.
- If you want potential value opportunities backed by strong financial metrics, start with a curated set of 26 high quality undervalued stocks that may warrant a closer look.
- For investors who care most about getting paid while they wait, focus on income ideas drawn from our universe of 6 dividend fortresses that pair higher yields with business resilience.
- If capital preservation is your first filter, narrow your watchlist to a hand picked 32 resilient stocks with low risk scores that score well on balance sheet strength and risk factors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com