


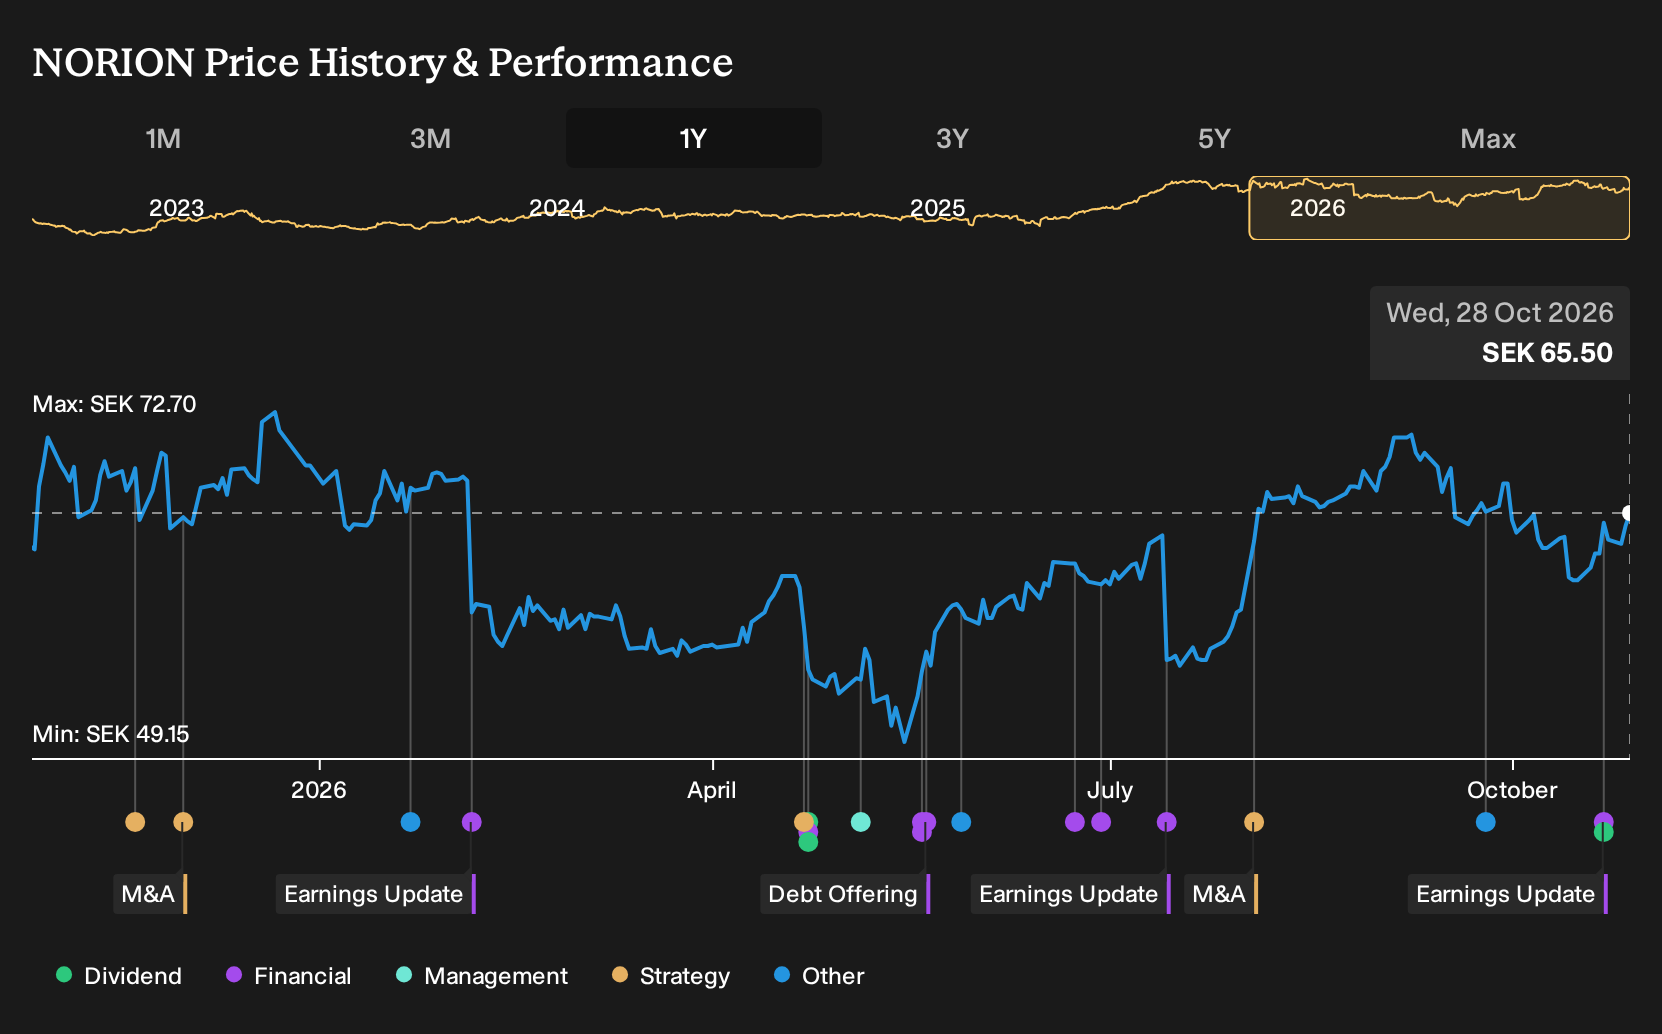
- Norion Bank AB reported third quarter 2026 results, with net interest income of SEK 914 million and net income of SEK 397 million, while nine month figures showed SEK 2,590 million in net interest income and SEK 931 million in net income.
- The bank paired quarterly earnings per share of SEK 2.18 with a Board decision to consider a share repurchase program, highlighting a focus on capital allocation alongside core lending profitability.
- Now the focus turns to what this Norion Bank earnings mix and potential buyback could mean for the broader investment narrative.
What Is Norion Bank's Investment Narrative?
To own Norion Bank, you have to be comfortable with a fairly plain banking story. The business leans on net interest income across corporate, real estate, consumer and payments activities, and the latest quarter shows that core lending can still support SEK 914 million of net interest income and SEK 397 million of net income. That is the operational backbone. The potential buyback the Board is considering adds a capital allocation angle. However, the real hinge for the next year remains credit quality and how efficiently Norion Bank converts its loan book into durable earnings.
In the short term, the mixed nine month picture, with lower net income and earnings per share than a year ago, keeps execution risk front and center. A repurchase plan could tighten the share count if approved. Even so, it would not change the day to day reality of running a bank that already carries a high level of bad loans and a relatively low allowance for those exposures. For an investor, the belief has to be that management can balance growth ambitions, capital discipline and risk appetite without eroding that earnings base further.
Even so, there is a tension inside that story once you look closely at ...
There's only one way to know the right time to buy, sell or hold Norion Bank. Head to Simply Wall St's company report for the latest analysis of Norion Bank's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Norion Bank research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Norion Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Norion Bank's overall financial health at a glance.
Looking For More Ideas Beyond Norion Bank?
If Norion Bank's latest earnings have you reassessing your watchlist, it can help to compare this lender with other businesses that show different mixes of balance sheet strength, valuation and income potential. The Simply Wall St Screener can surface groups of companies that share traits you care about so you can pressure test your thesis against a broader set of options.
- For investors who prioritize financial resilience first and share price second, scan a curated 229 resilient stocks with low risk scores that may align better with a capital preservation mindset.
- If you are hunting for quality at a reasonable price, consider reviewing a 191 high quality undervalued stocks that screens for stronger fundamentals relative to current market pricing.
- Readers who care most about durable income streams might want to research a 228 dividend fortresses that focuses on higher yielding payers with meaningful distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com