


- CleanSpark faces growing pressure on its core Bitcoin mining operations as analysts sharply cut earnings estimates, signaling concerns over costs, profitability and near term execution.
- The striking gap between upbeat brokerage ratings and weaker earnings projections highlights mounting questions about how resilient CleanSpark's business model is to tougher mining economics.
- We will now look at how CleanSpark's investment narrative lines up against this sharper earnings pessimism and what that implies.
Balance that CleanSpark focus by scanning a curated set of resilient Bitcoin and infrastructure peers in our 32 resilient stocks with low risk scores.
CleanSpark Investment Narrative Recap
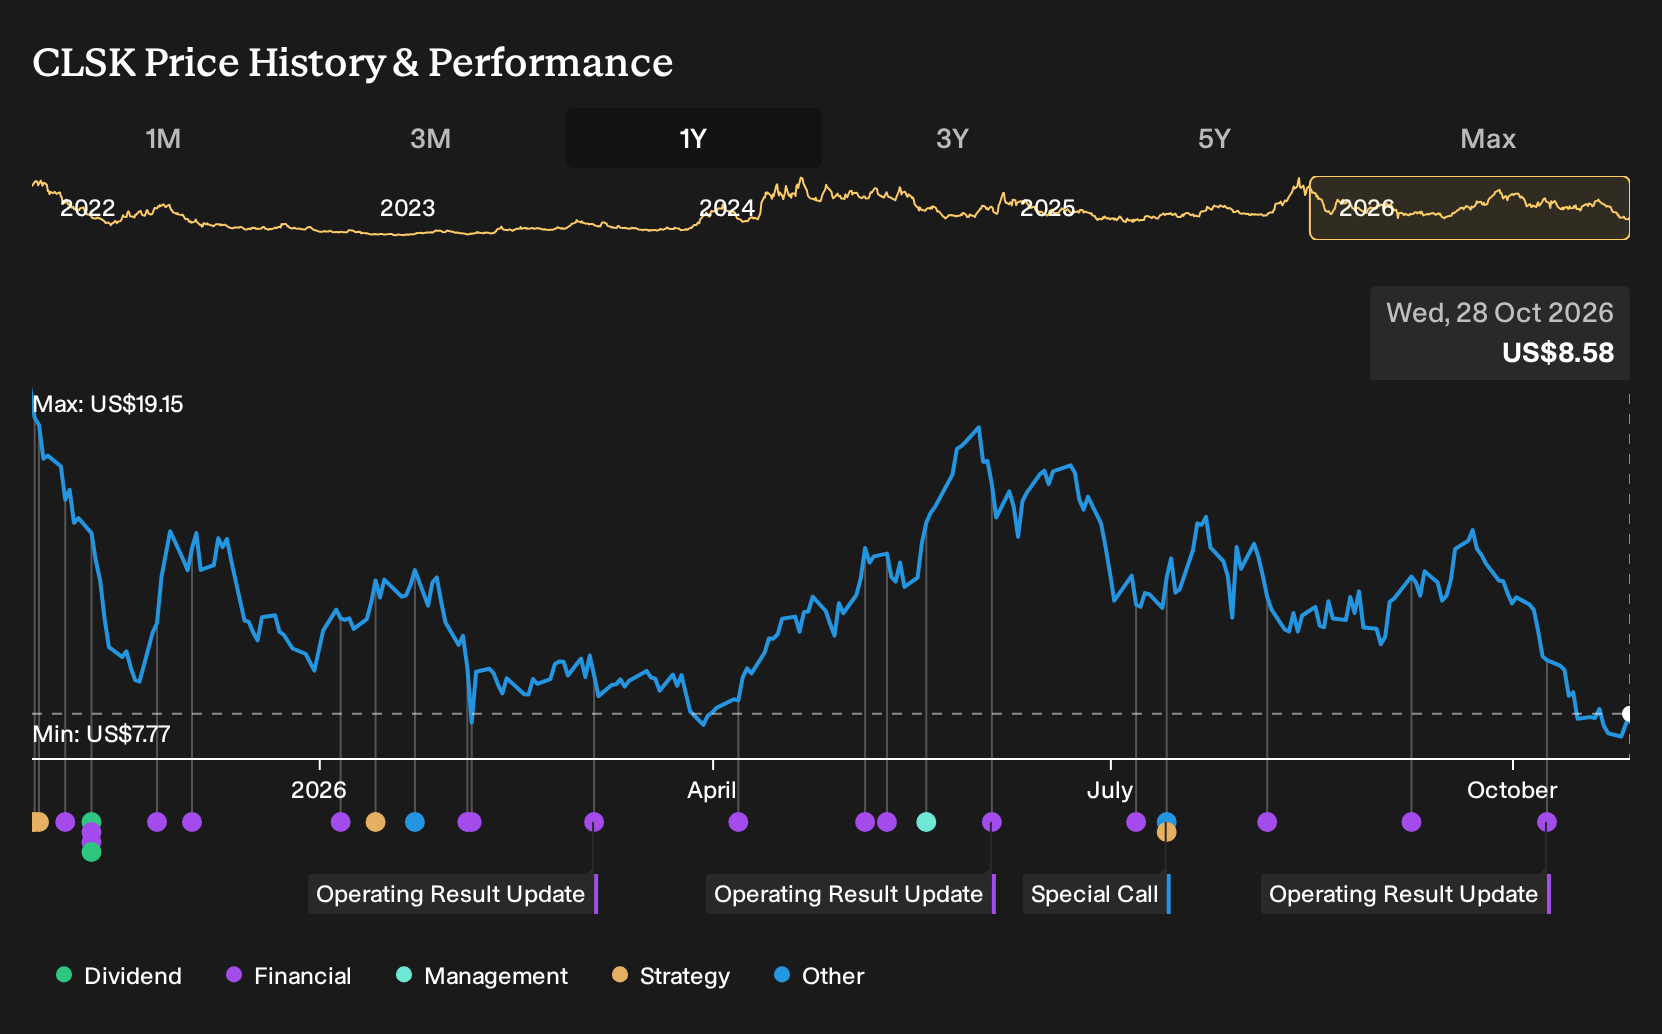
To own CleanSpark, you need to believe its Bitcoin mining footprint and AI infrastructure push can support sustainable cash generation despite volatile mining economics and heavy capital needs. The key short term swing factor is how efficiently those data centers run relative to Bitcoin prices and energy costs. Recent earnings downgrades highlight that this execution test is front and center.
The biggest current risk is that CleanSpark remains unprofitable and has less than one year of cash runway while still facing significant hardware and power investments. The new estimate cuts do not alter that core issue. They simply bring the funding and cost structure questions into sharper focus for anyone considering the stock.
The most relevant datapoint tied to this news is the sharp 57.1% cut to CleanSpark earnings estimates that now underpin a Zacks Rank of 4, or Sell. That shift directly challenges the idea that scaling hash rate and AI capacity will automatically translate into healthier margins in the near term. It puts operating efficiency under a spotlight.
For you, the practical takeaway is to connect that estimate reset back to real world constraints. CleanSpark is capital intensive, fully tied to Bitcoin mining economics and still loss making, with analysts not expecting profitability over the next three years. Any positive catalyst now likely needs to come from tighter cost control, disciplined CapEx and clear progress on cash generation.
CleanSpark's narrative projects US$857.1 million in revenue and US$98.0 million in earnings by 2029. This rests on analysts assuming 8.1% yearly revenue growth and earnings moving from a loss of US$1.0b today to a profit of US$98.0 million, an earnings swing of about US$1.1b over that period.
Uncover how CleanSpark's fair value indicates a 177% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view hangs on the Sandersville AI and data center lease. Bullish analysts were penciling in about US$1.2b of revenue and US$12.5 million of earnings by 2029, with a very high implied P/E multiple. That represents a far more optimistic CleanSpark story than the earnings cuts now in focus. It may also shift as new information lands.
Explore 4 other CleanSpark fair value estimates, including one that suggests as much as 215% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CleanSpark research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CleanSpark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CleanSpark's overall financial health at a glance.
Looking for more investment ideas beyond CleanSpark?
If the CleanSpark story has you rethinking risk, you can broaden your watchlist with other companies that match specific qualities you care about using the Simply Wall St Screener.
- If you want potential upside without taking on the weakest balance sheets, you might start with a curated 19 high quality undiscovered gems that pairs strong fundamentals with under-the-radar profiles.
- For investors who care most about financial resilience, consider focusing on businesses screened for durable funding and low leverage through our list of solid balance sheet and fundamentals (24 results).
- If steady income is high on your checklist, you can narrow the field to payout heavyweights by scanning our curated 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com