


Landstar System (LSTR) just posted third quarter 2026 results that combined strong US$1.51b in sales and higher earnings with a sharp hit from insurance and claims expenses, which weighed on profitability and investor reaction.
That insurance hit has reset expectations quickly, with Landstar System’s share price dropping about 18% over the past week and roughly 18% over 90 days, even though the 1 year total shareholder return is still up about 14%. This points to fading short term momentum after a stronger run. Spot 32 resilient stocks with low risk scores that, like Landstar System, are working through short term setbacks while still aiming to keep financial risk tightly controlled.
After a drop of roughly 18% in just a few days, Landstar System now sits at a very different entry point than it did before the insurance shock. Does that reset already reflect the risk, or is patience still worth it?
Most Popular Narrative: 7% Undervalued
Compared with the latest close at $138.80, the most followed narrative pegs Landstar System’s fair value at about $149.76, framing the recent insurance shock against a slightly higher long term anchor that uses an 8.23% discount rate.
Regulatory tightening around safety, fraud and carrier vetting has already led to a sharp reduction in approved third party carriers. As FMCSA and USDOT continue to raise the bar, Landstar System may need to spend more on anti fraud technology, insurance and compliance, which could lift insurance and operating costs faster than revenue and compress net margins over time.
See why 0 investors see Landstar System as 7% undervalued.
Result: Fair Value of $149.76 (UNDERVALUED)
Still, this bearish fair value hinges on liability costs and heavy haul concentration not surprising to the upside, which could shift sentiment on Landstar System quickly.
Find out about the key risks to this Landstar System narrative.
Another View: Multiples Point To A Richer Price Tag
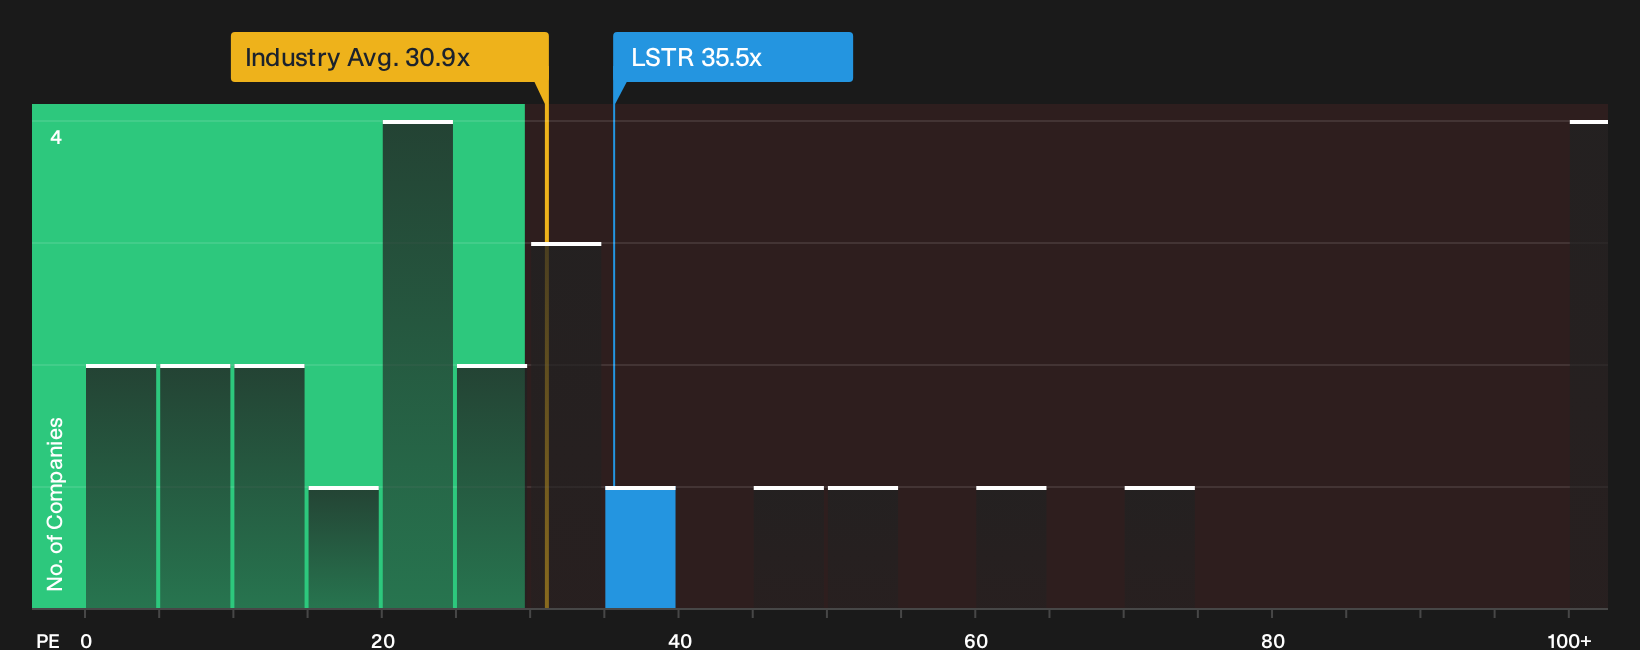
The fair value narrative pegs Landstar System at about $149.76, suggesting some upside from $138.80. The P/E picture tells a tougher story. LSTR trades around 35.5x earnings, compared with a fair ratio of 16.2x and an industry average of 32.6x, which lifts valuation risk if sentiment cools.
That kind of premium can persist for a while when investors are confident. However, it can also unwind quickly if earnings or insurance costs disappoint. Which signal do you trust more: the story or the sticker price multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece leans cautious, yet the Landstar System story clearly has brighter angles that bullish investors are watching closely. If you want to pressure test that optimism against the hard numbers and form your own view, start with the 3 key rewards.
Looking for more investment ideas beyond Landstar System?
Do not stop at one freight specialist when the broader market is full of potential opportunities. Casting a wider net can sharpen your perspective and highlight alternatives you might otherwise miss.
- Target resilient balance sheets and calm your risk radar by scanning a list of solid balance sheet and fundamentals (24 results) that already filters for financial strength and stability.
- Hunt for quality at a fair sticker price by reviewing a 26 high quality undervalued stocks that blends strong fundamentals with room for potential upside.
- Build a portfolio that pays you back regularly by checking a 6 dividend fortresses built around higher yielding businesses with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com